Think about the last time a checkout hung, or a refund took three emails and nine days. Did you go back? Most people don’t.
That single moment is why generative AI keeps showing up in payment stacks. It catches fraud earlier, it makes support feel less like a queue, and it takes a lot of dull reconciliation work off people’s desks. Stick with manual review and rule tables from four years ago, and you pay twice: once in operating cost, once in customers who quietly stop trusting you.
So here’s what this piece covers: what generative AI in payments actually is, what it buys a business, where it’s already working, and how to put it in without breaking what you have.
What is Generative AI in Payments?
Strip away the marketing and it’s this: AI and machine learning models doing the parts of a transaction that used to run on fixed rules and a human with a review queue. Traditional payment systems check a box, flag a threshold, escalate. AI-powered ones don’t work that way.
They read transaction data continuously and adjust. Fraud patterns shift, the model shifts with them. Customer behaviour changes, the experience changes too. Routine work gets handled without a ticket. The practical result is a system that stays accurate as conditions move, instead of one that slowly goes stale between rule updates.
Key Advantages of Using Generative AI in Payment Systems
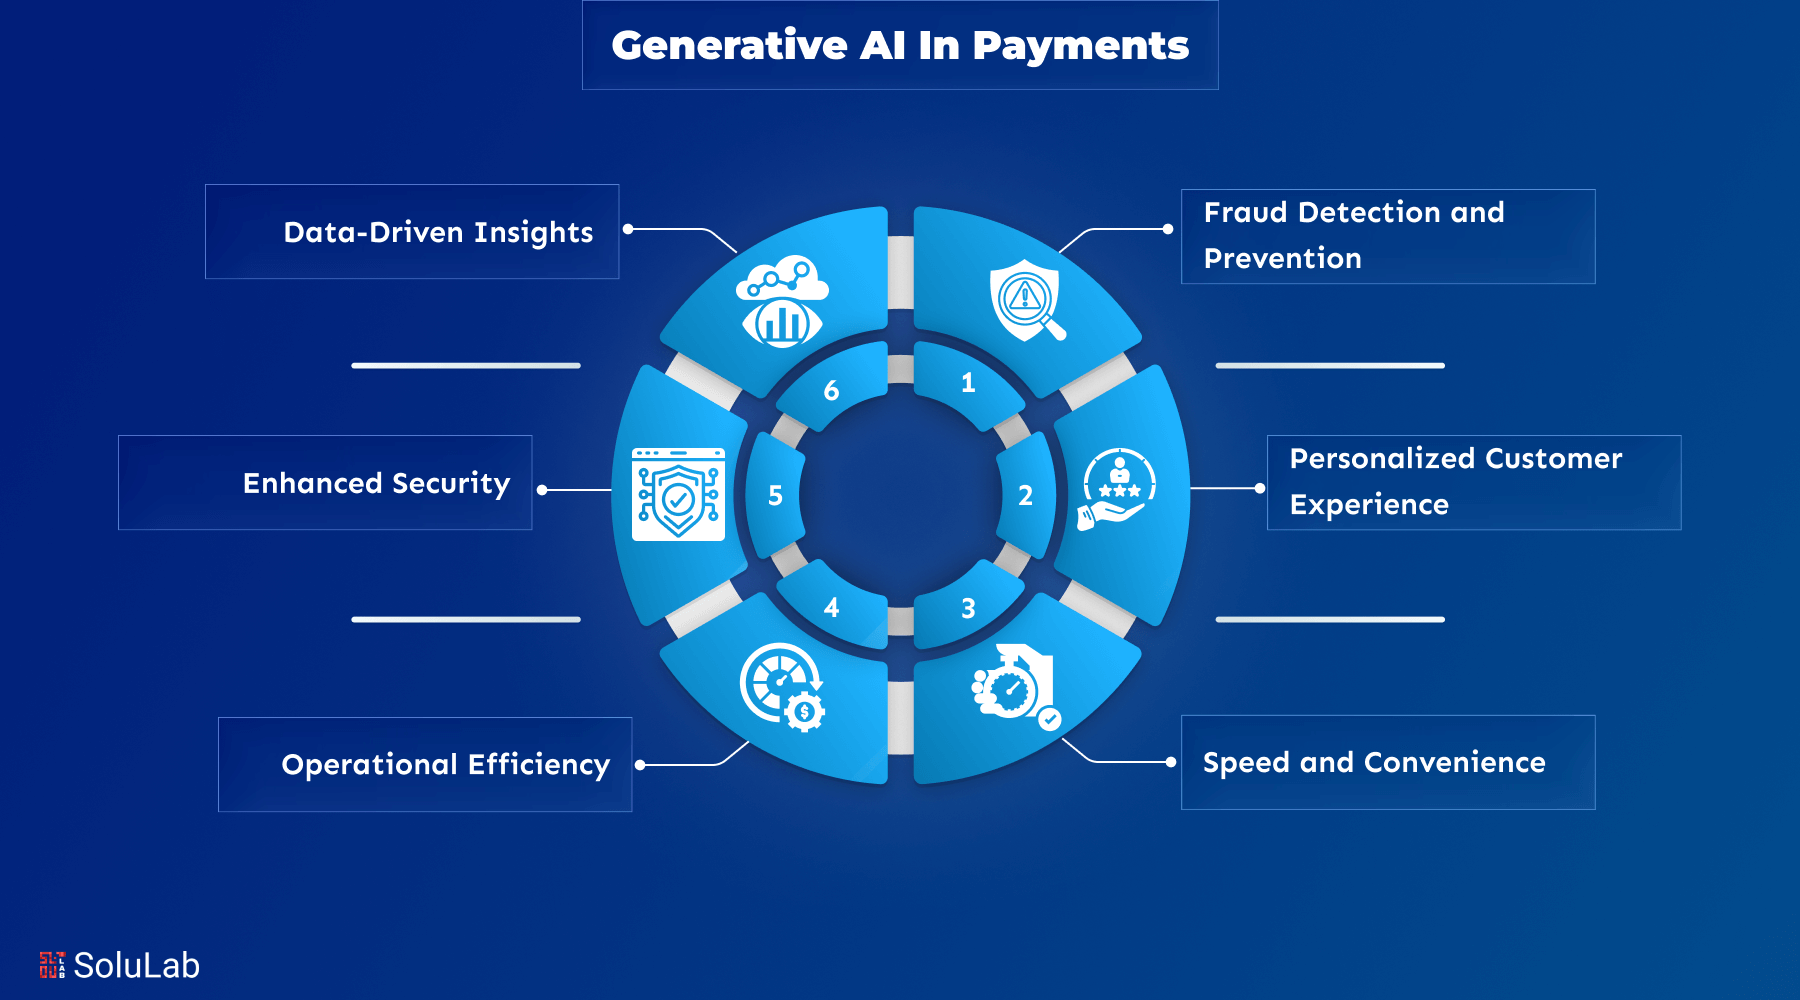
Payments got hit by generative AI the way most data-heavy industries did, just with higher stakes attached to being wrong. Security, speed, and the experience your user actually feels all improve when the model is doing the work. The list of AI payment benefits below is the one that matters commercially:
1. Fraud Detection and Prevention: Generative AI reads enormous volumes of transaction data and picks out the shapes that look like fraud. Because it keeps learning from fresh data, it spots anomalies as they happen rather than in a Monday morning report. That catches losses before they land, which protects the cardholder and saves financial institutions a great deal of money every year.
2. Personalized Customer Experience: Watch what a user does and you can shape what they get. AI-driven chatbots can answer questions, walk someone through a stuck payment, and handle support at two in the morning. The same signal drives recommendations built on what a person has actually bought before, not what a segment is assumed to want. People stay for that.
3. Operational Efficiency: The least glamorous of the AI payment benefits, and often the fastest to show up on a budget line. Invoice handling, transaction reconciliation, first-tier support: all of it is repetitive, and all of it can be automated. Costs drop, and the people you already employ go do work that compounds.
4. Enhanced Security: Stronger encryption on one side, biometric checks on the other. Facial recognition and fingerprint scanning make it much harder for the wrong person to reach sensitive financial data, which is the whole point. Fewer doors left open means fewer breaches to explain later.
5. Speed and Convenience: AI-powered payment gateways approve or decline inside milliseconds. Checkout stops being a pause. Users barely notice it happened, and that is exactly the outcome you want, because in a digital economy the checkout nobody remembers is the checkout nobody abandons.
6. Data-Driven Insights: Every transaction is a data point about behaviour and market movement. Read enough of them and pricing decisions stop being guesswork, product bets get sharper, and you build things people were already signalling they wanted. Revenue tends to follow, along with a position competitors have to work to match.
7. Cost Reduction: Manual processing is expensive. Fixing manual processing mistakes is more expensive. Payment AI handles high volumes accurately, which cuts both lines at once, because fewer human touches mean fewer costly errors to unwind.
8. Scalability: Growth breaks traditional systems. They need upgrades, migrations, downtime windows nobody enjoys planning. AI solutions absorb rising transaction volume and shifting demand with far less disruption, which is why growing businesses gravitate toward them.
9. Regulatory Compliance: Compliance teams are watching for suspicious activity around the clock, and there is only so much a human roster covers. Generative AI monitors transactions continuously and keeps institutions aligned with legal standards. That matters most under anti-money laundering (AML) and know-your-customer (KYC) regulations, where missing something has a price tag attached.
10. Innovation and Competitive Advantage: Adopt early and you get to ship things your competitors can’t yet. AI-driven payment systems open business models and services that simply were not available before, and that becomes the habit a company builds on.
Put together, those advantages compound: tighter security, experiences that fit the individual, leaner operations, decisions grounded in real data. And the role of Payment AI only grows from here. The industry is moving toward systems built around the customer rather than around the ledger, and the technology is what makes that shift affordable.
Which Businesses are Getting Benefits of AI-Powered Payments?
Less fraud, better experiences. That combination pays off differently depending on what you sell. Here’s where generative AI in payments earns its keep:
- B2B (Business-to-Business): AI simplifies complex invoicing, automates reconciliation, and cuts the delays that sour vendor relationships. Cash flow gets easier to forecast when invoices stop drifting.
- E–commerce: Faster checkout, fewer abandoned carts, sharper fraud detection. Shoppers get a smoother run at buying; merchants stop bleeding money on chargebacks.
- SaaS (Software-as-a-Service): Subscription billing runs itself, reminders get timed to the individual, and churn signals show up before the cancellation does. Recurring revenue holds steady for SaaS businesses and users stop getting nagged at the wrong moment.
- Retail: In-store and online both benefit. Offers tuned to the shopper, checkout that doesn’t drag, and fraud protection to make online transactions secure for retail and hospitality. Loyalty goes up; so do sales.
- Fintech & Banking: Fraud monitoring, predictive credit scoring, automated settlement. Transactions move faster and break less often, which is most of what this sector is judged on.
Top Use Cases of Generative AI in Payments
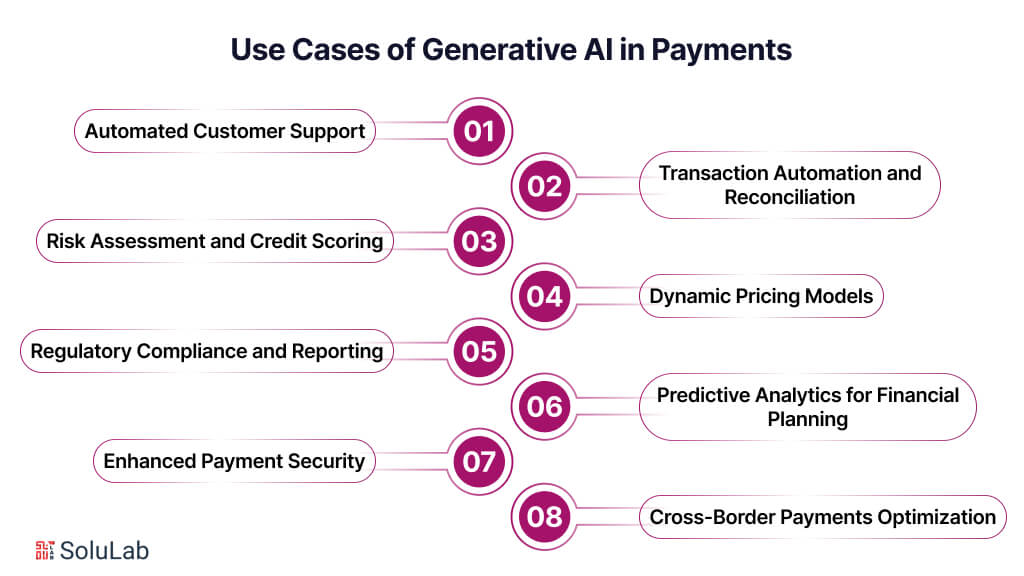
Theory is fine. What follows is the working set: the generative AI use cases in banking and payments that teams are actually building right now.
- Automated Customer Support: Virtual assistants field the inquiries that used to sit in a queue overnight. Password resets, balance checks, pushing a payment through: handled, around the clock, without pulling an agent off something harder.
- Transaction Automation and Reconciliation: Processing and matching transactions is repetitive work that humans do worse the longer they do it. Hand it to AI and both the cost line and the error rate come down for banks and financial institutions.
- Risk Assessment and Credit Scoring: Pull in a far wider range of data points and creditworthiness gets easier to read. Lenders make better calls, and borrowers get offered products that fit their actual financial situation rather than a crude band.
- Regulatory Compliance and Reporting: AI watches transactions for suspicious behaviour and writes the reports regulators expect. Anti-money laundering (AML) and know-your-customer (KYC) obligations get met consistently, which keeps fines and legal trouble off the table.
- Enhanced Payment Security: Biometric authentication plus anomaly detection. Facial recognition or a fingerprint confirms who is really on the other end, so sensitive financial information stays with the person it belongs to.
- Dynamic Pricing Models: Market trends, customer behaviour, competitor moves. Generative AI reads all three and lets banks and payment providers adjust pricing in real time instead of quarterly, which protects both revenue and position.
- Predictive Analytics for Financial Planning: Forecast someone’s income and expenses and you can tell them something useful about next month. AI tools turn that into budgeting, saving, and investing suggestions people can act on, which changes financial advice from an annual meeting into a running conversation.
- Cross-Border Payments Optimization: International transfers are slow and expensive for reasons that are mostly routing. AI reads exchange rates and payment paths, picks the better route, and gets the money there faster and cheaper for everyone involved
Taken together, these generative AI use cases in banking and payments point one direction: financial services that are safer, quicker, and far less annoying to use. More applications are coming. The way we move money is changing underneath us, and most people will only notice because it got easier.
How to Integrate Generative AI in Payments?
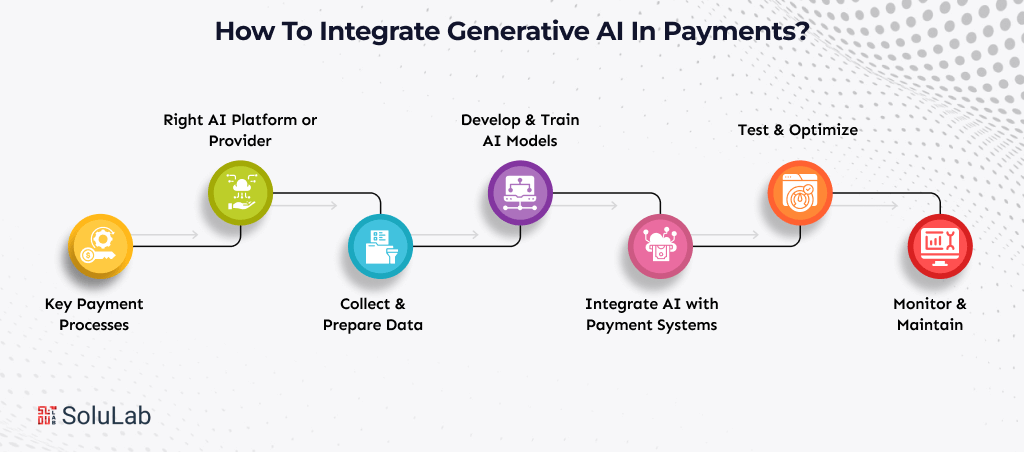
Better fraud detection, automated processes, happier customers. Getting there is less mysterious than it sounds. Here is the order that works.
Step #1: Identify Key Payment Processes
Walk your own payment workflow end to end and mark where AI actually helps: fraud detection, customer support, refunds, transaction personalization. In practice this is where most teams stall, because everything looks like a candidate. Pick the one that hurts most.
Step #2: Choose the Right AI Platform or Provider
Pick a generative AI solution or fintech partner that fits how your business already runs and takes secure payment processing seriously. The real question to ask: how cleanly do their APIs sit against the system you have today?
Step #3: Collect & Prepare Data
Pull your historical transaction data, customer interactions, and fraud records together. Then clean and structure it, properly, because a model trained on messy inputs will happily give you confident nonsense. Keep data privacy obligations in view the entire time.
Step #4: Develop & Train AI Models
Build AI models around the processes you picked in step one. Generative AI is useful here for simulating scenarios you have not seen yet, predicting fraudulent behaviour, and producing customer insights that hold up.
Step #5: Integrate AI with Payment Systems
Wire the models into your payment gateway, your app, your backend. The failure mode to watch for is the handoff: AI, transaction systems, and customer-facing interfaces all need to talk without dropping context.
Step #6: Test & Optimize
Pilot it. Watch fraud detection accuracy, processing speed, and what customers say about the experience. Then tune. This part never quite finishes, and that’s fine.
Step #7: Monitor & Maintain
Deployment is the start, not the finish. Track performance, feed AI models new data as it arrives, and keep security protocols current. A payment system earns trust by staying boring for years.
Real World Examples of Generative AI in Payments
Names you already know, doing this in production right now.
Visa
Visa is betting big on GenAI, with more than $100 million committed to startups rethinking how payments work. It is also piloting AI agents that make purchases on a user’s behalf, inside budgets the user sets.
Stripe
Stripe runs AI-powered chatbots and virtual assistants across payment queries and refunds. The responses read like a person wrote them, which is the trick: support scales without turning into a phone tree.
PayPal
PayPal builds recommendations and promotions off how people actually spend. Generative AI writes the tailored insight around it, and engagement holds because the suggestion is relevant rather than broadcast.
Mastercard
Mastercard watches transactions as they move, flags patterns that don’t fit, and stops fraudulent payments before settlement. Generative AI sharpens the prediction, catching suspicious activity earlier and with fewer false alarms than rule-based systems managed.
SoluLab Transforms Banking and Finance with Gen AI
Challenge
Banks are squeezed from several sides at once: customers expect more, too much of the work is still manual, risk keeps shifting, regulations keep changing, and cyber threats keep arriving.
Solution
SoluLab put Gen AI to work on the manual tasks, built personalized customer experiences on top, and hardened cybersecurity underneath, so the bank could run leaner without cutting corners.
Impact
- 3x increase in customer satisfaction with personalized services.
- 70% faster processes, cutting operational costs.
- 98% fewer cyber threats, ensuring data safety.
Conclusion
Fraud slips through. Approvals crawl. Reconciliation eats a week. Traditional systems were built for a slower version of this business, and both merchants and their customers feel it. The gap is widening, too: competitors already running AI through their operations are pulling ahead while everyone else debates the budget.
Put generative AI into the payment path and you get fraud prevention that thinks, personalization that happens in the moment, workflows that run themselves, and approvals that land before the user looks up.
SoluLab, a top generative AI development company, builds this into payment processing systems so fewer fraudulent transactions get through in the first place. Get in touch with us today!
FAQs
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.