Money went digital decades ago. The permission layer never did. Banks, brokers, and clearing houses still decide who gets an account, what a transfer costs, and which hours the rails stay open. Decentralized Finance (DeFi) is the attempt to pull that layer out entirely and rebuild the same functions on open networks, and the Web3 era is where the attempt stopped being a thought experiment. No single company sits at the middle of it. The people using it govern it, through code anyone can read. That one change is what makes the books checkable and the settlement quick.
Underneath sits a blockchain: a shared ledger, copied across thousands of machines, where a recorded transaction stays recorded. Strip that away and none of the rest stands up. What runs on top is built for ordinary users rather than institutional trading desks. Open a wallet, connect, transact. No credit committee, no minimum balance, no branch that shuts at four.
Could this rewire finance? Plausibly. Cheaper access, fewer gatekeepers, ledgers you can audit yourself instead of taking a statement on faith. But be straight about the stage it is at. DeFi is young, rough in places, and still arguing with itself about basics. What is genuinely on the table is the question of who controls money and on whose terms.
Decentralized Finance (DeFi) in the Web3 Era
Web3 is the third act of the internet, and its pitch is simple enough: you hold your own keys, your own data, your own assets, and the apps talk to each other instead of walling themselves off. DeFi lives inside that pitch and applies it to money. Financial services come from decentralized applications, dApps, rather than a bank’s back office. Lending, swapping, borrowing, collateral, all of it runs as code on a blockchain where every entry is visible and nothing gets quietly edited later.
Think of Web3 as plumbing and DeFi as the fixture you actually touch. The plumbing gives you identity you own, storage nobody else controls, and networks that do not need a company in the middle to keep working. Bolt the two together and you get financial products that settle faster, cost far less to operate, and stay open to anyone with a connection and a wallet. DeFi in Web3 gives those dApps somewhere dependable to run.
Understanding Decentralized Finance (DeFi)
DeFi is finance rebuilt without the gatekeeper. Blockchain does the recordkeeping, so two strangers can transact directly and neither needs a bank standing between them vouching for the other. Nobody signs off on your participation. You just connect. DeFi platforms aim to provide inclusive and accessible financial services to a global audience.
Decentralization is the whole point, which means no central authority runs the show. Smart contracts do the running instead. A smart contract is an agreement written as code, and it executes itself the moment its conditions are met. That is where the middleman goes: not negotiated away, but engineered out. Costs drop. What is left is visible to anyone who wants to read it.
Evolution of DeFi in the Web3 Era
The DeFi in Web3 era is a different phase of the internet, one built out of decentralized protocols and apps that answer to their users. DeFi is doing a lot of the heavy lifting in that shift. Blockchain plus smart contracts gives you financial infrastructure that works without trusting anyone in particular, and where the rules are legible to all sides. Put those two threads together and you get room for things that were not previously buildable.
Web3 keeps maturing, and security, privacy, and user control improve along with it. Projects built on those principles start from a firm position: your assets are yours, your data is yours, and no operator sits between you and either one.
Significance of DeFi in the Current Financial Landscape
Here is why any of this matters. Large parts of the world’s population sit outside the traditional financial system, blocked by paperwork, geography, minimum balances, or simply not being a profitable customer. DeFi does not ask those questions. Lending, borrowing, trading: the protocol serves whoever shows up, and no one holds the power to switch you off.
People have also grown noticeably less relaxed about what companies do with their data, and that mood carries straight into Web3. DeFi fits it. You run your own financial activity instead of asking a centralized institution for permission to run it. Scale that far enough and the shape of finance itself changes: more people inside it, fewer arbitrary reasons to be kept out.
Core Concepts of Decentralized Finance
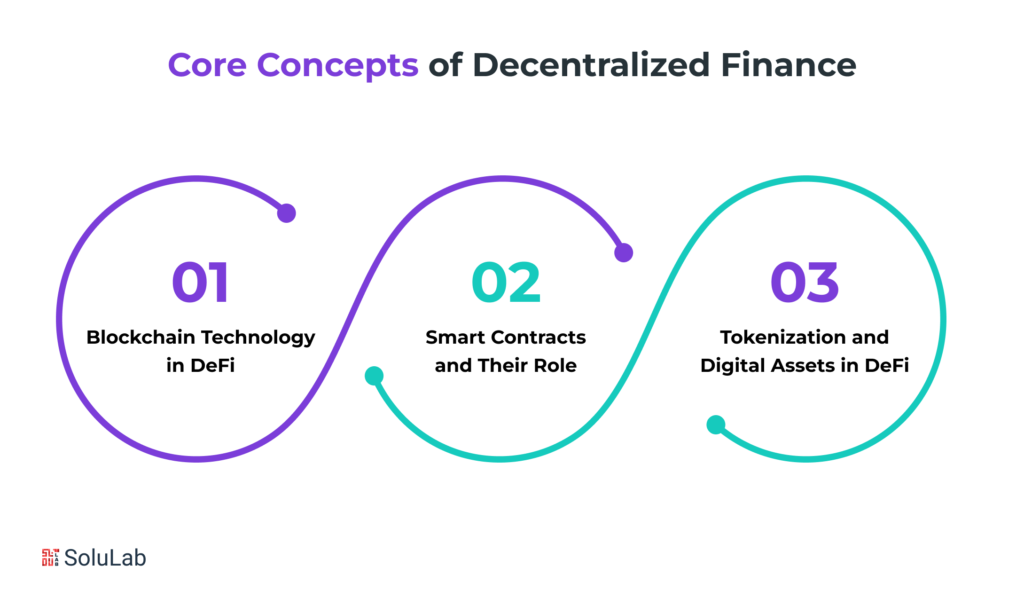
Three pieces carry almost all the weight in DeFi: the blockchain, the smart contract, and the digital asset. A blockchain is a distributed ledger that records transactions openly and keeps them safe from tampering. A smart contract is code that lives on that ledger and enforces its own terms. A digital asset is value in purely digital form, a cryptocurrency or a token. Learn those three and the rest of the vocabulary stops being intimidating.
Combine them and you get a financial system with nobody in charge of it. Transactions clear without a third party verifying anyone’s good faith, because the contract does the verifying. The record is public by default, so you can check the math rather than request a statement. And the combination makes room for instruments that had no earlier equivalent, such as a decentralized exchange or a lending pool that runs itself. This is early work. The potential is real, and so is the distance still to cover.
Blockchain Technology in DeFi
Everything in decentralized finance rests on the blockchain. It is distributed, it is immutable, and those two properties are what make a financial record trustworthy without a trusted institution behind it. It is also the surface smart contracts are written onto, each one a set of rules that fire when their conditions are met. Lending, borrowing, trading: the process runs itself, with no intermediary taking a cut for standing in the middle.
Smart Contracts and Their Role
Smart contracts are what DeFi applications are made of. Write the conditions, deploy the code, and the transaction executes when those conditions hold, with no one’s approval required. In DeFi in Web3, that pairing gets stronger still. You commit funds knowing the agreement will run exactly as written, not as some institution later decides to interpret it. The code is the terms. That is the deal, for better and occasionally for worse.
Tokenization and Digital Assets in DeFi
Tokenization means taking something that exists in the real world and representing it as a digital token on a blockchain. For DeFi, that is a big deal. A building, a warehouse of commodities, an asset that normally trades in one indivisible lump becomes something you can split into pieces and trade on a network. Small buyers can hold a slice. Assets that used to sit frozen for years start moving, and far more of them become usable inside Decentralized Finance Web3.
Key Components of the DeFi Ecosystem
Look at what people actually use day to day and three things dominate: the decentralized exchange, automated market makers, and non-fungible tokens (NFTs) threaded through both. Together they let you trade without an intermediary, earn by supplying liquidity, and put one-of-a-kind assets to work. Decentralized exchange platforms (DEXs) let you swap cryptocurrencies with no central authority approving the trade. Compare that with a centralized exchange, which is a company, with a balance sheet and a support queue and a list of things it can freeze. A DEX has fewer of those failure points, and nothing about it depends on the operator behaving well.
Automated market makers (AMMs) are a flavor of DEX that prices assets with an algorithm rather than an order book. Fewer moving parts, faster fills, and no one matching buyers to sellers by hand. They also do not sit on your funds the way a traditional venue does, which removes an entire category of thing that can go wrong. Non-fungible tokens (NFTs) are the other piece. Each one is unique and cannot be copied, which is what lets them stand in for art, collectibles, and in-game items. They trade on DEXs, and they can feed liquidity into AMMs too.
Decentralized Exchanges (DEX)
decentralized exchange platforms match traders with each other directly and skip the intermediary altogether. Your keys never leave your hands, and neither do your funds, not at any point in the trade. Building decentralized exchange infrastructure into the DeFi ecosystem follows from the same instinct running through all of this: delete the single point that can fail, and give people control of what they own.
Decentralized Lending and Borrowing Platforms
DeFi lending platforms work in two directions. Put assets in and earn interest from the people borrowing them, or post collateral and borrow against it. Smart contracts handle the whole loop: matching, interest, collateral, liquidation. No loan officer, no application. What the Web3 era adds is custody that never leaves you, and that is most of why people are willing to lend through a protocol they have never met.
Automated Market Makers (AMM) and Liquidity Pools
Automated Market Makers are what keep a decentralized exchange liquid, and they do it with a pricing formula rather than a book of resting orders. You trade against the contract itself. Liquidity providers deposit assets into a pool and collect a share of the fees every trade generates. It is an odd design if you come from traditional markets, and it works. Nobody has to be on the other side of your trade at that exact second, which is precisely the constraint that made small markets unusable inside the DeFi ecosystem.
Challenges and Opportunities in DeFi
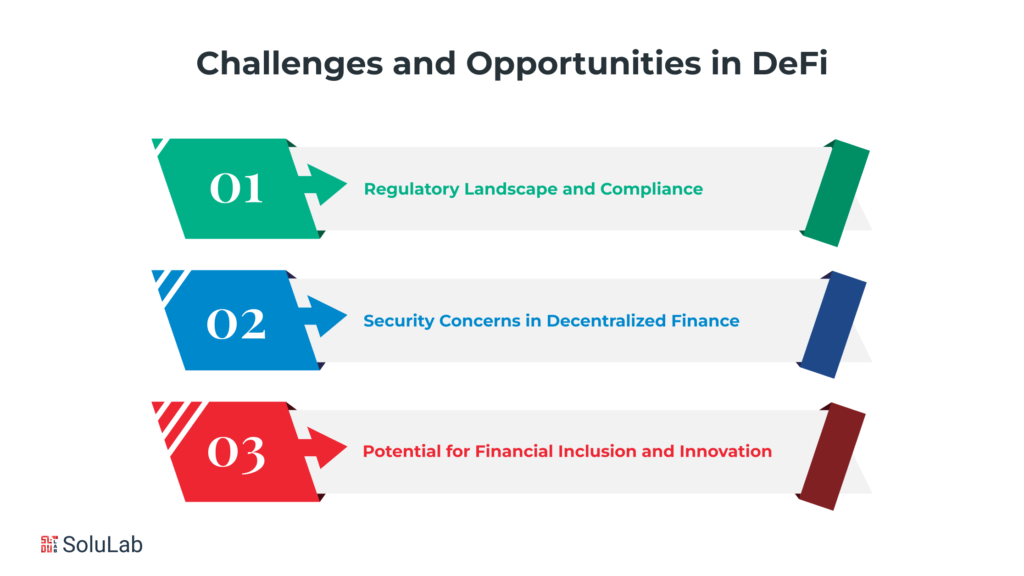
Nothing this new arrives clean. DeFi carries real problems alongside real promise, and the honest version of the story keeps both in frame: regulation, security, and the genuine chance to bring financial services to people who have none. Start with regulation, because it is the thorniest. A decentralized protocol does not fit the rulebook written for banks. There is often no company to license, no jurisdiction to file in, no officer to hold responsible. Protocols struggle to comply even when they want to, and regulators struggle to see what is happening in the first place.
Then there is security, and this one has teeth. DeFi runs on smart contracts, and smart contracts are software written by people who make mistakes. Protocols have been drained. Some of those losses were large and very public, and they cost the industry more than money: they cost trust, which is the harder thing to rebuild, and they are a large part of why mainstream adoption keeps stalling. Set that against what works. DeFi protocols can reach people that conventional institutions have written off as unprofitable, and it can do it at a fraction of the cost. Fix the security story and the rest becomes a question of when, not whether.
Regulatory Landscape and Compliance
Decentralization and regulation pull in opposite directions, and that tension is not going away. Governments are still working out what to do with Decentralized Finance Web3, and in the meantime compliance is something protocols have to reason about carefully. Finding the point where decentralization survives contact with the rules is hard. It is also the work that turns a frontier into an industry.
Security Concerns in Decentralized Finance
Security is the whole ballgame in DeFi, since smart contracts hold the funds and a bug in one is a bug with money behind it. Exploits have happened and the worry they created was earned. The flip side is that the DeFi exchanges moves fast, and it learns in public. Audit practices have tightened, security tooling has improved, and the standard for what counts as ready to deploy has risen considerably.
Potential for Financial Inclusion and Innovation
The opportunity that keeps drawing people in is reach. Open, permissionless financial services can get to the unbanked and the underbanked, who are not short of need but short of access. That is the same goal Web3 technologies claim more broadly, and here it has a concrete shape: a wallet, a connection, and services that do not ask who you are first.
Real World Applications of DeFi
This is not whiteboard material any more. DeFi already touches traditional finance, cross-border payments, and the tokenizing of physical assets, and the pattern repeats wherever it lands. New products that run cheaper and open wider than what they replace. Cross-border transfers that cost less and show you where the money is. Real estate or gold turned into tokens, which makes an asset that took months to sell into one you can trade in pieces. The list keeps growing, and it has already moved past finance into industries such as healthcare.
Still early, though. Early enough that how we think about finance and how we run a business could both look different in a few years. Before you put money anywhere, understand what you are putting it into. These protocols are complicated, the risks are not always where a newcomer expects them, and the ground keeps shifting. In practice, this is where most people get burned: they follow a yield without reading how the thing actually works. Keep reading. What was true six months ago often is not.
DeFi in Traditional Finance
Digital assets are not the boundary. The interesting work is at the seam between conventional finance and Decentralized Finance Web3. Tokenize a traditional asset, wire a smart contract to it, and it can participate in DeFi applications directly, which opens up ways to invest and structure products that neither side could offer alone.
Cross-Border Transactions and Remittances
Sending money across a border through the banking system means correspondent banks, cut-off times, and fees that fall hardest on the smallest transfers. Blockchain and DeFi route around all of it. Send digital assets anywhere, receive them anywhere, no banking infrastructure in the path. It costs less. It also lands in minutes rather than days, which matters enormously to anyone sending wages home.
Tokenization of Real Assets in DeFi
A building can be tokenized. So can a painting. Once an asset exists as tokens on a blockchain, ownership stops being all-or-nothing, and a buyer who could never afford the whole thing can hold a fraction of it. DeFi handles the trading and transfer from there. Markets that were illiquid by nature start to move, because the asset no longer has to find a single buyer with the full price in hand.
Risks and Considerations for DeFi Participants
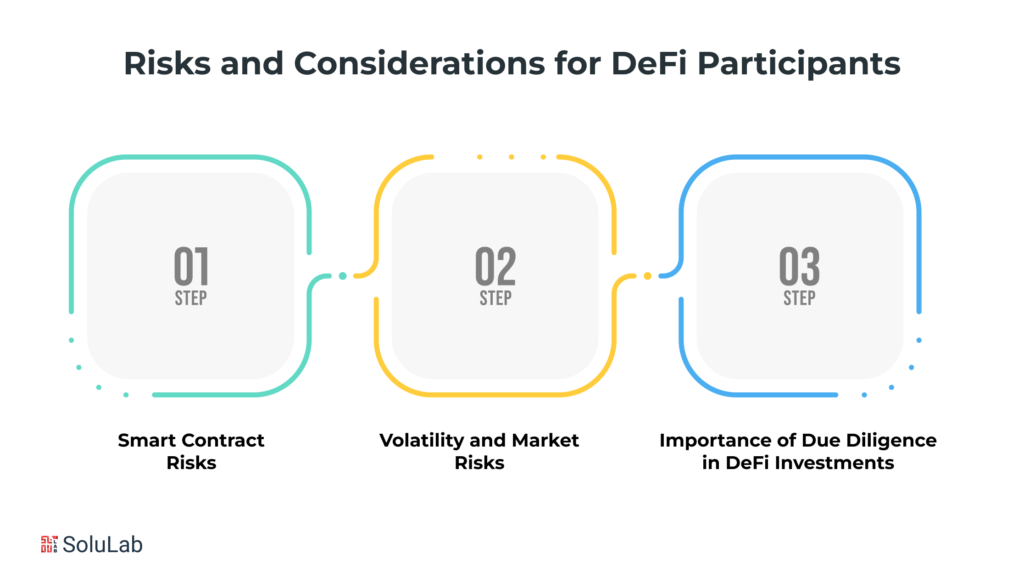
Every upside here has a matching risk, and pretending otherwise helps nobody. Contract bugs, violent price swings, protocols that change under you. The defense is unglamorous: do the homework, size your positions like you might lose them, and accept that the ground moves. Homework means reading the whitepaper properly, checking who the team is and what they have shipped before, and looking at the code or at a credible audit of it. Scams exist in this space. So does outright fraud. A few hours of reading is the cheapest protection you will ever buy.
Position sizing is the other half. DeFi markets swing hard, and a price that looked stable on Monday can be somewhere else entirely by Thursday. Know what a bad week does to your position before you take it. And keep up: new protocols launch constantly, old ones fork, incentives get rewritten. Staying current is not enthusiasm. It is the only way to make a decision on facts rather than on what was true last quarter.
Smart Contract Risks
Automation is not the same as safety. A smart contract does exactly what its code says, including the parts the author got wrong, and a flaw in that code is an open door to whatever it holds. Anyone active in the DeFi ecosystem should treat audits and code review as a prerequisite rather than a bonus feature. The DeFi in Web3 era leans hard on community review and on teams publishing enough for outsiders to check their work.
Volatility and Market Risks
Prices move, and in DeFi they move without a circuit breaker. That hits collateral first: a drop in the asset backing your loan can change your position fast, and lending and borrowing dynamics shift along with it. Spreading exposure helps. So do decentralized stablecoins, which give you somewhere to sit that is not tied to the swing. Neither trick removes the risk in DeFi in Web3, they just keep it survivable.
Importance of Due Diligence in DeFi Investments
You cannot participate well in something you do not understand. Read the protocol. Find out who governs it and how a proposal actually passes. Check what its security record looks like and who has reviewed the code. The DeFi in Web3 ethos pushes people to do this together in the open, which is the quiet strength of the model: a lot of eyes on the same contracts, and findings that get shared rather than hoarded, which is what makes the DeFi ecosystem sturdier over time.
Future Trends and Innovations in DeFi
So what is coming? Three threads look worth watching: deeper integration with DeFi in Web3 technologies, NFTs finding real financial uses rather than speculative ones, and decentralized identity (DID) arriving in finance. None of them is finished. All of them are being built right now.
Predicting this field precisely is a fool’s errand, and anyone claiming otherwise is selling something. The direction, though, is legible. Tighter integration with DeFi in Web3 technologies lowers the effort of getting to financial services at all. NFTs give digital assets a form that new products can be built around. And decentralized identity hands people control of their own financial data, which is a bigger deal than it sounds when you consider how much of that data currently sits with institutions you never chose.
Integration with Web3 Technologies
DeFi and Web3 keep converging, and the fit is natural enough that it barely needs arguing. Web3 puts decentralization and the user at the center, which is what Decentralized Finance Web3 was always trying to do with money. What comes out of the overlap is better interfaces, apps that actually work with each other, and projects with a shot at lasting beyond their first incentive program.
NFTs (Non-Fungible Tokens) in DeFi
NFTs represent things that are one of a kind, digital or physical, and DeFi has started treating them as financial objects rather than curiosities. They bring something new to Decentralized Finance Web3: a unique asset you can post as collateral, borrow against, or trade inside a protocol. For creators that means liquidity without selling outright. For investors it means a category of asset that had no financial rails at all until recently.
The Role of Decentralized Identity (DID) in Finance
Decentralized Identity (DID) changes who holds the file on you. Instead of your identity living in a dozen institutional databases, you carry it and decide what to reveal and to whom. That is better for privacy, better for security, and it lowers the barrier for people whose documents do not satisfy a conventional onboarding form. It is also squarely in line with what Web3 has argued for from the start.
Conclusion
Strip away the noise and DeFi is a fairly plain proposition: a second set of financial rails, made of blockchains, smart contracts, and tokens, that does a handful of things the old rails cannot. It settles at three in the morning. It shows you its books. It lets you keep custody of what you own. That is not a small list.
The working parts of the DeFi ecosystem are the ones covered above. A decentralized exchange gives you direct access to instruments with nobody in between taking a spread for the privilege. Automated market makers and liquidity pools keep markets tradeable and let anyone earn from supplying depth, in or out at will. NFTs add ownership of the specific and the singular, which widens what DeFi can price at all.
SoluLab builds in this space, and has done the work of designing and shipping DeFi models rather than writing about them from a distance. As aleading AI development company, SoluLab brings the engineering depth these systems demand, and the willingness to say when an idea does not hold up. Companies come to us with a DeFi concept that is half-formed or a specific problem that needs solving, and both are fine starting points. The larger point is that DeFi in the Web3 era is not a detour from how finance develops. Decentralized principles, blockchain, and applications built around the user add up to a different default: control sits with the person holding the assets. Plenty remains unbuilt and plenty remains unsolved, and that is exactly the kind of work SoluLab wants in the space of Decentralized Finance Web3
One last thought. Financial systems have absorbed a lot of technological shocks and kept going, and they will absorb this one too, changed by it rather than replaced. What is worth carrying forward is the practical stuff: check the code, understand the risk, and keep custody of your keys. Decentralized Finance in the DeFi in Web3 era stops being a concept the moment you actually use it, and for a growing number of people, that has already happened.
FAQs
1. What is decentralized finance?
Decentralized finance, usually shortened to DeFi, is the set of financial applications and services that run on blockchain technology. The banks, brokers, and clearing agents that normally sit in the middle get replaced or supplemented by smart contracts on blockchain platforms. The result is a system you can inspect, reach without permission, and use regardless of who you are or where you live.
2. How does DeFi align with Web3?
They want the same things: decentralization, control in the user’s hands, and applications that interoperate instead of locking people in. Web3 is the internet’s third act, built on decentralized protocols and apps that answer to their users. DeFi takes that idea and applies it to money, using blockchain and smart contracts to build financial services along the same lines.
3. What role does a decentralized exchange play in DeFi?
A decentralized exchange(DEX) is where a lot of DeFi activity actually happens: you trade digital assets directly, with no centralized intermediary holding your funds or approving the trade. Defi DEX platforms run the swap through smart contracts instead. Security improves, counterparty risk drops away, and nobody in the DeFi ecosystem has to be trusted for the trade to clear.
4. What are the key applications of DeFi?
Lending. Borrowing. decentralized exchange trading, liquidity provision, and a steadily lengthening list beyond those. What ties them together is the absence of a traditional intermediary: the services are global by default, and nobody has to approve your access first.
5. How are NFTs integrated into DeFi?
An NFT represents something unique, digital or physical, recorded on a blockchain. Inside DeFi that makes it usable as collateral, tradeable on a decentralized exchange, or a component in other financial instruments. It gives protocols a way to handle assets that are one of a kind rather than interchangeable, which most financial plumbing was never designed to do.
Bhavya is driving growth through data-backed demand generation for AI and Web3 solutions. With 9+ years in digital marketing, he has spearheaded initiatives that led to a 40% increase in qualified inbound leads. Bhavya shares insights on marketing ROI and scaling a digital presence via AI workflows. He is open to connecting with startups and enterprise teams to help them overcome their challenges.