Tech keeps rewriting the rules for whole industries, and banking is next in line. The force behind it this time is Web3. The name refers to the third era of the World Wide Web, one that is decentralized and built around the user rather than the platform. That changes how people interact online, and how they do business.
Three ideas sit underneath it: decentralization, transparency and giving users real control. Web1 and Web2 were centralized. A handful of players ran the show. Web3 swaps that model for blockchain technology and decentralized protocols, so the digital world becomes more open and lets more people in.
Banking has been through big tech shifts before. Internet banking was one. Artificial intelligence was another. Web3 looks like the next. Web3 in banking means moving away from traditional, centralized systems and toward a financial setup that is more democratic and where different systems can actually talk to each other.
Bring Web3 into financial operations and you get decentralized ledgers, smart contracts and tokenization. Combined, they make finance safer, more transparent and more efficient. What sets transactions on Web3 platforms apart? Fewer middlemen, stronger security, and far more control in the user’s hands.
What is the Importance of Reshaping Financial Systems?
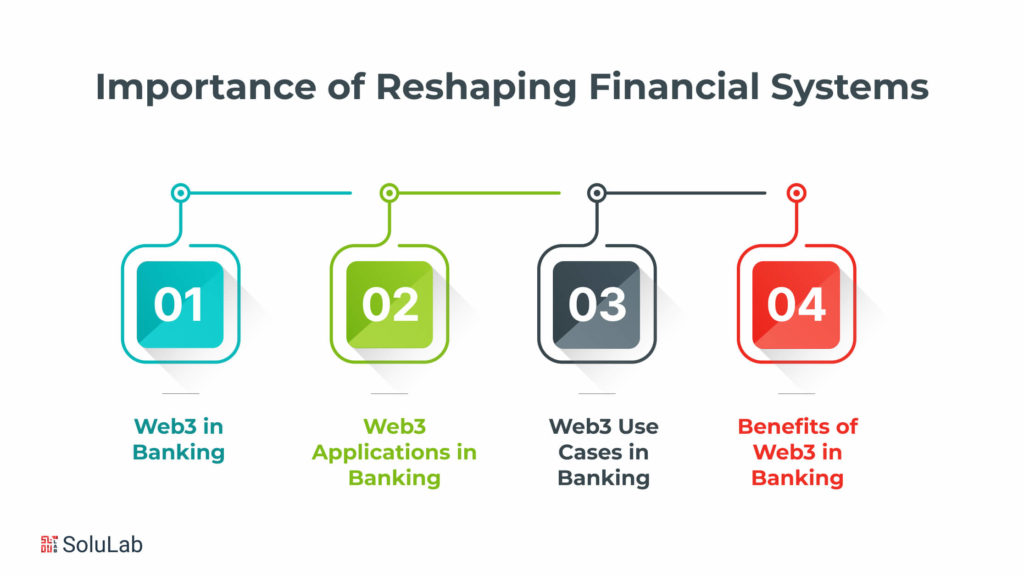
Web3 is changing financial systems at the root. It brings transparency, security and inclusion at levels banking hasn’t seen before. And inside banks, it’s already reworking the old processes.
Web3 in Banking
Put blockchain and decentralized technology into a banking system and you have Web3 banking. The upside is concrete. Stronger security. Less fraud. Customers holding far more control over their own money.
Web3 Applications in Banking
The range is wide: decentralized lending platforms, tokenized assets, cross-border payments settled on blockchain. Each one cuts steps out of a process, and each one brings more people into the financial system.
Web3 Use Cases in Banking
Think identity verification, transactions you can trace end to end, and decentralized finance (DeFi) trends. All of them rely on what blockchain does well to make banking faster and safer.
Benefits of Web3 in Banking
So what do banks and customers actually get? Better security, lower costs, more control for the user, and easier access. The system that results is tougher and built around the people using it, not the institution.
What are the Impacts of Traditional Banking?
Web3 has opened a new chapter for finance, and traditional banking is feeling it in several ways at once. Some of the changes are structural. Others are about day-to-day operations. Here are the ones that matter most.
Disintermediation and Decentralization
Web3 in banking breaks with the old model of intermediaries and central control. Blockchain, the backbone of Web3, makes it possible to cut out the middle layers entirely by building decentralized financial systems.
Users gain the most. They can transact peer to peer and lean less on banking intermediaries. The knock-on effect is a more inclusive financial system, one that offers services well beyond what conventional institutions reach.
Smart Contracts and Automation
Smart contracts are where Web3 gets practical. They’re self-executing agreements with the rules written into the code, and they can automate jobs like loan approvals, fund transfers and compliance checks.
Fewer manual steps means fewer errors and less room for fraud. It also makes banks quicker. Automation of this kind lets a traditional bank respond to customers and markets with an agility it rarely had before.
Enhanced Security and Transparency
Security gets a serious upgrade through advanced cryptography. Blockchain, a core piece of Web3, keeps data intact and unchangeable once it’s written, which makes it very hard for attackers to tamper with records.
Transparency builds trust, too. Because blockchain records are open, everyone involved can see the same picture. Clients can follow their transactions in real time. That’s a level of visibility traditional banking never offered, and together with the stronger security, it makes the whole system harder to knock over.
Web3 Applications in Banking
When banks adopt Web3 applications, new services follow. Built on decentralized technology, they include decentralized finance (DeFi), asset tokenization and decentralized identity verification.
But Web3 doesn’t stay inside the bank’s walls. It reaches people the old structures missed, widening financial inclusion and access.
Web3 Use Cases in Banking
In practice, Web3 shows up in banking through cross-border payments, decentralized lending platforms and more.
Blockchain makes cross-border transfers faster and more secure. Decentralized lending gives people another place to find funding, outside the usual banking channels. Two very different problems, one underlying technology. That range is exactly why Web3 could reshape how banks operate.
What Role do Smart Contracts Play in the Seamless Execution of Financial Transactions within Web3 Applications in Banking?
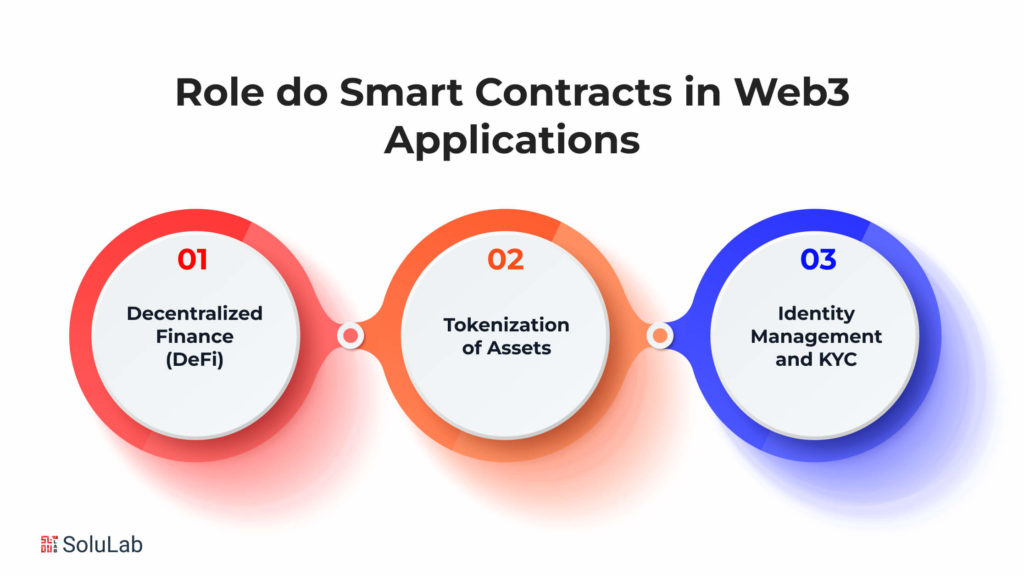
Banking keeps shifting, and Web3 applications are pushing it toward decentralization, transparency and efficiency. Three developments drive most of this: decentralized finance (DeFi), tokenization of assets, and modern identity management systems built on Know Your Customer (KYC) protocols. Let’s take each in turn and look at what it actually does for banks.
A. Decentralized Finance (DeFi)
Decentralization Redefined
Web3 banking apps use blockchain to build financial networks with no central operator. Intermediaries drop out. Transactions happen directly between the two parties, and because the record is shared, trust and transparency come built in.
Smart Contracts for Seamless Transactions
Smart contracts are central to Web3. They let financial agreements run automatically and securely, with no intermediary required. Transactions go through without hiccups. For banks, that means less fraud risk and lower operating costs.
Liquidity Pools and Yield Farming
DeFi platforms on Web3 let users pool their funds and earn interest on them. Yield farming, another DeFi development, rewards people for locking assets into protocols. More locked assets means more liquidity, and more liquidity means a broader menu of financial services.
B. Tokenization of Assets
Fractional Ownership through Tokens
Tokenization lets people own a fraction of assets that were always hard to buy and sell, such as real estate or art. You no longer need a fortune to invest in something expensive. A smaller amount of capital gets you a piece.
Efficient Asset Transfer
Once an asset lives on a blockchain as a digital token, moving it gets easy. Buying, selling and transferring ownership all speed up. Settlement takes less time, and it costs less.
Enhanced Liquidity and Market Accessibility
Tokenized assets can trade around the clock, 24/7, on decentralized exchanges. That boosts liquidity. It also widens the market, which helps investors and banks alike: there are simply more assets available to manage and trade.
C. Identity Management and KYC
Decentralized Identity Solutions
Privacy moves to the front with decentralized identity. People keep control of their own personal information instead of handing it to a central database. The payoff is a lower risk of identity theft and unauthorized access.
Streamlined KYC Processes
KYC is one of the most painful parts of opening an account. Web3 improves it by letting users share identity credentials securely. Onboarding gets faster, regulatory requirements are still met, and the bank ends up safer and more transparent for it.
Cross-Border Identity Verification
Verifying identity across borders is another win. Banks in different countries can work together smoothly while user data stays protected. Less friction on international transactions, and global banking runs more efficiently as a result.
Read Also: Build MiCA-Compliant Neo Banks in Europe
What Regulatory Challenges do Traditional Banks Face as they Integrate Web3 Technologies into their Financial Operations?
It isn’t all upside. Bringing Web3 into finance raises real problems, and banks moving into this space hit three in particular: regulation, security and integration. Here’s what each looks like.
Regulatory Hurdles
Regulation is messy. Existing rules were written for centralized systems, and Web3 isn’t one. Traditional banks adopting Web3 applications have to work through that, while regulators themselves are still figuring out how to adapt.
The open questions: who has jurisdiction, what compliance looks like, and how to build a framework that can handle something as fluid and distributed as Web3 banking.
Security Risks and Mitigations
Security cuts both ways. Blockchain is decentralized and open source, and that openness creates new risks for Web3 banking.
Smart contracts are the weak spot. If nobody audits them properly, they can be exploited. Any traditional bank stepping into Web3 needs strong cybersecurity, thorough code audits and a real plan for handling threats. That’s how you keep financial transactions intact and confidential. In practice, this is where many first projects slip: the audit gets squeezed to hit a launch date.
Integration Challenges for Traditional Banks
Then there’s the plumbing. Getting Web3 to work with a traditional bank’s existing infrastructure is hard. Legacy systems weren’t built for something decentralized and trustless like blockchain, and they often resist a clean fit.
Staff need training so they understand how Web3 applications work and where the tricky parts are. And integration should happen in phases. That way existing services keep running while the bank starts collecting the benefits of Web3 in banking.
Even so, Web3 applications are changing banking by making transactions trustless and transparent. DeFi platforms, blockchain-based identity checks and much more: the list of Web3 use cases in finance is long and still growing.
How do Web3 Technologies Contribute to the Unlocking of Global Financial Inclusion?
New technology has opened far more room for financial inclusion than existed even a few years ago. Web3 is one of the biggest reasons. It changes how people reach financial services and how those services get delivered. Here’s where the opportunities lie.
Access to Financial Services Globally
Geography used to decide who got banked. Web3 is breaking that down, putting financial services within reach worldwide in a way banking never managed. Traditional banks have long struggled to serve remote and underserved communities, and billions of people remain unbanked as a result.
Web3 works differently. Because it’s decentralized and runs on blockchain, it supports financial networks with no borders. With cryptocurrencies and decentralized finance (DeFi) platforms, someone almost anywhere can use a wide range of financial services. No traditional bank account needed.
Trust matters here too. Web3 applications are transparent and secure by design, and that encourages people who were shut out of formal finance to take part. The result? A fairer playing field, whatever someone’s location or economic background.
Empowering the Unbanked through Web3 Technologies
A large share of the world’s population is still unbanked or underbanked, blocked from the traditional financial system. Web3 is tackling this head on, using blockchain to build decentralized financial networks.
With Web3 applications in banking, people who never had a bank can now borrow, lend and even earn interest through decentralized platforms.
That’s what “Web3 banking” really points to: financial services built around the user, where people make their own calls about their own money. Giving the unbanked that power shows what Web3 can do. It’s also one of the strongest levers available for narrowing global economic inequality.
Case Studies and Success Stories
There are plenty of examples of Web3 widening financial inclusion [SOURCE NEEDED]. In regions with little traditional banking infrastructure, decentralized finance platforms built on Web3 principles have let people get loans, invest in assets and take part in economic activity without the usual hurdles.
The use cases vary a lot, from peer-to-peer lending platforms to decentralized identity tools that make financial services easier to reach.
Taken together, these stories show how adaptable and durable Web3 is, and that it produces real, positive results for individuals and whole communities.
What are the Steps essential for Web3 in Banking?
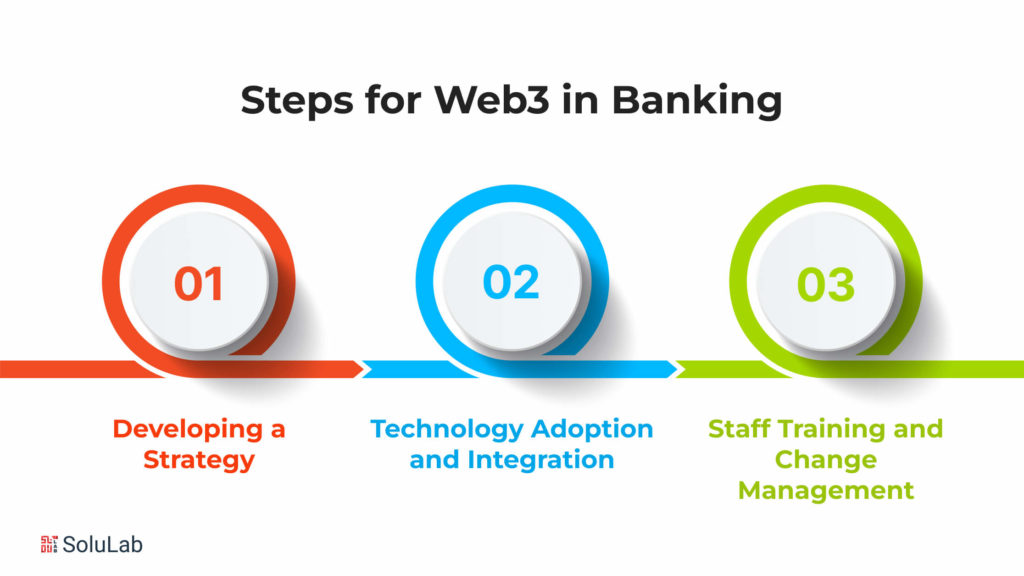
Banks that want to stay ahead can’t treat Web3 as optional anymore. It’s decentralized and trustless, and it’s already changing how banking is structured. Adopting it well takes a plan. You need to pick the right technology, integrate it carefully and train your people properly. Here’s how to approach it, step by step:
A. Developing a Strategy
Start with strategy. Before touching any code, learn how Web3 in finance really works and figure out where it fits in banking. Look hard at your current infrastructure. Where would a Web3 use case make things faster, safer or more transparent? Those are your targets.
Key Considerations
- Take a detailed look at Web3 use cases in banking.
- Set clear, specific goals for what Web3 integration should achieve.
- Put a dedicated team in charge of carrying out the strategy.
- Make sure every step lines up with regulatory requirements and compliance standards.
B. Technology Adoption and Integration
With a solid strategy in hand, move on to choosing and integrating the technology itself. Find the platforms and tools that match what you’ve planned. For banks, Web3 applications may include blockchain-based solutions, smart contracts, and decentralized finance (DeFi) protocols.
Key Steps
- Compare blockchain platforms and pick ones that suit banking use.
- Build in smart contracts so transactions run automatically and securely.
- Look at decentralized finance options that could improve your financial services.
- Partner with FinTech firms that specialize in Web3.
C. Staff Training and Change Management
Technology is only half the job. The other half is people. Training and change management decide whether the transition goes smoothly or stalls. Your banking staff need to understand what Web3 is, how it changes their existing processes, and how to actually use the new tools well.
Training Essentials
- Run workshops and training sessions that cover Web3 basics.
- Build a culture where people adapt quickly and keep learning.
- Give employees the resources and support to build skills in the areas that matter.
- Roll things out in phases so the change is gradual and disruption stays low.
Follow these steps and a bank puts itself near the front of the Web3 shift, with fresh room for innovation and happier customers. But don’t mistake it for a simple tech upgrade. Adopting Web3 in banking is a strategic change in how a financial institution works in the digital age.
Conclusion
SoluLab’s complete reference to Web3 in banking makes one thing plain: decentralized technology can change the financial industry from the ground up. As a leading Web3 development firm, SoluLab sees how much Web3 applications matter for banks, and it lays out a roadmap for institutions that want the benefits of this shift.
The guide covers the many ways Web3 applies to finance and shows how it lifts security, transparency and efficiency in financial processes. If your firm wants to stay ahead in the digital market, hiring Web3 developers is the recommended route, because Web3 banking is complex and real expertise makes the difference.
What sets SoluLab apart is how it handles the hard parts of Web3 in banking. That makes it a partner financial organizations can trust as decentralized finance grows. SoluLab uses web3 finance to make transitions smooth, and to open new paths for growth, innovation and long-term development in banking.
FAQs
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.