Banks have been sitting on mountains of data for decades. Machine learning is what finally made that pile useful. This piece looks at what actually changes once a bank puts ML to work: how customers get treated, how risk gets priced, how fraud gets caught before the money leaves the account. Some of it is genuinely new. A lot of it is old banking logic running faster, at a scale no room full of analysts could ever match. We will go through the operations side, the customer side, and the use cases that keep showing up in real deployments. You will not find a promise here that ML fixes everything. You will find where it works, where it drags, and what a bank needs in place before any of it pays for itself.
Understanding Machine Learning in Banking
Strip out the marketing and Machine Learning in banking is a plain idea. Feed algorithms enough history and they start spotting patterns a human analyst would need years to find. The model gets corrected, retrains, comes back slightly sharper. Run that loop a few million times and the bank ends up with predictions it can act on instead of hunches it has to defend.
Defining Machine Learning:
Machine Learning in banking sector (ML) sits inside the wider field of Artificial Intelligence (AI). The short version: a system gets better at a job by working through examples, not because somebody wrote a rule for every possible case. Banks care because the examples already exist. Transactions, applications, call logs, device signals, decades of them. ML reads that record and turns it into something predictive.
Where does that actually show up? Five places, mostly:
1. Fraud Detection: The model learns what a given customer’s normal looks like, then flags whatever does not fit. Wrong city, wrong hour, wrong amount, wrong sequence. That flag goes into a review queue built from historical transaction data, and the suspicious ones get looked at before the damage compounds.
2. Credit Scoring: Instead of three or four ratios, a model weighs dozens of signals about an applicant at once. Lending decisions get faster. Defaults get easier to see coming, and the loan book stays cleaner as a result.
3. Personalized Recommendations: Customer data tells a bank what someone needs rather than what the campaign calendar says to push this quarter. Better offers, better timing, and revenue that comes from relevance instead of volume.
4. Risk Management: Market risk, credit risk, operational risk. Models read enormous volumes of data to size up exposure, estimate what a bad scenario costs, and shape the response while there is still time to shape it.
5. Customer Service: Chatbots and virtual assistants answer at three in the morning with no queue. They close out the routine questions, pass the messy ones upward, and keep human agents free for the calls that need judgment.
And the list is not finished. New applications keep arriving as the tooling matures.
Significance in the Banking Industry:
So why does any of this reach the balance sheet? Five reasons come up again and again:
1. Enhanced Customer Experiences: Models read behavior and adjust the product while the customer is still in the app. People notice when a bank stops treating them as a segment. Loyalty tends to follow.
2. Optimized Risk Management: Patterns and outliers get caught earlier, which keeps losses smaller and keeps the institution’s books honest.
3. Leaner Operations: Automation lifts the repetitive work off people’s desks. Less manual handling, fewer handoffs, shorter turnaround.
4. Fraud Detection and Prevention: Suspicious transactions get caught while they are happening, not during next month’s reconciliation. That saves money. More to the point, it saves trust.
5. Personalized Financial Advice: Advisory tools built on ML give a customer insight tied to their own numbers, which is the only kind of advice that means anything.
Banks that get this right stop behaving like processing plants and start behaving like something a customer would actively choose.
Evolution of ML in Finance:
ML did not arrive in finance all at once. It crept in through the back office, one workflow at a time. Risk assessment was an early winner: algorithms comb through historical data for patterns and anomalies, which makes the resulting numbers both more accurate and easier to defend in a committee. Fraud detection came next. Models read transaction volume no review team could physically touch, spot the behavior that does not belong, and raise the alert while the payment is still in flight. Losses shrink. Customers keep their money.
Customer service followed. Chatbots handle natural language well enough now to resolve the common stuff around the clock. Personalization is the other headline application, with products shaped around real spending habits and stated goals rather than a demographic guess. Then there is the unglamorous side: automating tasks, tightening processes, putting people and compute where they earn the most. That is where a surprising share of the actual savings live. The technology keeps moving, and finance keeps finding new places to point it.
Machine Learning Transforming Banking Operations
Something big shifted in banking, and it never announced itself. Machine learning quietly became infrastructure. Institutions run it for insight, for customer experience, for the plumbing of daily operations. Banking has always been quicker than outsiders assume at adopting technology that pays for itself, and this is another instance of that instinct working.
1. Enhancing Customer Experience:
Three things tend to happen at once when ML lands inside a bank. The customer experience improves, operations get cheaper, and risk gets smaller.
- Chatbots development answer straight away, read what is actually being asked, and close out simple requests without anyone stepping in.
- Recommendations built on a customer’s own financial data help them decide rather than guess, which is what moves people toward their goals.
- Fraud models read transaction data for patterns that do not belong, and keep money sitting where it should be sitting.
- The list runs further than that: credit scoring, customer segmentation, risk management.
Put simply, the upside for banking is large and mostly proven.
2. Fraud Detection and Security:
Fraud is where ML earns its keep fastest. Models learn what unusual looks like, whether that means a transaction far outside a customer’s normal range, a burst of tiny test charges, or network traffic that does not fit the shape of the rest. Banks running this properly cut their exposure sharply. And the better systems surface risk before the loss lands, which buys the bank time to act instead of time to apologize.
What that looks like in practice:
- Transaction monitoring
- Network traffic analysis
- Device fingerprinting
- Behavioral analytics
Fraudsters iterate. So do the models. That, in one line, is the whole argument for using ML to guard customer money.
Credit Scoring and Risk Assessment:
Machine Learning in Banking industry (ML) models look at far more than a credit file. Nontraditional sources come into the picture, and what emerges is a fuller read on where an applicant genuinely stands. The appeal is easy to see: huge data volumes processed quickly, complicated patterns surfaced, lending calls made without the drift that creeps into a human underwriter’s judgment late on a Friday. Alternative data also widens the pool, so people who were invisible to the old scorecards become bankable. But the problems are real and they are not small. Is the model fair? Can anyone explain why it said no? Is the data safe where it sits? Those questions need answers before deployment, not after the first complaint. Validation and testing have to be serious work rather than a checkbox, and steady spending on data security is what keeps customer trust intact. Get that part right and ML makes credit faster, sharper, and open to more people than it used to be.
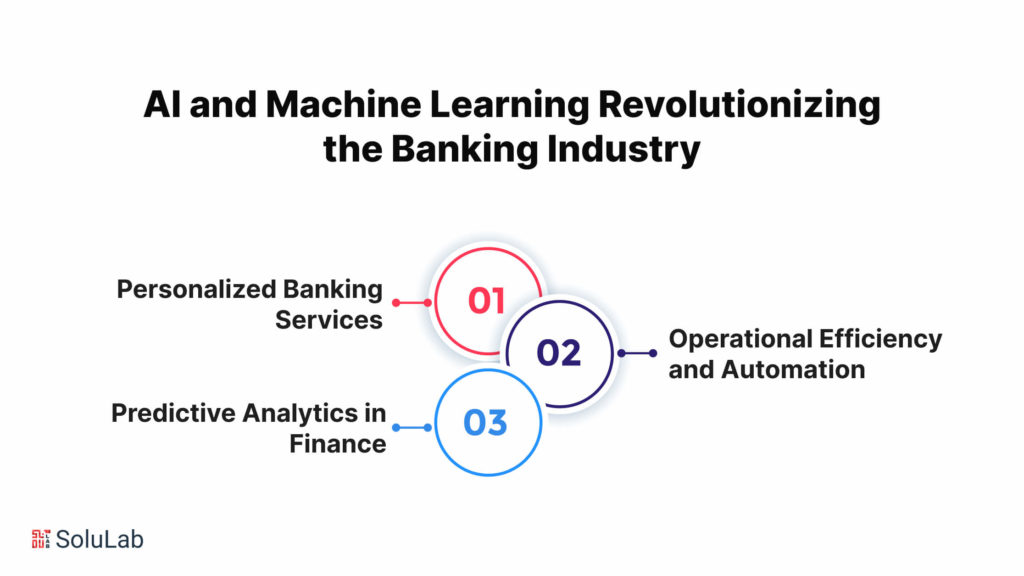
AI and Machine Learning Revolutionizing the Banking Industry
Artificial Intelligence (AI) and Machine Learning in Banking industry are not competing ideas. AI supplies the wider intelligence. ML supplies the correction loop that keeps the whole thing current. One sets the intent, the other keeps score. Together they sharpen decisions, improve what customers actually feel, and leave the bank able to change when the market does.
Personalized Banking Services:
Artificial Intelligence (AI) and Machine Learning in Banking industry (ML) are what make a bank feel like it knows you.
Key Transformations:
- Tailored Product Recommendations: AI reads customer data and suggests what fits. A higher yield savings account for one person, an investment option for another, rather than the same blanket offer sent to everybody.
- Enhanced Customer Experience: AI-powered chatbots and virtual assistants are awake at midnight, answering questions and clearing issues on the spot.
- Fraud Detection and Prevention: Transaction patterns get read continuously, and anything that looks wrong gets stopped before the customer is out of pocket.
- Personalized Financial Advice: Advisory tools work from one customer’s actual situation, so the recommendations land as specific rather than generic.
- Automating the Repetitive Work: Data entry, customer verification, the same forms over and over. AI and ML absorb that, and employees get their attention back for the problems that deserve it.
JPMorgan Chase, Bank of America and Wells Fargo are all well into this already. The tooling keeps improving, and banking services keep getting more personal, quicker, and harder to defraud.
Operational Efficiency and Automation:
Automation is quietly rewriting how a bank runs day to day, and advanced machine learning in banking sector algorithms are doing the heavy lifting. Take document verification. For years that meant a person reading page after page, catching what they could before fatigue set in. Machine learning in banking sector algorithms work through the same stack in a fraction of the time and catch discrepancies a tired reviewer would slide past. Routine transactions and data entry go the same way. What stays with staff is the work that genuinely needs a human: judgment calls, exceptions, the customer whose situation does not fit any box on the form. The payoff shows up as speed, fewer errors, better service, lower cost, and cleaner compliance records. Banks are still finding new places to aim it.
Predictive Analytics in Finance:
Predictive analytics is a bank asking what happens next and getting a usable answer back. Five places it pays:
- Forecasting Market Fluctuations: Historical data, current conditions, outside factors. Combine them and both the opportunities and the trouble show up earlier than they otherwise would.
- Anticipating Customer Needs: Read behavior and preference, then build the product and the campaign around what people are about to want. Satisfaction climbs. So does revenue.
- Detecting Fraud and Financial Crime: Suspicious transactions surface, fraud gets uncovered, customer funds stay put, and the wider system stays sound.
- Optimizing Operational Efficiency: Service data, productivity data, resource data. Analyze it and the waste becomes obvious. Cost follows the waste out the door.
- Enhancing Risk Management: Risks and weak points become visible ahead of time, which is exactly what a credit team needs before it signs off on a loan.
The net effect is a bank that plans instead of reacts. Sharper strategy, less risk carried on the books, customers who stay, and growth that is not an accident.
Application of Machine Learning in Banking and Finance
Now to specifics. This section covers what ML does once it is actually deployed across banking and finance, in the places where it changes a process rather than just reporting on one. Some applications reshape how decisions get made. Others quietly remove work nobody enjoyed. A few manage both at the same time.
Algorithmic Trading:
Machine learning algorithms changed algorithmic trading by making enormous volumes of history readable in the moment a trade has to happen. That matters most when markets turn violent. The gains are concrete: deeper data analysis, faster execution, fewer fat finger mistakes, and strategies a desk can tune rather than buy off the shelf. There is more coming. Better signal generation, tighter risk controls, smarter portfolio construction as the algorithms themselves get more capable. Trading will keep moving in this direction, and the desks that resist it will feel the gap first.
Dynamic Fraud Prevention:
Rule based fraud systems carry one fatal flaw. Somebody has to write the rule, and fraud tactics change faster than a committee approves updates. ML flips that around. Train on historical data, let the model learn the shape of fraud, and it picks up anomalies inside live transactions instead of inside last month’s report. The attempt gets stopped mid flight rather than investigated after settlement. Retrain the model and it keeps pace. That is the difference in a sentence. What ML brings to fraud prevention:
- Real-time detection: fraud gets flagged as the transaction hits, not in an overnight batch job.
- Adaptability: continuous retraining keeps the model current with whatever tactic is circulating this month.
- Reduced false positives: tuning cuts the number of legitimate customers who get declined at the till for no reason.
- Scalability: volume becomes a hardware question, which suits large operations well.
Customer Sentiment Analysis:
Sentiment analysis, run on Machine Learning in Banking industry algorithms, tells a bank what its customers actually think. Not what a survey with a four percent response rate implies. The raw material is already everywhere: support conversations, social posts, complaint forms, feedback fields nobody has read in years. Models pull the recurring signals out of that mess until the pattern becomes legible. Then comes the useful part, which is doing something about it. Fix the app flow people keep cursing. Build the loyalty program the data says would land. There is a competitive angle here too, since the same method benchmarks a bank against its rivals and shows plainly where it trails. Done properly, sentiment work is how an institution stops guessing about its own reputation.
Machine Learning Use Cases in the Banking Sector
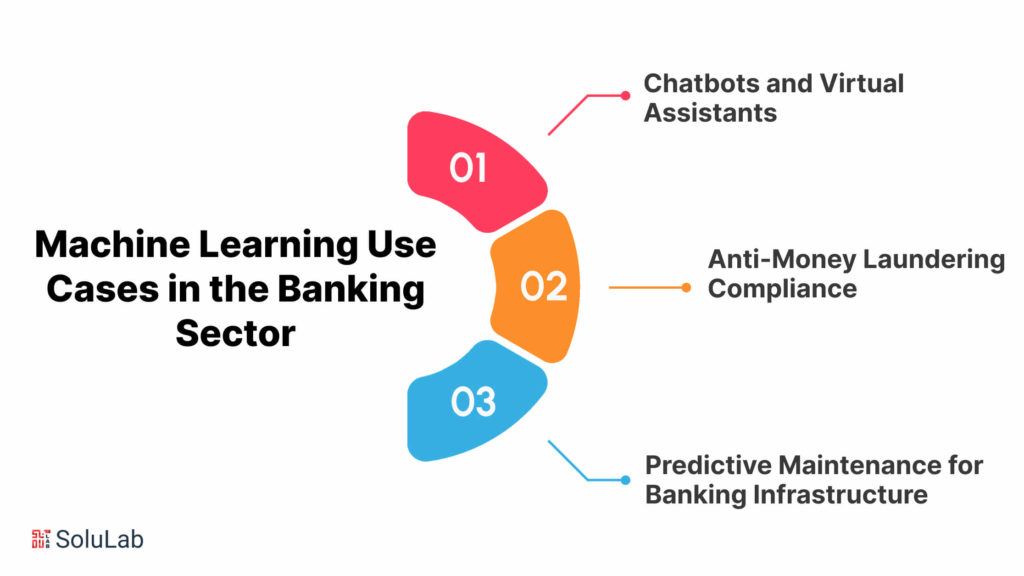
Below are the use cases that come up most often in real banking deployments: product customization, customer experience, and the internal machinery that keeps the place running.
Chatbots and Virtual Assistants:
Chatbots running on Machine Learning in Banking industry algorithms now hold the front line of customer service. Instant answers. Routine jobs such as payments and balance checks finished inside the chat window. Replies shaped by what the bank already knows about that customer, so the conversation does not restart from zero every single time. Satisfaction goes up, cost per interaction comes down, and growth follows from both. Enterprise Chatbots are how most institutions get there.
Anti-Money Laundering (AML) Compliance:
AML is slow, manual, and error prone almost everywhere it is still done by hand. Machine learning is changing that. Train models on years of transaction history and they learn what laundering patterns look like, then surface them with an accuracy no review team can match at that volume. Time saved, cost down, risk finally understood. For a compliance officer the appeal is simple: fewer missed cases, fewer wasted investigations, and a regulator who leaves satisfied. Customers benefit too, mostly by not getting caught in friction they did nothing to earn.
Predictive Maintenance for Banking Infrastructure:
Nobody thinks about the ATM network or the core system until it goes down. Machine learning is what keeps that call from coming. Models read historical performance data and predict where hardware and systems are heading toward failure, which turns maintenance from a panic into a schedule. Alerts fire early. Diagnostics run themselves. Security posture improves alongside, since the same anomaly detection works on both problems. Less downtime, better use of scarce engineers, and customers who notice nothing at all because nothing broke. That last one is the entire point.
Conclusion
Machine learning has already changed how banks operate, how customers get treated, and how security gets handled. None of that is speculative any more. SoluLab works as a machine learning development company on exactly this class of problem. Its work in AI development services helps banks put AI and machine learning in Banking Industry into live operations rather than pilot decks that never ship. The engagements cover the whole range: customer experience, operational efficiency, security hardening. If your institution is still arguing about where to start, that argument is usually the thing worth outsourcing first.
FAQs
Bhavya is driving growth through data-backed demand generation for AI and Web3 solutions. With 9+ years in digital marketing, he has spearheaded initiatives that led to a 40% increase in qualified inbound leads. Bhavya shares insights on marketing ROI and scaling a digital presence via AI workflows. He is open to connecting with startups and enterprise teams to help them overcome their challenges.