Few inventions have changed how we handle digital transactions and data as sharply as blockchain. So let’s start at the beginning: what the technology is, how it actually runs under the hood, and where it is being put to work in today’s digital economy.
Strip away the hype and a blockchain is a ledger. A digital one, spread across many machines instead of sitting in one company’s server room. It is made of blocks linked in a chain, and each block holds a record of several transactions. Three traits define it: transparency, security, and immutability. A centralized database has a single owner who decides what goes in. A blockchain runs on a network of computers, called nodes, and every participant can see and check the transactions. Once data lands in a block and that block joins the chain, changing it becomes extremely hard, which is exactly why people trust what’s written there.
That mix of transparency, security, and efficiency is why blockchain has spread into so many fields. From blockchain platforms to development services and consulting, the market around it keeps growing, and there is real room in it for businesses and developers. Whole companies now exist to handle one slice of this technology or another. Some build the blockchain platforms themselves. Others provide blockchain development services on top of them.
How Does Blockchain Work?
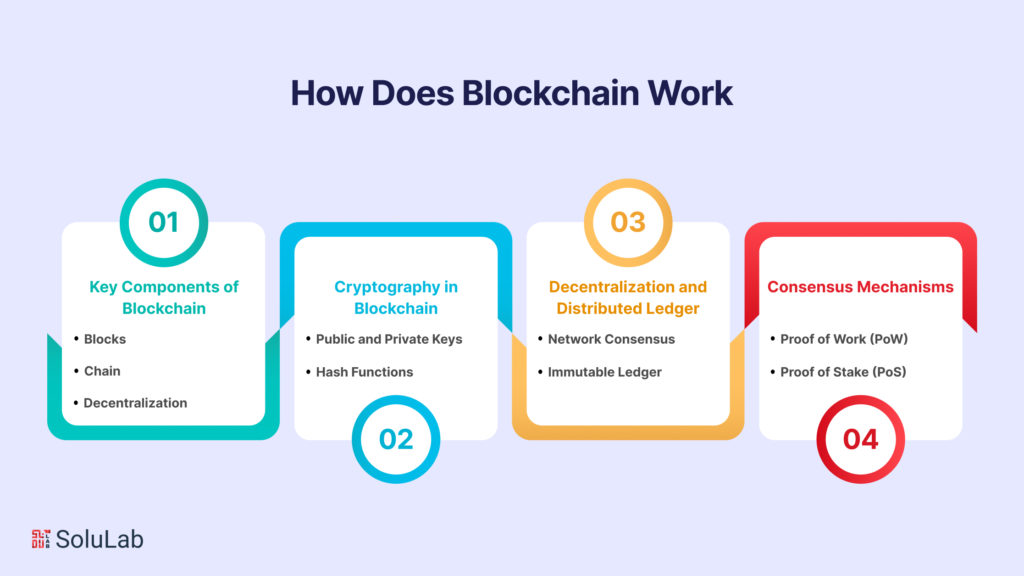
Finance, supply chains, and a long list of other industries are watching blockchain closely. But you can’t judge what it might change until you know how it works. This section walks through the main building blocks, what cryptography contributes, why decentralization matters, and how consensus mechanisms keep everyone honest.
Key Components of Blockchain
Think of a blockchain as a distributed and immutable ledger in blockchain that logs transactions across a network of computers. Three pieces make it work:
- Blocks
A block is a container for transaction data. It bundles a group of transactions together and carries its own unique fingerprint, called a “hash.”
- Chain
Blocks line up in the order they were created. Each new block stores the hash of the one before it, and that link is what makes the chain secure: tamper with one block and the connection to the next one breaks.
- Decentralization
No single machine is in charge. The blockchain runs across a decentralized network of nodes, and every node keeps a full copy of the ledger. Lose one node and nothing is lost. That redundancy is a big part of the security story.
Cryptography in Blockchain
Cryptography does the heavy lifting when it comes to securing data and protecting privacy on a blockchain. Two techniques matter most:
- Public and Private Keys
Every user holds two cryptographic keys. The public key identifies you. The private key is what you sign with. You sign a transaction with your private key, and anyone can check that signature using your public key.
- Hash Functions
A cryptographic hash function turns transactions and blocks into alphanumeric strings of a fixed length. Change a single character in the input and the output looks completely different. That sensitivity is the point, because it makes tampering obvious.
Decentralization and Distributed Ledger
Decentralization sits at the heart of blockchain. Where a traditional system keeps one master copy under one authority, a blockchain spreads its ledger across the network:
- Network Consensus
Nobody approves a transaction alone. A consensus mechanism validates it, and usually most of the nodes have to agree that it’s legitimate.
- Immutable Ledger
After a block joins the chain, rewriting the transactions inside it is close to impossible. The cryptography would have to be broken, and the consensus mechanism would have to be overpowered, both at once.
Consensus Mechanisms (e.g., Proof of Work, Proof of Stake)
Without consensus mechanisms, a blockchain simply doesn’t function. They are how everyone on the network agrees which transactions are valid. The two you’ll hear about most:
- Proof of Work (PoW)
Under PoW, miners compete to solve hard mathematical puzzles, and the winner gets to add the next block. It eats a lot of computing power and energy. The payoff is very strong security.
- Proof of Stake (PoS)
PoS swaps miners for validators. Who gets to create a new block depends on how many coins a validator holds and is willing to “stake” as collateral. Less brute-force computing, so PoS uses far less energy than PoW.
What are the Fundamental Components and Characteristics of a Blockchain Network?
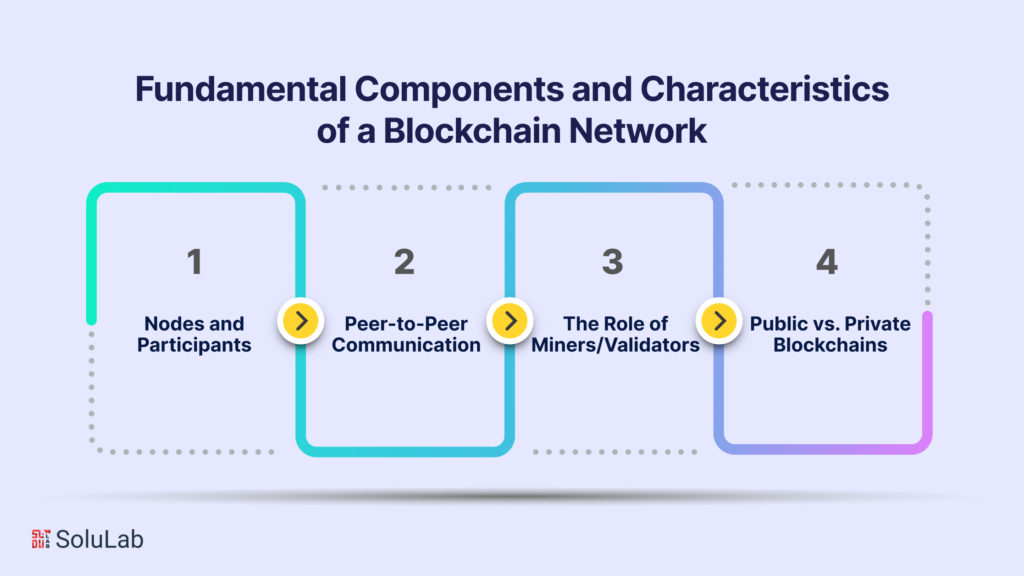
Blockchain gives us a secure, transparent way to record transactions and data, and it has become one of the most talked-about ideas in digital technology. To really get it, though, you have to look at the network itself. Here we cover who and what sits on that network, how peers talk to each other, what miners and validators do, and how public blockchains differ from private ones.
Nodes and Participants
- Every blockchain network is built from nodes and participants. A node is simply a computer or device connected to the network. Collectively, nodes are what keep the blockchain decentralized.
- Participants are the people, organizations, or other entities that use the blockchain, whether they create transactions, validate them, or store them. Put together, they make up the community that keeps the network alive.
Read Our Blog Post: Best Companies to Hire Blockchain Developers in 2024
Peer-to-Peer Communication
- Nodes on a blockchain talk to each other directly over a peer-to-peer (P2P) network. No middleman. That setup tightens security and removes any single point of failure, since there’s no central server to knock over.
- When someone starts a transaction or updates the chain, the news is broadcast to every node on the network. That’s how all the nodes end up holding the same, current copy of the blockchain.
The Role of Miners/Validators
- On public blockchains, miners or validators are the ones keeping the ledger honest. Miners check transactions by solving hard mathematical puzzles as part of the consensus process (Proof of Work or Proof of Stake, for example).
- A verified transaction goes into a new block, and that block is then attached to the existing chain. Why would anyone spend the computing power? Rewards, usually paid in cryptocurrency.
Public vs. Private Blockchains
Broadly, blockchain networks come in two flavours, public and private, and they behave quite differently:
- Public Blockchains
Anyone can join. Public blockchains are open and permissionless, decentralized and transparent, and they are the backbone of cryptocurrencies such as Bitcoin and Ethereum. A global network of miners keeps them running.
Read Also: What Are The Benefits of Hiring a Blockchain Developer?
- Private Blockchains
Private blockchains are the opposite. Access is limited to specific participants or organizations, and the network is permissioned, so only approved entities can validate transactions or even read the ledger. You’ll mostly find them in enterprise applications, supply chain management, and consortiums.
Once you understand the network’s structure, who takes part, and how they communicate, the rest of blockchain starts to make sense. This is the groundwork for secure digital transactions, traceable supply chains, and decentralized applications (DApps). And the technology isn’t standing still. Each step forward opens fresh room for new ideas and new trends.
Plenty of companies and developers are now building on blockchain and selling services and solutions around it. Getting adoption and integration right is where most businesses struggle, and Blockchain consulting services can help work through that complexity so a business stays ahead as its operations go digital.
What are the Applications of Blockchain Technology?
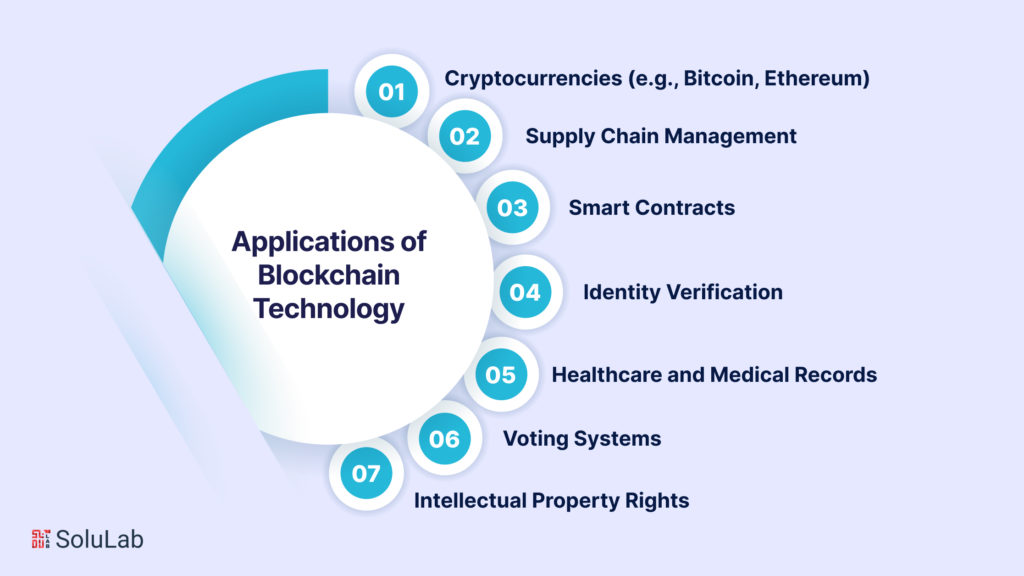
Most people first heard of blockchain as the engine behind Bitcoin and Ethereum. It has since found work well beyond digital money. At bottom it is a distributed ledger that makes transactions transparent, secure, and immutable, and that turns out to be useful in a lot of places. Here are some of the main applications of blockchain technology:
- Cryptocurrencies (e.g., Bitcoin, Ethereum)
The famous one. Blockchain is how cryptocurrencies are created and managed, acting as a decentralized ledger of every transaction. People can pay each other directly, peer to peer, with no bank sitting in the middle.
- Supply Chain Management
Where did this product actually come from? Blockchain gives supply chains end-to-end visibility, so you can follow goods from their origin through every hand they pass through. That cuts fraud, proves products are genuine, and makes the whole chain run more efficiently.
Read Our Blog: What Are The Top 10 Companies To Hire Blockchain Developers from
- Smart Contracts
A smart contract is an agreement written directly in code. When the conditions it describes are met, it runs itself. Blockchain’s security and trustworthiness make it a natural home for these contracts, which are showing up in legal agreements, insurance, and beyond.
- Identity Verification
Identity checks can run on blockchain in a way that is secure and resistant to tampering. People keep control of their own data and share only the pieces they choose with parties they trust, which lowers the risk of identity theft and fraud.
- Healthcare and Medical Records
Medical records need to stay accurate and private. Blockchain protects both. Patients can grant secure access to their own data, and healthcare providers can share information more easily without giving up privacy.
- Voting Systems
Voting on a blockchain records every vote as a transaction. That makes the results very hard to tamper with and the election easier to audit, and more trust in the democratic process follows.
Read Also: Investing in Blockchain Development: A Strategic Guide for Businesses
- Intellectual Property Rights
Who made it first? Artists, writers, and other creators can timestamp their work on a blockchain, which leaves hard proof of creation and ownership and helps protect their intellectual property.
The list keeps growing as the technology matures. Companies in many industries are testing new ways to use blockchain to run more efficiently, securely, and transparently. And the current trends in blockchain suggest its impact is only going to get bigger, pushing digital transformation into its next phase.
What are the Latest Trends in Blockchain Technology?
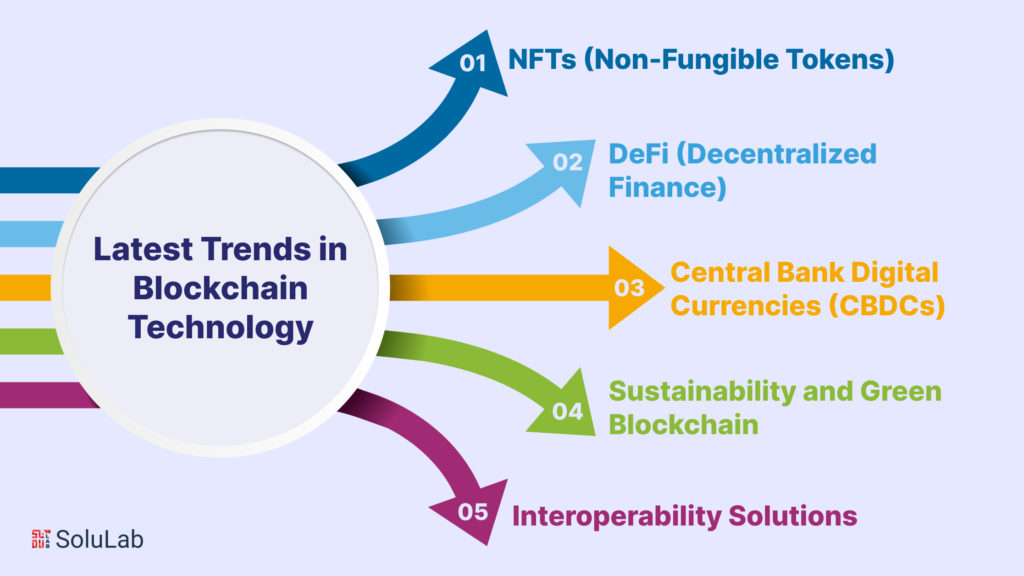
Blockchain arrived as the plumbing under cryptocurrencies. It has changed a great deal in the years since, and it now reaches well past digital money. These are the trends shaping where it goes next.
NFTs (Non-Fungible Tokens)
- Non-Fungible Tokens, or NFTs, swept through digital art and collectibles. Each NFT is a unique digital asset that stands for ownership of something, digital or physical. Blockchain records who owns it and where it came from, and that proof of provenance is why NFTs carry so much value in art, music, gaming, and even virtual real estate.
- They have also changed how people think about ownership and authenticity, and they push against long-standing copyright and intellectual property norms. Artists, musicians, and creators now use NFTs to sell their digital work straight to buyers, no middlemen involved.
DeFi (Decentralized Finance)
- Decentralized Finance, or DeFi, is shaking up traditional finance. DeFi apps run on blockchain networks and give anyone open, permissionless access to lending, borrowing, trading, and yield farming. With banks cut out of the loop, users keep more control over their own assets.
- Growth has been explosive, pulling in users and developers alike. But there are real problems too. Security holes and regulatory questions both need answers before DeFi can last over the long term.
Central Bank Digital Currencies (CBDCs)
- A Central Bank Digital Currency is a digital version of a fiat currency, issued by the central bank itself. The goal is to pair what blockchain does well with the stability of traditional money. Governments and central banks around the world are studying CBDCs as a way to modernise payment systems, widen financial inclusion, and fight illicit activity.
- This is a big shift for the financial system. It could also change how people adopt and use cryptocurrencies such as Bitcoin and stablecoins.
Read Our Blog Post: Top 20 Supply Chain Startups That Are Using Blockchain Technology
Sustainability and Green Blockchain
- Energy use is a sore point. Some networks, especially those running Proof of Work (PoW), burn a lot of power, and that has drawn environmental criticism. The response has been a steady move toward greener consensus mechanisms such as Proof of Stake (PoS).
- Green blockchain projects try to shrink the technology’s carbon footprint without giving up the security and decentralization that make it worth using. That puts them in step with wider global sustainability goals.
Interoperability Solutions
- Here’s a stubborn problem. Most blockchain networks work in isolation, so assets and data can’t move easily from one to another. Interoperability solutions aim to close those gaps and let separate networks talk to each other and pass value back and forth smoothly.
- Projects and protocols built for this, Polkadot and Cosmos among them, are picking up momentum. They make cross-chain communication possible and help build connected blockchain ecosystems.
How is SoluLab Pioneering the Digital Revolution Through its Blockchain Development Expertise?
Blockchain started life as the backbone of cryptocurrencies like Bitcoin. It has outgrown that job and now drives new ideas across many industries. For any business going digital, knowing how blockchain works, where it applies, and how to use it well is no longer optional. SoluLab, a blockchain development and consulting company, works right at that point.
A quick recap. A blockchain is a decentralized, immutable digital ledger that records transactions across a network of computers. It runs peer to peer and uses strong cryptography to protect data. Each “block” holds a set of transactions, and the blocks link together in the order they were created, which keeps the record transparent and secure.
Blockchain Development with SoluLab
- Blockchain Platforms
SoluLab builds on established blockchain platforms such as Ethereum and Hyperledger to deliver solutions that scale and stay secure. Those platforms are the base layer for decentralized applications (DApps) and for enterprise-grade blockchain networks.
- Role of Blockchain Development Companies
Most organizations don’t need blockchain in theory. They need it wired into what they already run. SoluLab guides them from first conversation to launch, offering consultation, development, and implementation so the new system fits cleanly with existing ones.
- Blockchain Development Services
SoluLab covers blockchain development end to end, including smart contract development, decentralized application development, blockchain consulting, and integrating blockchain into existing systems.
Blockchain is already reshaping whole industries. The hard part for most organizations is turning that into something that works in their own operations, and that is the gap SoluLab’s development and consulting teams are built to close.
Conclusion
Once you see how blocks, hashes, keys, and consensus fit together, it’s clear why blockchain has become a foundation for digital transformation rather than a side project. SoluLab has built its name on developing blockchain solutions, and it is counted among the leading blockchain companies.
SoluLab knows this technology well. It can explain the fine print, and it can also hand businesses working, modern blockchain development services. Blockchain trends will keep shifting, and SoluLab keeps pace, adapting its work so clients can use blockchain to move their digital transformation forward.
If you want blockchain working for your business, SoluLab is a strong place to start. You can hire top blockchain developers and tap into full blockchain consulting services in one place, and that combination is what sets SoluLab apart. Blockchain stopped being just a buzzword a while ago. The real question now is which problem in your business it should solve first.
FAQs
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.