

Key Takeaways
- Claims is where the money is. Document intake, triage and eligibility decisions carry the most manual cost per policy and the clearest automation path. SoluLab’s work with Ambetter Health Insurance cut claims processing time by 40% and flagged 85% of fraudulent claims.
- Regulators already have rules. The NAIC adopted its Model Bulletin on the use of AI by insurers in December 2023, and its AI Systems Evaluation Tool is being piloted by 12 states as of March 2026. Governance is not optional any more.
- Adoption is already mainstream. In NAIC’s own surveys, 92% of 93 health insurers and 88% of 193 auto insurers report using, planning to use, or exploring AI/ML models.
- The EU AI Act clock matters if you write risk in Europe. The Act became applicable on 2 August 2026, and Annex III high-risk obligations, which cover insurance pricing and risk assessment, apply from 2 December 2027.
- Budget realistically. SoluLab prices insurance AI from $18,000 for a non-enterprise-grade app to $60,000+ for a full enterprise platform, and a production use case typically runs a 10 to 16 week build. Treat anything promising a regulated decision in production in three weeks with suspicion.
AI in insurance is the use of machine learning, generative AI and agentic systems to automate and improve core insurance work: first notice of loss, claims triage and settlement, fraud detection, underwriting risk assessment, policy servicing and customer support. Insurers apply it to cut cycle times and loss leakage, not to replace regulated human judgment.
What is AI in insurance?
Definition. AI in insurance is the application of predictive machine learning, generative AI and agentic AI to insurance operations, so that document-heavy and judgment-heavy tasks (claims adjudication, risk scoring, fraud triage, policy servicing) can be done faster and more consistently than by manual review alone.
Three different technologies get bundled under one label, and they fail in different ways. Separating them is the first useful thing an insurer can do.
Predictive machine learning scores things. Given a claim, a policy or an applicant, it returns a number: probability of fraud, expected severity, likelihood of lapse. It is the oldest and best understood category in insurance, it is also the category regulators scrutinise hardest, because a score that drives pricing or eligibility is a decision about a consumer.
Generative AI reads and writes. It summarises a 60-page loss adjuster report, drafts a denial letter, extracts structured fields from a hospital bill, answers a policyholder question in natural language. Its weakness is that it will produce fluent output even when it is wrong, so it belongs behind validation rather than in front of a customer unsupervised.
Agentic AI takes steps. Rather than returning a single answer, it executes a sequence: pull the policy, check coverage dates, retrieve the medical codes, compare against the MGA rule set, write the eligibility decision, route the exception to a human. This is where most of 2026’s real operational savings sit, and also where governance gets hardest, because the system is now acting rather than advising.
Where does AI actually create value in an insurance business?
AI in insurance pays off where three things overlap: high volume, heavy unstructured documents, and a decision that follows rules a machine can learn. That points at a narrow set of functions, not the whole enterprise.
| Function | What AI does | Typical measurable effect | Difficulty |
| Claims intake and triage | Reads FNOL, bills, estimates, police reports; extracts fields; routes by severity | Cycle time, straight-through-processing rate | Low to medium |
| Fraud detection | Scores claims against network and behavioural patterns | Loss leakage, detected fraud rate | Medium |
| Claims adjudication | Checks coverage and eligibility against the rule set | Touch rate per claim, adjuster hours | Medium to high |
| Underwriting risk assessment | Scores and prices submissions, flags for referral | Quote turnaround, hit rate, loss ratio | High (regulated) |
| Policy servicing | Handles endorsements, renewals, document requests | Cost per service interaction | Low |
| Customer support | Answers coverage and status questions; drafts responses | Containment rate, CSAT | Low |
| Subrogation and recovery | Identifies recoverable claims from file text | Recovery dollars captured | Medium |
The functions in the bottom half are where most insurers start, because the regulatory exposure is lower and the data is cleaner. The functions at the top are where the money is. A sensible sequence is to prove the platform on servicing and intake, then move into adjudication once governance is in place.
How do insurers implement AI in claims? A seven-stage walk-through
Claims is not one task. It is a chain of about seven, and AI slots into each differently. This is the walk-through most insurers ask for, so here is the whole chain rather than a list of buzzwords.
Stage 1. First notice of loss. The claim arrives by portal, phone, email or broker upload, in whatever format the claimant chose. AI’s job is normalisation: transcribe the call, read the attachments, and populate the claim record. Optical character recognition handles the scanned documents, and a language model maps free text onto your schema. The success measure is the share of claims that reach the next stage with no human data entry.
Stage 2. Document understanding. This is the foundation, and the stage most projects underestimate. A health claim might arrive with an itemised bill, an explanation of benefits, a referral letter and a handwritten note. The system has to know which document is which, pull the right fields from each, and say honestly when a field is missing or illegible. In our InsureCheck build, a claims platform for an MGA, document understanding was the entire basis of the product, because the eligibility decision downstream is only as good as the extraction upstream.
Stage 3. Coverage and eligibility check. With fields extracted, the system compares the claim against the policy: were the dates in force, is the peril covered, are the limits and deductibles right, does the MGA rule set permit this claim to pass. This is deterministic logic reading AI-extracted inputs, which is the correct division of labour. You do not want a language model deciding coverage. You want it reading the documents that the rules engine then evaluates.
Stage 4. Fraud and anomaly scoring. The claim is scored against historical patterns, provider networks, repair-shop behaviour and claimant history. A high score does not deny the claim. It routes it to a special investigations unit with the reasons attached, which matters both operationally and legally.
Stage 5. Severity estimation and reserving. A model predicts likely final cost so reserves are set correctly from day one rather than adjusted repeatedly. For motor and property, image models on damage photographs do real work here.
Stage 6. Settlement decision and payment. Low-value, low-risk, fully documented claims settle straight through. Everything else goes to an adjuster, but arrives with the file summarised, the policy language cited and a recommendation attached, which is where adjuster time is actually saved.
Stage 7. Communication and closure. Generative AI drafts the settlement or denial explanation in plain language, which an adjuster reviews and sends. Denials in particular should never auto-send, for reasons that are regulatory as much as reputational.
The pattern worth noticing: AI reads, scores, drafts and routes. Rules decide coverage, and humans own denials, disputes and anything where a consumer is adversely affected. Insurers that blur that line are the ones that end up in front of a regulator.
How does AI change underwriting?
AI changes underwriting by scoring submissions before a human sees them, so underwriters spend their time on the risks that need judgment instead of the ones that need data entry. Submission intake, exposure extraction, triage and referral routing are the parts that automate well. Pricing and declination decisions stay under human and actuarial control.
The practical gain is triage. A commercial underwriter receiving 200 submissions a week does not need help pricing the complex 20. They need the other 180 sorted, enriched and either auto-quoted or routed with the exposures already pulled out of the broker’s spreadsheet. In SoluLab’s Ambetter engagement, automating the underwriting path improved decision accuracy by 90% against the manual baseline, largely by removing transcription errors rather than by out-predicting the underwriter.
Underwriting also carries the heaviest regulatory load of anything on this page, because a model that influences eligibility or price is a model that can discriminate. That is the explicit subject of Colorado’s SB21-169 and of the NAIC bulletin discussed below.
Underwriting has its own detailed page on this site. For model design, referral logic, rating integration and the governance a rate filing needs, see AI in insurance underwriting.
How do insurers use AI to detect fraud?
AI detects insurance fraud by scoring every claim against patterns no individual adjuster can see: claimant and provider history, repair-shop and clinic networks, timing anomalies, document tampering signals and text similarity across unrelated claims. The output is a ranked referral queue with reasons, not an automated denial.
Three signal families do most of the work:
- Behavioural. Claim filed days after policy inception, coverage increased shortly before loss, repeated claims just under the inspection threshold.
- Network. The same clinic, contractor, towing firm or legal representative appearing across apparently unconnected claims. Graph models are genuinely strong here and are difficult to replicate with rules.
- Document. Edited invoices, reused photographs with altered metadata, template language recurring across different claimants.
On the Ambetter build, the fraud detection layer identified and prevented 85% of fraudulent claims. The honest caveat on any number like that is the denominator: it measures against fraud the programme was able to confirm, so treat it as a strong operational result rather than a claim about all fraud in the book.
One design rule worth stating plainly. A fraud model must output reasons, not just a score. An investigator who receives “0.87” learns nothing. An investigator who receives “0.87, driven by third claim from this clinic in 60 days and invoice metadata modified after issue date” can act that morning. Explainability here is an operational requirement before it is a compliance one.
What are the main AI use cases in insurance by line of business?
The five use cases that recur most often across insurance lines are claims document automation, fraud scoring, underwriting triage, policy servicing automation and customer support containment. How they rank changes by line.
| Line of business | Highest-value AI use case | Second | Data that makes or breaks it |
| Auto / motor | Damage assessment from photographs, straight-through settlement of low-value claims | Repair-network fraud detection | Image quality standards, parts and labour pricing data |
| Property / home | Severity estimation and reserving from loss photos and adjuster notes | Catastrophe surge triage | Geospatial and peril data, historical loss files |
| Health | Claims eligibility and adjudication against benefit rules, coding validation | Prior-authorisation automation | Clean HL7 and FHIR feeds, benefit rule sets, coding dictionaries |
| Life | Accelerated underwriting from medical and prescription records | Lapse and surrender prediction | Medical records access, mortality tables, consent trail |
| Commercial / specialty | Submission intake and exposure extraction from broker spreadsheets | Referral triage for underwriters | Broker document variance, exposure schedules |
| Reinsurance | Portfolio exposure aggregation from cedent bordereaux | Treaty wording analysis | Bordereaux consistency across cedents |
Health insurance deserves a note. NAIC’s survey found 92% of 93 health insurers using, planning to use, or exploring AI/ML, the highest penetration of any line. It is also the line where benefit rules are most explicit, which is exactly what makes automated adjudication tractable. That combination is why health claims platforms are the most common place we see an insurer’s first production AI system.
What does an insurance AI architecture actually look like?
A production insurance AI architecture has five layers: ingestion, document understanding, a decision layer that separates models from rules, an orchestration layer that routes to humans, and a governance layer that logs everything. The separation between the model and the rules engine is the single most important design decision.
Here is the reference shape we build to.
The parts that matter, and why:
- Ingestion accepts whatever the real world sends: portal uploads, broker emails, EDI, phone transcripts, scanned post. Normalising here rather than downstream prevents a long tail of edge-case failures.
- Document understanding is OCR plus a vision-language model plus a classifier, with a confidence score on every extracted field. Fields below threshold go to human review rather than silently through. This is the component that decides whether the whole system works.
- The decision layer is deliberately split. Models produce scores and drafts. A deterministic rules engine holds coverage logic, benefit rules and the MGA or policy conditions. When a regulator or an auditor asks why a claim was handled a certain way, you point at the rule, with the model’s input recorded as evidence.
- Orchestration routes each case by confidence and risk: straight-through, adjuster review, or special investigations. Agentic workflows live here, with a hard requirement that every action is reversible and logged.
- Governance captures model version, inputs, outputs, confidence, the human who intervened and the final disposition, per case. The NAIC Model Bulletin effectively expects an insurer to be able to produce this. Building it at the end costs several times what building it on day one costs.
How much does AI in insurance cost?
AI in insurance builds with SoluLab start at $18,000 for an application that does not need enterprise grading, $24,000 for an MVP built on the enterprise track, and $60,000 and up for a full enterprise-grade platform. A white-label build is $30,000. Insurance is priced above SoluLab’s general AI rate because core-system integration, model validation and regulatory evidence add real work.
| Engagement tier | Price | What it covers |
| Basic | $18,000 | A working application that does not require enterprise grading. Suits a contained servicing, triage or document task with no regulated decision attached. |
| MVP | $24,000 | A first production version built on the enterprise track, so the integration, logging and governance foundations are in place from the start. |
| White label | $30,000 | A pre-built platform configured and branded for your business, faster to deploy than custom. |
| Advance | $60,000+ | Full enterprise-grade platform: multiple use cases, deep core integration, bias testing harness and the audit trail the NAIC, NYDFS and Colorado requirements expect. |
Most insurers writing regulated business land in the Advance tier, for the same reason the regulatory section above describes. Once a model influences coverage, eligibility or price, the bias testing, reason codes, per-decision logging and model registry stop being optional, and those are engineering line items rather than documentation.
Budget for running costs separately. Model usage or GPU hosting, monitoring, retraining and periodic revalidation recur every month and scale with claim volume. They are not in the build price.
What moves you between tiers:
| Cost driver | Cheap end | Expensive end |
| Document variety | One or two standard forms, machine-generated | Mixed scans, handwriting, multi-jurisdiction formats |
| Integration surface | Read-only API on a modern core | Writing back into a legacy policy admin system with no API |
| Decision criticality | Summarisation, routing, drafting | Coverage, eligibility or pricing decisions |
| Governance depth | Internal tooling, no consumer impact | Regulated decisions needing bias testing and audit trail |
| Data readiness | Clean, labelled historical claims | No labelled data, so annotation is part of the project |
| Volume | Thousands of claims a month | Millions, which changes architecture and hosting |
Two patterns we see repeatedly. First, the policy administration system is the real cost centre. A document-understanding pipeline is well-understood engineering, but writing a decision back into a twenty-year-old core without an API is where budgets go. Second, labelled data is frequently missing. If nobody recorded which historical claims were fraudulent, the first phase of the project is building that ground truth, and that is a real line item rather than a rounding error.
Pricing above is SoluLab’s published service and cost list for AI in the insurance vertical, current as of 10 September 2026.
How long does an insurance AI project take?
A focused claims or servicing use case typically runs 10 to 16 weeks from kickoff to production, assuming data access is granted in the first fortnight. Regulated decisions that need bias testing and a rate or filing review take longer, usually 5 to 8 months, because the governance work runs in parallel with the build rather than after it.
A realistic shape:
- Weeks 1 to 2. Discovery, data access, baseline measurement. If you cannot measure the current cycle time and touch rate, you cannot prove improvement later.
- Weeks 3 to 5. Document understanding on real documents, not samples. This is where unpleasant surprises surface, which is why it comes early.
- Weeks 6 to 9. Decision layer, rules integration, orchestration and human routing.
- Weeks 10 to 12. Shadow mode. The system runs on live claims without acting, and its outputs are compared against adjuster decisions.
- Weeks 13 to 16. Staged rollout by claim type and value band, with governance artefacts produced as you go.
Shadow mode is the step most often cut for time, and cutting it is almost always a mistake. It is the only cheap opportunity to discover that the model is confidently wrong about a claim category you did not think about.
How should an insurer implement AI? A six-step roadmap
- Pick one use case with a measurable KPI. Not “AI in claims”. Something like “reduce average touch count on motor claims under £2,000 from 4.1 to 2.0”. If you cannot write the baseline down, start by measuring it.
- Audit the data and the core system. Where do the documents live, what format, who grants access, and can you write a decision back into the policy admin system. Answer this before design, because the answer frequently changes the design.
- Decide what the model decides, and what the rules decide. Write it down explicitly. Coverage, eligibility and pricing logic belong in rules. Reading, scoring, drafting and routing belong to models.
- Build governance alongside the build. Model registry, reason codes, per-decision logging, bias testing harness. This is a requirement under NYDFS and Colorado, and the artefacts are what a regulator asks for.
- Run shadow mode on live traffic. Compare the system against human decisions on real claims, segment by claim type, and look specifically for categories where confidence is high and accuracy is not.
- Roll out in bands, keep the human in the loop where it counts. Start with low-value, fully documented, low-risk claims. Keep denials, disputes and anything adverse to a consumer under human authority.
What goes wrong with insurance AI projects?
Most AI in insurance projects fail for operational reasons, not model reasons. The five recurring causes:
Document reality. Pilots are run on clean sample documents and production receives phone photographs of crumpled invoices. If your pilot never saw a handwritten note or a Polish-language medical report, your pilot proved nothing about production.
Legacy core integration. The model works and cannot write its answer anywhere. This is discovered at week ten of a twelve-week project with depressing regularity.
No labelled ground truth. Nobody can say which historical claims were fraudulent or which decisions were correct, so there is nothing to train or evaluate against. Budget for annotation.
Governance retrofitted. The system goes live, then a regulator or an internal audit asks for a per-decision log and a bias test, and the team discovers neither was designed in. Re-architecting a live claims system is expensive.
Scope that starts at pricing. Teams begin with the most regulated, highest-stakes decision because it has the biggest headline number, then stall in review for months. Starting at intake and servicing builds the platform, the trust and the governance muscle that make the hard use cases possible later.
One more, worth naming honestly: AI is a poor fit for insurance problems that are genuinely about missing information rather than slow processing. If a claim is stuck because a third party has not sent a document, no model fixes that. Automating a chase process might.
Where is AI in insurance heading?
The direction of travel for AI in insurance in 2026 is from systems that advise to systems that act, under tighter supervision. Three shifts are visible in the work insurers are actually funding.
From scoring to workflow. The first generation of insurance AI returned a number that a human then acted on. The current generation executes the steps: retrieve, check, decide within bounds, route the exception. The constraint is no longer model quality. It is whether the surrounding system can log and reverse what the agent did.
From one model to a portfolio with a registry. Insurers running six or eight models in production are discovering they need the same inventory, monitoring and attestation machinery a bank needs for model risk. That is what the NAIC evaluation tool is probing for.
From vendor tools to owned decision layers. Because NYDFS puts responsibility for third-party systems on the insurer, and because Colorado requires an officer to attest, insurers are becoming less willing to accept a vendor black box in the decision path. The pattern we are asked for now is a vendor model behind an insurer-owned rules and logging layer.
The thing that will not change is where accountability sits. An adverse decision against a policyholder is the insurer’s decision, whatever produced it.
Who provides AI solutions for insurance?
Insurance AI is delivered by three kinds of provider: the large consultancies, the insurtech point-solution vendors, and engineering-led AI partners who build into your existing policy administration estate. Which one fits depends on whether you need advice, a product, or a system that integrates with a core you already run.
SoluLab sits in the third category. We are an AI and GenAI engineering partner, consulting-led, and the insurance work we are asked to do is usually document-heavy claims automation with a compliance requirement attached.
Understanding the Need for AI in Insurance
Think about what buying insurance used to mean. Stacks of forms, meetings that ate an afternoon, claims that asked for documents you did not know you needed, and then months of waiting for someone to decide.
Artificial intelligence in insurance brought automation into that picture, and trust started coming back with it. Companies now run AI solutions for insurance to grow the book, strip out risk and fraud, and automate the core operations that were quietly draining budget.
AI in health insurance matters here too. It tightens operations and lets insurers price premiums against a much deeper read of the data instead of a broad category. Underwriting gets shorter, fewer hands touch each file, and applicants can connect with health insurance carriers directly rather than through three intermediaries.
Read Blog: Generative AI in Healthcare
The short version: AI insurance pays off on both sides of the contract. Here’s how.
- AI in the insurance sector sharpens risk analysis, catches fraud, and takes human slips out of the equation.
- AI in insurance makes customer service better and faster, and it does the same for claims processing.
- Underwriting improves once AI handles the repetitive judgment calls and fewer people have to intervene.
- With AI and ML in insurance, underwriters measure risk more precisely, which means premium pricing can actually be personal.
- And AI in the insurance sector shortens the path between an applicant and an insurer, cutting the steps in between.
How Does Artificial Intelligence Add Value to the Insurance Sector?
To stay relevant, insurers have to fold in the newer technologies: metaverse, blockchain, artificial intelligence, robotic process automation, whatever fits the problem. So look at where those tools actually touch an insurance process that today is slow and exhausting for everyone involved. But value only counts when the implementation of Gen AI in insurance industry produces something you can measure. A few places it does:
- Optimized Claim Processing
Claims processing is genuinely hard work. An agent has to read through several policies, understand the fine print in each, and then work out what the customer is actually owed. AI for insurance takes over the mechanical half of that job, which cuts both the errors and the clock time on a claim.
Bring in AI, RPA, and IoT together and the operational gain compounds. Insurers suddenly have a pipeline into smart home assistants, fitness trackers, healthcare wearables, a whole spread of connected devices. AI and Insurance working in tandem means data arrives on its own, insurers stay close to policyholders instead of hearing from them once a year, and the insight that feeds underwriting and claim management is far richer. Risk drops as a result.
- Assessing Risk
Underwriting leaned almost entirely on the applicant filling out standard forms by hand. People lie. People also just get things wrong, and either way the risk assessment that comes out the other end is off.
Research on the advantages of AI in insurance, underwriting especially, points to three things it can do:
- Model a future market with 83% accuracy.
- Reduce processing time in underwriting by 10-fold.
- Boost case acceptance by 25%.
- Fraud Detection and Prevention
Roughly $1 trillion in premiums flows into the insurance sector every year. At that size, fraud is not a rounding error. Non-health insurance fraud is expected to cost more than $40 billion annually, and households pay for it: $400 to $700 extra on premiums.
Gen AI in insurance is rewriting how fraud gets caught. Push enough data through it and the odd patterns surface, insurers get flagged in real time rather than after the payout clears. Less risk, smaller losses, and operations that hold up under scrutiny. The policyholder benefits too, because false claims are what push everyone’s rate up.
- Reporting of Claims
For claim filing, AI can take the first notification of loss with almost no human touch. From there the system allocates, routes, reports, and prioritizes the claim on its own.
People report incidents at 2am, from a phone, on the side of a road. Chatbots handle that intake without complaint and move the claim along. Build Chatbots with AI then pushes the information onward to whatever needs to process it next.
- Investigation and Management of Insurance Claims
Paired with the right applications, AI and ML in insurance automate the hunt for fraudulent activity across the whole chain: data collection, claims processing, authorizations, permits, payment tracking, recovery tracking. Every step, monitored. That is where the time and money come back.
Artificial Intelligence in insurance processes can run and improve a wide spread of functions.
- Enhanced Standard Procedures
Customer service in insurance looks nothing like it did a decade ago, and artificial intelligence is the reason. As noted above, a chatbot is the cheapest way to open a process and hand the information to whoever needs it next, with no person in the loop. Quick, simple, and hard to get wrong.
AI chatbots also upsell and cross-sell, reading a customer’s purchase history and profile before they suggest anything. Automate the repetitive layer and operations scale without a matching headcount jump, while the humans you already have move to work that deserves them.
- Better Way to Estimate Losses
Damage assessment has gotten much easier, thanks to machine learning, deep learning, and optical character recognition (OCR). Upload a photo of the damaged object. That is roughly the whole workflow now, and the extent of the damage comes back fast.
The same technologies also forecast losses before they land and offer advice worth acting on.
Use Cases of AI in Insurance
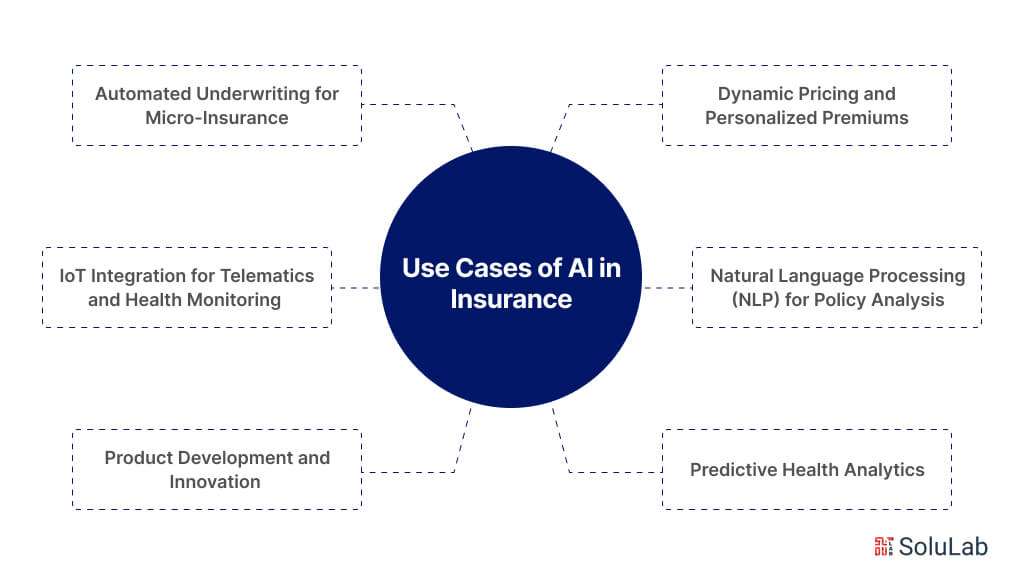
The list of AI use cases in insurance is long, and it stretches across the whole business. Risk management, underwriting, customer service, product design. Each one gets faster, cheaper, or more accurate, and the customer usually notices.
Some of the AI in insurance use cases:
Customer Segmentation and Targeted Marketing: AI analytics pull apart the customer base along demographic, behavioral, and psychographic lines. Insurers then aim campaigns and products at the segment that will actually respond, and engagement and conversion both move.
- Dynamic Pricing and Personalized Premiums: Algorithms read individual risk factors and behavioral data, then move the premium in real time. Drive carefully, pay less. That is the incentive, and it pushes policyholders to reduce their own risk rather than wait for a claim.
- Automated Underwriting for Micro-Insurance: Small, low-premium policies never justified manual underwriting. AI models handle that assessment cheaply, which is what makes micro-insurance viable for low-income customers. Insurers reach people they previously could not serve, and the numbers still work.
- Natural Language Processing (NLP) for Policy Analysis: NLP tools read dense policy documents and pull out what matters: coverage limits, exclusions, terms. Underwriting and claims teams get the details in seconds instead of an afternoon, and they decide on better information.
Read Also: Top 10 Applications of Natural Language Processing
- IoT Integration for Telematics and Health Monitoring: Telematics in cars, wearables on wrists. Insurers use both to see what policyholders are actually doing and how their health is trending, in real time. That feeds risk assessment, pricing, and reward programs, and it nudges people toward safer driving and better habits.
- Product Development and Innovation: AI surfaces market trends, shifting customer preferences, and risks that did not exist last year. Insurers build new products against that signal instead of guesswork, which is how a crowded market stays interesting.
- Predictive Health Analytics: AI in health insurance reads wearable data, electronic health records, and other sources, looking for the patterns that precede a health risk or a chronic condition. Catch it early and the insurer can step in with a health management program or preventive care instead of paying for the crisis later. Better outcomes for the person, lower cost for everyone.
Top Trends and Innovations Driven by AI Changing the Insurance Industry
Adopting these technologies is not free. The insurance business has a steep learning curve ahead of it, and the people holding the policies will feel the changes as much as the companies writing them. A few of the trends worth watching:
- High Personalization
Plans can now be built around one person rather than a category, because AI can hold that much detail. Feed a system data on lifestyle, behavior, and stated preferences and it will assemble a personalized insurance solutions. In a market this competitive, that level of tailoring is what keeps existing customers and wins new ones.
- Explosion of Data from Networked Devices
Connected devices multiplied, and data creation went up with them. IoT sensors and smart devices are collecting and transmitting at a volume nobody planned for. That is an opportunity and a headache at once, because storing it, reading it, and deciding on it are three separate problems. Companies that handle the flood well stay competitive. The rest drown in it.
- Extended Reality
Extended reality is where virtual reality goes next. The insured object no longer has to physically be somewhere for someone to look at it. File the claim, and AI runs a virtual examination instead. If the safety features of the car are already known, quoting a better rate gets much easier.
- Data Accuracy
In AI, data is king. The whole exercise is gathering data from many sources and making sense of it. But the business decisions are only as good as the inputs, and reliable, exact data is what separates a useful model from an expensive one. Get that right and insurers can head off risk and fraud before either one costs them anything.
Factors Driving Implementation of AI in Insurance Industry
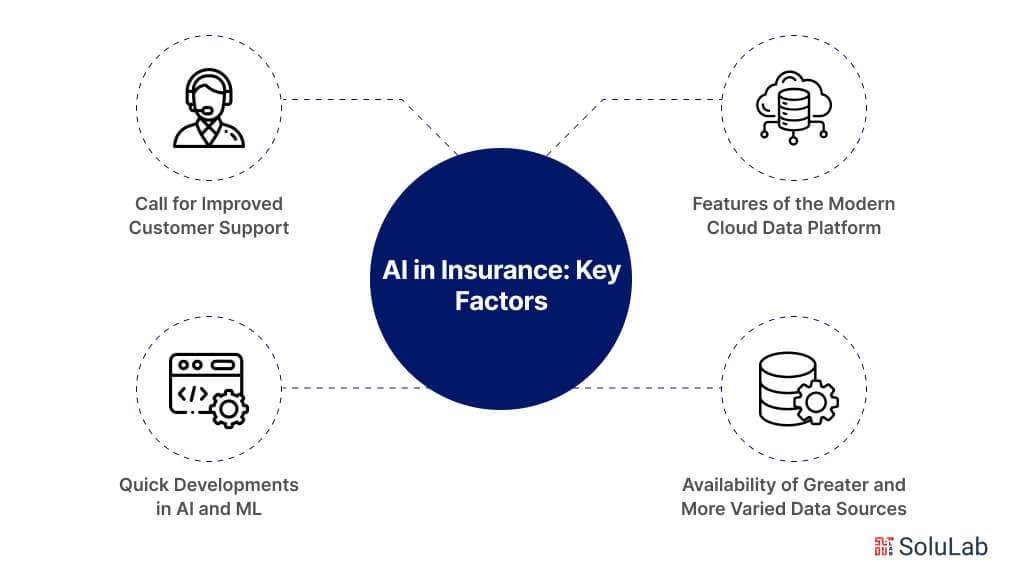
Market share and profitability are both climbing for insurers who deployed AI. So why now? A handful of forces pushed the industry over the line at roughly the same time.
- Quick Developments in Artificial Intelligence and Machine Learning
Machine learning and AI moved fast, and every jump opened another way to pull value out of data an insurer already owned. Take large language modeling (LLM), a subfield of artificial intelligence built to read document data intelligently. With LLMs, claims move faster and fraudulent ones get flagged with better accuracy. Generative AI is the other example: it stitches together functions, data, and tools, then reasons its way to an answer. Early days still. The potential for insurance is hard to overstate.
- Availability of Greater and More Varied Data Sources
There is simply more raw material now. The count and variety of data sources jumped, and third-party information turned into something insurers cannot ignore: consumer credit, marketing files, social posts, shopping behavior, criminal records, prior claims, weather. Each one feeds something. Marketing gets sharper, risk models get closer to reality, underwriting and claims handling both improve.
- Call for Improved Customer Support
Customers stopped accepting business-hours support. Chatbots and virtual assistants now give them individual answers at any hour, which is a different standard than the industry held five years ago. Behind those front-line systems sits natural language processing (NLP), the branch of artificial intelligence that lets machines understand and respond to written and spoken language. It absorbs the basic questions around the clock, and human agents get to spend their time on the messy cases that need a person.
- Features of the Modern Cloud Data Platform
Cloud data platforms like Snowflake made storing and processing huge volumes both practical and affordable. Structured, semi-structured, unstructured: it all lands in the same place, so insurers can train and refine AI models on data sets they previously kept in separate silos. Compute scales elastically, which is what keeps AI and ML workloads from becoming a capacity planning exercise.
Final Words
AI has reshaped insurance operations, customer experience, and risk strategy, and the change runs deeper than a tooling upgrade. Underwriting got shorter. Fraud detection got sharper. Customer service got personal. Insurers who keep pushing on AI will find more efficiency and more competitive room in a business that is now thoroughly digital. But the ethics do not take care of themselves. Transparency, fairness, and accountability in how these systems are used are what earn trust, and without them the risks come back in a different form.
Deployment is where most insurance teams get stuck, which is why working with experienced AI development companies such as SoluLab tends to shorten the path. SoluLab builds around the specific business problem rather than shipping a generic product: chatbots and virtual assistants for client interaction, pricing model optimization, claims processing automation, whatever the gap actually is. SoluLab is a trustworthy AI development company pushing the insurance industry’s transformation forward with modern artificial intelligence (AI) solutions, and the focus stays on innovation and on customers who come back. Get in touch and tell us where your AI journey is stalling.
FAQs
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.