

Loan underwriting has always been messy and error-prone, and it has never kept pace with what financial markets actually demand. Traditional approaches bleed time: underwriters spend roughly 40% of their working hours on tasks that add no real value, as per Accenture. Over the next five years, that waste is projected to cost the industry $160 billion. And that is before you factor in what dissatisfaction with the claims process does to retention. Unhappy customers leave. That translates to a real risk of lost $170 billion in premiums.
AI changes the math here. By automating repetitive work like data gathering and risk evaluation, AI loan underwriting cuts the time and manual effort required for these tasks substantially. Systems process large volumes of data quickly, catch the kinds of errors humans miss when tired or distracted, and move decisions along faster. McKinsey reports that automation in insurance could cut claims processing costs by up to 30%. That figure tells you what is possible across financial services more broadly.
This post looks at how AI is reshaping loan underwriting in practice: where machine learning speeds up data processing, where it sharpens risk assessment, and how it compresses loan approval timelines. We cover the real problems with traditional underwriting, what AI actually solves, and what that means for accuracy, speed, and lending decisions.
What Exactly is Loan Underwriting?
Loan underwriting is the process a financial institution uses to examine a borrower’s creditworthiness and decide how much risk it is taking on by lending to them. This is especially relevant when businesses need to compare small business loans and choose the right financing option. The lender looks at credit history, income, employment stability, and the debt-to-income ratio. The goal is to judge whether the borrower can actually repay. From that judgment comes a decision: approve, modify, or decline. Along with that decision come the terms, including interest rate and loan amount. Done right, underwriting is the foundation of sound risk management and responsible lending.
Traditional Loan Underwriting vs. AI-Based Loan Underwriting
| Aspect | Traditional Loan Underwriting | AI-Based Loan Underwriting |
| Processing Time | A slow, manual process | A fast, automated process |
| Efficiency | Labor-intensive and subject to delays | Highly efficient and streamlined |
| Accuracy | Varies, reliant on human judgment | Consistent and data-driven |
| Consistency | Prone to human error and bias | Uniform decisions based on algorithms |
| Data Utilization | Limited to standard financial data | Leverages a broad range of data, including unconventional sources |
| Scalability | Difficult to scale | Easily scalable with increased data and resources |
| Cost Implications | Higher operational costs due to labor | Lower operational costs, with an initial investment in technology |
| Risk Assessment | Based on fixed criteria and manual reviews | Dynamic and continuous risk evaluation using real-time data |
| Decision Speed | Takes days to weeks | Completed within minutes to hours |
| Customer Experience | Slower response times | Faster approvals and an improved user experience |
| Compliance | Manual compliance checks | Automated compliance with real-time updates |
| Adaptability | Slow to adapt to new trends | Quickly incorporates new data and trends |
How Does AI Work in Loan Underwriting?
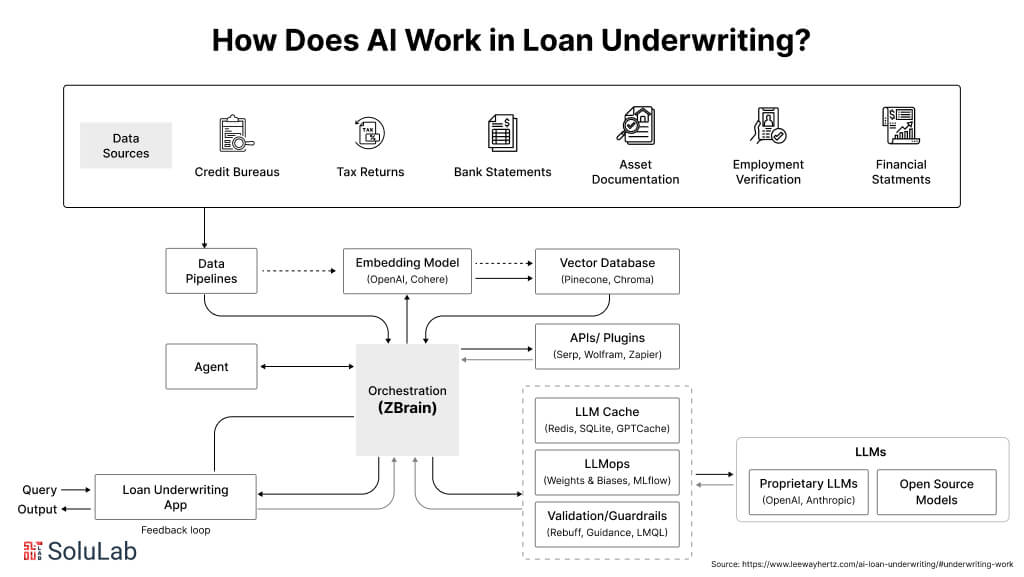
Bringing AI into underwriting means connecting several distinct components that automate data analysis, speed up processing, and surface actionable insights. The full system goes well beyond what traditional methods can do. It uses Large Language Models (LLMs) integrated with a financial institution’s own knowledge base, which sharpens the analysis and gets decisions out faster. Here is how the pieces fit together:
1. Data Sources
The first step is pulling data from multiple sources, including:
- Credit Bureaus: Credit reports from major bureaus like Equifax, Experian, and TransUnion help evaluate the borrower’s credit history, payment behavior, and creditworthiness.
- Financial Statements: Borrowers provide income statements, balance sheets, and cash flow statements to assess financial health and repayment ability.
- Tax Returns: Tax filings verify the borrower’s income and provide insights into their financial stability.
- Employment Verification: Confirming employment status and income through direct contact or employment documents.
- Bank Statements: Analyzing cash flow and spending patterns from bank records to assess debt management and repayment potential.
- Asset Documentation: Evaluating assets like real estate, investments, and collateral to determine the borrower’s financial standing.
- Credit References: Gathering additional creditworthiness information from other lenders.
2. Data Pipeline
Once collected, the data moves through a pipeline that handles ingestion, cleaning, filtering, and structuring. This step is unglamorous but non-negotiable: bad input at this stage corrupts everything downstream.
3. Embedding Model
Processed data gets segmented and fed into an embedding model, which converts text into numerical vectors that AI models can work with. Popular options here include embedding models from OpenAI, Google, and Cohere.
4. Vector Database
Those vectors get stored in a vector database built for fast querying and retrieval. Tools like Pinecone, Weaviate, and PGvector can manage billions of vectors and return comparisons quickly, which matters a lot when you are processing high application volumes.
5. APIs and Plugins
APIs and plugins, including Serp, Zapier, and Wolfram, connect the various components and bring in extra data where needed. Without these connectors, the system would be working in a silo.
6. Orchestration Layer
An orchestration layer, such as ZBrain, manages the whole workflow. It chains prompts, handles calls to external APIs, retrieves contextual data from the vector database, and keeps memory consistent across LLM calls. Think of it as the coordinator that stops the system from losing its thread between steps.
Read Our Blog: AI in Banking: Transforming Financial Services
7. Query Execution
When someone submits a query through the loan underwriting application, it kicks off the data retrieval and generation process. Queries might cover a borrower’s financial history, creditworthiness, employment, or the specific conditions around a loan.
8. LLM Processing
The orchestration layer pulls the relevant data from the vector database and LLM cache, then routes it to the right LLM for the job. Which LLM gets selected depends on what the query actually requires.
9. Output
The LLM produces a response: a creditworthiness assessment, a risk flag, a draft loan agreement, or a summary of the borrower’s financial position. What comes out depends entirely on what was asked.
10. Loan Underwriting App
The validated output surfaces in the loan underwriting app, where everything gets consolidated. Decision-makers can review the findings and act on them. The app is the interface between the AI’s analysis and the humans who still make the final call.
11. Feedback Loop
User feedback on the output feeds back into the system continuously, refining the AI underwriting process over time. The system gets more accurate with use, not less.
12. AI Agent
AI Agents are central to how the underwriting process actually runs. They tackle complex problems, interact with external environments, and keep improving after deployment through reasoning, planning, memory, and self-reflection.
13. LLM Cache
Frequently accessed data gets cached using tools like Redis, SQLite, or GPTCache. This cuts response times on repeat queries, which adds up fast in high-volume environments.
14. Logging/LLMOps
Throughout the process, LLMOps tools like Weights & Biases, MLflow, and Helicone log activity and track system performance. Continuous optimization through feedback loops depends on having this visibility.
15. Validation
A validation layer checks the LLM’s output for accuracy using tools like Guardrails, Rebuff, and LMQL. You do not want an AI system making lending decisions without something double-checking its work.
Check Our Blog Post: AI in Finance: A Guide for Financial Leaders
16. LLM APIs and Hosting
Executing loan underwriting tasks requires LLM APIs and a place to run them. Teams can use APIs from OpenAI or Anthropic, or go the open-source route. Cloud platforms, including AWS, GCP, and Azure, offer hosting options sized to project requirements.
This Agentic RAG architecture is what makes AI-based underwriting genuinely fast, data-driven, and consistent at scale.
Use Cases of AI in Loan Underwriting
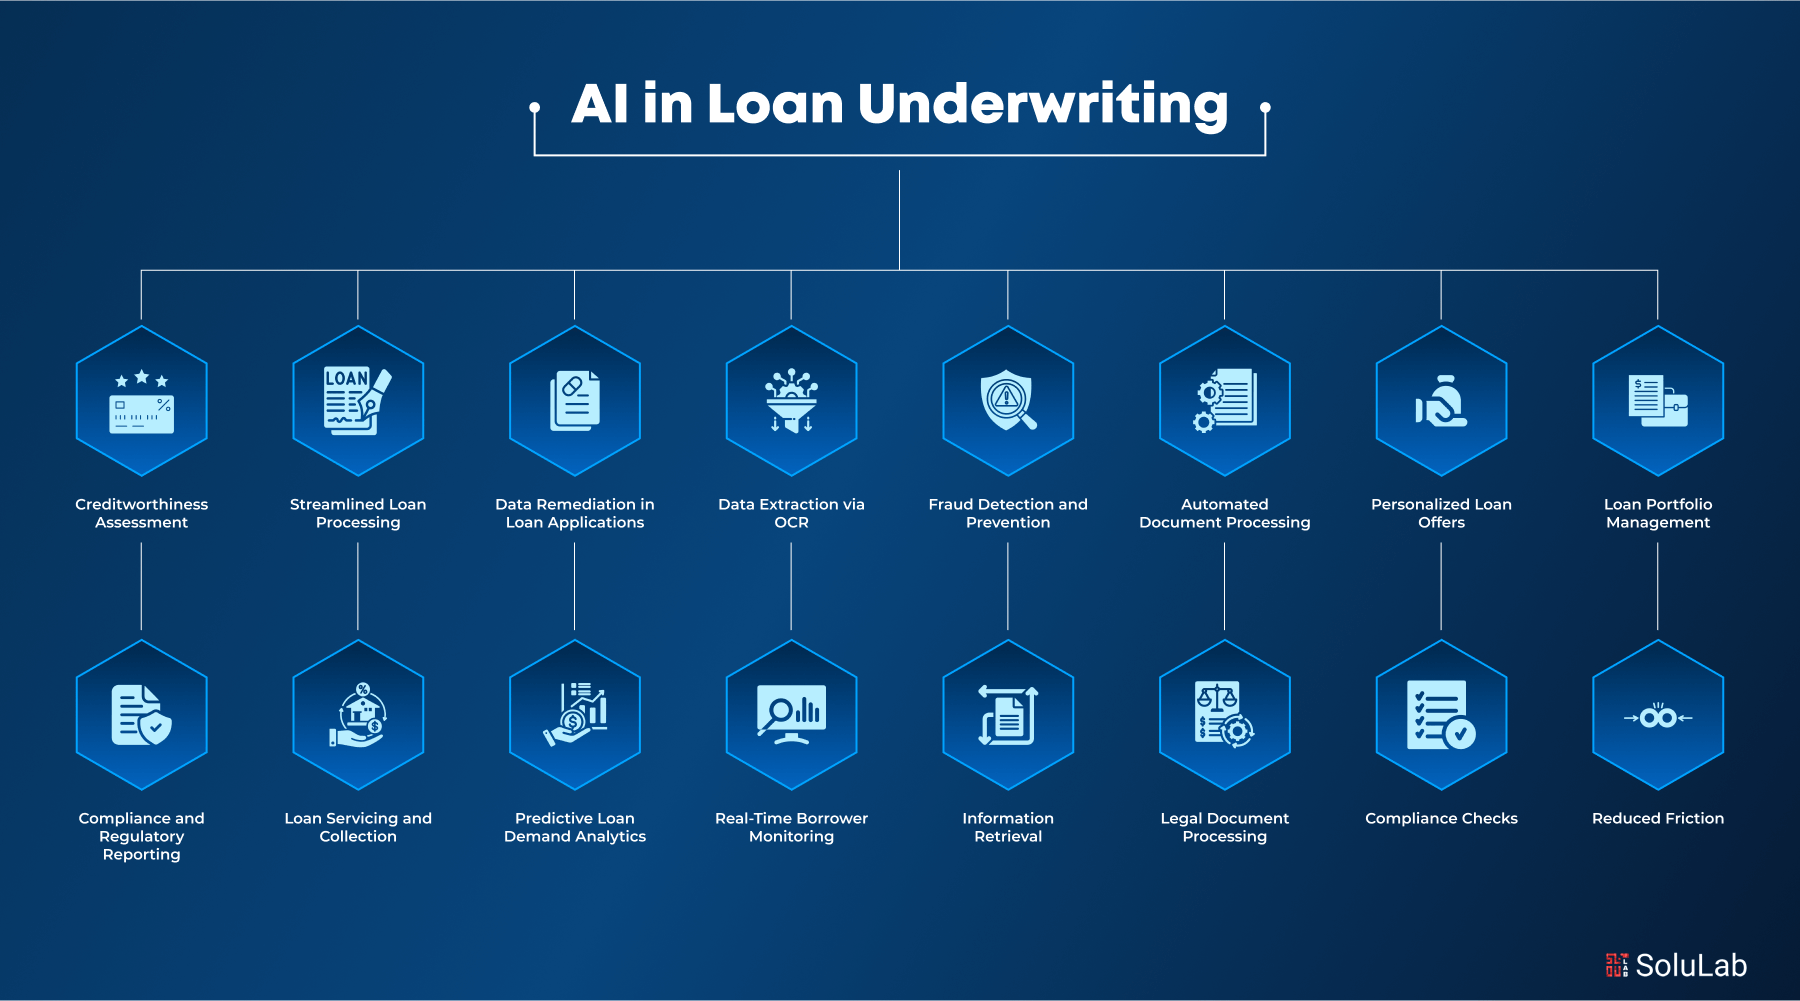
AI has left a mark on many industries. In loan underwriting, the impact is direct and measurable. Here are the key use cases of AI in loan underwriting, showing where AI does real work:
1. Creditworthiness Assessment
- Enhanced credit scoring: AI systems evaluate a wider range of data points, including credit history, transaction details, and even social media activity, producing credit scores that are more grounded in actual behavior.
- Predictive risk models: AI weighs multiple factors at once, giving lenders a more complete picture before they decide.
2. Summarization and Classification
- Document summarization: AI condenses lengthy documents quickly, pulling out what matters without the reviewer having to read every page.
- Business document classification: AI sorts and classifies business documents, making the organization and processing of files far faster.
3. Filling Information Gaps
- Form completion: AI handles the tedious work of completing forms and checks that the data entered is correct.
- Data enrichment: AI fills gaps by cross-referencing external data sources, building a more complete picture of the borrower.
- Automated data validation: AI checks data against historical trends, catching inconsistencies that a tired human reviewer might miss.
4. Elevating Customer Experience
- Personalized financial advice: AI reads transaction data and uses it to offer tailored financial guidance, whether that is around savings strategies or major purchase decisions.
- Exclusive offers: AI surfaces relevant offers to specific customers, improving the experience through conversational AI engagement.
5. Streamlined Loan Processing
- Automated decision making: AI handles up to 95% of manual underwriting decisions for SME lending. That frees human reviewers for the edge cases that actually need judgment.
- Data aggregation: AI tools pull and process large datasets from multiple sources rapidly, producing risk assessments that would take a human team days to compile.
6. Data Remediation in Loan Applications
- Improved data quality: AI identifies and corrects data quality issues, so the personal and financial information going into a decision is actually accurate.
- Efficiency gains: Machine learning models integrated with AI speed up the remediation process and reduce the backlogs that typically pile up in high-volume operations.
7. Data Extraction via OCR in Loan Underwriting
- Efficient data extraction: AI-powered OCR pulls text from physical documents and converts it into formats the underwriting system can actually use.
- Enhanced decision making: AI-enabled OCR captures extra data points from financial records, broadening the view of an applicant’s financial situation.
8. Loan Underwriting with Behavioral Analytics
- Transactional insights: AI categorizes transactions and builds simplified financial statements, delivering real-time visibility into how a borrower actually manages money.
- Customer experience: Behavioral analytics improves how institutions interact with customers, enriching NLP applications across financial data processing.
9. Fraud Detection and Prevention
- Anomaly detection: AI spots irregular patterns in loan applications that suggest something is off.
- Real-time monitoring: AI watches transactions continuously, catching and stopping fraudulent activity as it happens.
10. Automated Document Processing
- Optical Character Recognition (OCR): AI pulls the necessary information from documents like tax returns and pay stubs without a human having to key it in manually.
- Data verification: AI cross-checks provided information against external sources, so what enters the system is what it claims to be.
11. Personalized Loan Offers
- Tailored recommendations: AI matches loan offers to a customer’s actual financial history and current needs, rather than pushing a one-size-fits-all product.
- Dynamic interest rates: AI adjusts rates in real time based on risk assessments, which is a lot fairer than applying a fixed rate to everyone in a bracket.
12. Loan Portfolio Management
- Portfolio analysis: AI scans loan portfolios for high-risk positions and flags them before they become problems.
- Predictive analytics: AI forecasts borrower behavior and future trends, shaping portfolio management through Hybrid AI techniques.
13. Customer Service and Support
- AI chatbots: AI-driven chatbots handle borrower inquiries, loan status updates, and application questions without routing every request to a human agent.
- Virtual assistants: AI virtual assistants guide users through the loan application, offering a less frustrating experience at each step.
14. Compliance and Regulatory Reporting
- Automated compliance checks: AI runs loan applications through compliance checks automatically, catching issues before they escalate.
- Regulatory reporting: AI builds regulatory reports by organizing the required data accurately, saving teams a significant amount of manual preparation work.
15. Loan Servicing and Collection
- Proactive customer engagement: AI identifies borrowers showing early signs of financial stress and offers personalized repayment options before a default occurs.
- Automated collection: AI determines the best approach for reaching delinquent borrowers and recommends collection strategies accordingly.
16. Predictive Loan Demand Analytics
- Forecasting loan demand: AI reads trends and customer behavior to anticipate where demand will be, giving lenders time to position their products accordingly.
- Customer segmentation: AI groups borrowers by behavior and patterns, making targeted outreach far more precise than broad demographic buckets.
17. Sentiment Analysis
- Customer feedback analysis: AI reads borrower feedback from surveys and social media, surfacing patterns that inform service improvements.
- Market sentiment: AI tracks broader market mood, feeding that signal into risk assessment and decision-making.
18. Real-Time Borrower Monitoring
- Ongoing assessment: AI watches borrowers’ financial health continuously, alerting lenders when something starts to look risky.
- Dynamic adjustments: AI updates loan terms based on real-time data, so both parties are working from current information, not stale snapshots.
19. Portfolio Diversification Strategies
- Risk diversification: AI finds opportunities to spread risk across sectors, geographies, and borrower types, which reduces concentration risk.
- Optimal allocation: AI produces insights for adaptive AI solutions to optimize how capital is deployed and how risk is managed across the book.
20. Information Retrieval
- Data extraction: AI pulls relevant information from unstructured data, which is where a surprising amount of useful borrower context lives.
- Contextual understanding: AI does not just extract text; it reads context, which means the information it surfaces is actually meaningful rather than literally accurate but useless.
21. Legal Document Processing in Loan Underwriting
- Information gathering: AI organizes and summarizes legal documents like loan agreements, making compliance review faster without sacrificing thoroughness.
- Automated contract review: AI tools work through loan contracts, identifying risks and checking regulatory adherence so legal teams can focus on the exceptions.
22. Compliance Checks
- Automated compliance: AI runs checklist verifications and watches for regulatory changes in real time, so the team is not caught off guard by an update.
- Error detection: AI flags potential compliance problems in underwriting documents and processes before they become audit findings.
23. Training and Double-Checking
- Training simulations: AI builds simulated underwriting scenarios for practice, giving new underwriters realistic cases to work through without any real money on the line.
- Error detection: AI double-checks underwriting decisions, providing a second pass that reduces the human error rate.
24. Reduced Friction in Commercial Underwriting
- Streamlined processes: AI optimizes asset scheduling in commercial underwriting, cutting out the inefficiencies that slow deals down.
- Automated risk assessment: AI assesses risks quickly, reducing how much manual intervention the process requires.
Taken together, these cases show how Data Annotation and AI in loan under writing improve accuracy, speed, and the quality of decisions across the process.
Related:AI for Insurance Underwriting
Process of Loan Underwriting
The loan underwriting process is a series of steps where a lender evaluates an applicant’s creditworthiness and risk profile before approving a loan. Modern AI tools have changed how most of these steps work. Here is what the process looks like in practice:
1. Application Submission: The borrower applies and provides financial details, income, debts, and assets. Loan underwriting AI collects and validates this data automatically, cutting down how much manual input is required from the start.
2. Credit Evaluation: Lenders look at credit history, income, and debt obligations to judge repayment ability. AI-powered models go beyond traditional credit scoring by pulling in a wider range of data points and running predictive models that produce sharper assessments.
3. Risk Assessment: The lender works out how likely the applicant is to default. This is where Loan underwriting AI does some of its best work: analyzing large datasets and running machine learning algorithms to build a more detailed risk profile than any manual review could produce.
4. Verification of Information: Employment status, income, and assets all need to be verified. AI-driven systems cross-reference this data against external databases, cutting the time spent on manual checks significantly.
5. Approval or Rejection: Based on the credit evaluation and risk profile, the underwriter approves or rejects the application. Loan underwriting AI handles the straightforward cases automatically, freeing up underwriters to focus their attention on the applications that genuinely need a human eye.
6. Loan Offer & Terms: Approved applications get a loan offer with the interest rate, repayment schedule, and other conditions. AI models adjust interest rates dynamically based on real-time risk data, so the terms reflect the actual risk, not a broad category.
Bringing AI into the loan underwriting process means faster decisions, fewer errors, and a materially better experience for borrowers at each stage.
The Operational Benefits of AI in Loan Underwriting
Bringing artificial intelligence into underwriting changes the economics of lending. Here is where the gains actually show up:
1. Increased Efficiency and Speed: AI takes over the time-consuming work in underwriting, which means decisions move faster. Borrowers hear back sooner. The whole workflow gets leaner.
2. Enhanced Accuracy and Risk Assessment: AI-powered systems scan large datasets for patterns and risk signals, producing creditworthiness predictions that are more reliable than what a human reviewer working from a standard checklist can do. Fewer bad loans get approved.
3. Personalized Decision-making: AI lets lenders tailor terms, interest rates, and conditions to individual borrower profiles rather than forcing every applicant into a fixed bracket. This matters more than it sounds; borrowers notice.
4. Cost Reduction: Automating manual tasks through technologies like Robotic Process Automation (RPA) cuts operational costs. The savings are not marginal. When you take repetitive human labor out of a high-volume process, the numbers shift fast.
5. Enhanced fraud detection: AI runs sophisticated anomaly detection across loan applications, flagging patterns that suggest fraud. Human reviewers miss things, especially at scale. AI does not get tired.
6. Streamlined document processing: AI technologies like Natural Language Processing (NLP) and Computer Vision work through unstructured data in loan applications far faster than any manual process. Documents that used to take hours to process get handled in minutes.
7. Increased Objectivity and Consistency: AI applies the same rules to every application. There is no unconscious bias, no bad day, no inconsistency between reviewers. That consistency is good for borrowers and reduces fair-lending risk for lenders.
8. Scalability: AI-driven underwriting handles growing application volumes without needing proportional headcount increases. For lenders with expanding portfolios, that is a significant operational advantage.
9. Data-driven Insights: AI surfaces patterns and trends that would be invisible at the individual case level. Lenders can use those insights to refine their underwriting criteria over time.
10. Adaptability to Dynamic Conditions: AI adjusts in real time to shifting economic conditions, keeping underwriting models current. Retrieval Augmented Generation (RAG) means the system keeps learning as conditions change, not just when someone schedules a manual update.
11. Improved Customer Experience: Faster processing and offers that actually fit a borrower’s situation build trust. Borrowers who feel treated fairly and heard back from quickly do not go looking for another lender.
12. Regulatory Compliance: AI systems can be built to apply regulatory requirements automatically, reducing the chance of human error in compliance checks. Automated processes also adapt faster when regulations change.
The case for bringing AI into underwriting is not just about speed. It addresses the specific weaknesses of the traditional model: subjectivity, inconsistency, cost, and the inability to process the full picture of a borrower’s financial life.
The Future of AI in Loan Underwriting
The direction AI loan underwriting is heading is clear, even if the timeline is not. Several factors will shape how this plays out:
1. Expanded Use of Alternative Data: Financial institutions are moving beyond standard credit scores. Social media activity, online behavior patterns, and other non-conventional signals are being added to the picture. The idea is to get a fuller read on a borrower’s actual financial habits, not just their borrowing history.
2. Ongoing Regulatory Adaptation: Regulatory frameworks are still catching up to AI in loan underwriting. Governments and regulators are working to draw lines between the efficiency gains AI offers and the consumer protections that cannot be traded away. That work is not finished.
3. Greater Emphasis on Education and Awareness: As more lending decisions get made or shaped by AI, borrowers will want to understand how that works. Institutions that communicate clearly about their AI use will earn more trust than those that treat it as a black box.
4. Innovations in Explainable AI: Progress in explainable AI is making it easier to understand what complex models are actually doing. This matters for regulators, for borrowers who want to know why they were declined, and for institutions trying to prove their models are fair.
5. Cross-industry Collaboration: Financial institutions, technology companies, and regulatory bodies are increasingly working together rather than in parallel. Sharing what works and what does not across the industry will lead to better AI implementations and fewer costly mistakes in AI loan underwriting.
The future of AI loan underwriting will be built on better data, more transparent models, and a clearer understanding of where automation should defer to human judgment. The institutions that get that balance right will have a real advantage.
How Can SoluLab Assist with AI in Loan Underwriting?
SoluLab builds AI-powered solutions that change how loan underwriting actually works. Our team uses technologies like Robotic Process Automation and Retrieval Augmented Generation to automate manual tasks, sharpen decision-making, and improve how risk gets assessed. The result is a faster, more accurate process that gives your clients a better experience and keeps your institution competitive.
When you hire AI developers from SoluLab, you get AI solutions built around your specific requirements, not a generic product with your logo on it. Whether you need AI models for credit risk or document processing through natural language processing, our team handles the full build. We have delivered advanced AI systems for financial institutions and we know where the hard problems live. Contact us to find out how we can integrate AI into your underwriting operations.
FAQs
1. How does AI improve the loan underwriting process?
AI automates the work that slows underwriting down: document processing, risk assessment, and data analysis. With AI analyzing large datasets in real time, lenders make faster decisions with better information behind them. Approvals speed up, operational costs drop, and creditworthiness assessments become more accurate because the models can weigh a wider range of risk factors than a manual review can.
2. What are the benefits of using AI for risk assessment in loan underwriting?
AI risk assessment models work through vast amounts of data, including non-traditional financial signals, to predict default likelihood more accurately than conventional methods. Human error goes down. The decisions that come out are grounded in comprehensive data rather than a reviewer’s judgment on a given afternoon. Portfolio management improves as a result.
3. How can AI help financial institutions remain compliant with regulations?
AI systems can be built to run compliance checks automatically, confirm all required documentation is present, and reduce the chance of human error in the process. When regulations change, AI monitors those updates in real time, so the institution adapts without requiring a manual review cycle every time a rule shifts.
4. What role does AI play in fraud detection during loan underwriting?
AI watches for patterns and anomalies across loan applications that point toward fraudulent activity. It does this continuously, not just at the point of application. That means suspicious behavior gets flagged early, before money changes hands, making the lending environment safer for both sides of the transaction.
5. How can SoluLab help integrate AI into my loan underwriting system?
SoluLab builds AI solutions fit to your loan underwriting requirements. Our team handles automation, risk assessment models, and end-to-end efficiency improvements in your lending process. Partnering with us gives you access to AI technologies that cut costs, reduce errors, and improve the borrower experience. Contact us to learn more about our AI development services.
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.