

Ask anyone who has waited three days for a wire to clear. Banks still run on settlement cycles, liquidity gaps, and back-office costs that feel oddly old for an industry this rich, and both the institutions and their customers pay for it.
Now picture the opposite: trades that settle in seconds, assets you can actually sell when you want to, and records nobody can quietly edit. That is the promise of tokenization in banking in a single sentence.
The mechanics are simpler than the jargon suggests. A bank takes a real-world asset, say a bond, a building, or a book of credit, and represents it as a digital token on a blockchain. Once that happens, cross-border payments get cheaper, asset management gets cleaner, and markets that used to be locked up start to move.
Below, we walk through how RWA tokenization is reshaping the old banking model, and why we think it is one of the more serious routes to a financial system that is faster, easier to audit, and open to more people.
Why RWA Tokenization Matters for Banks in 2026 and Beyond?
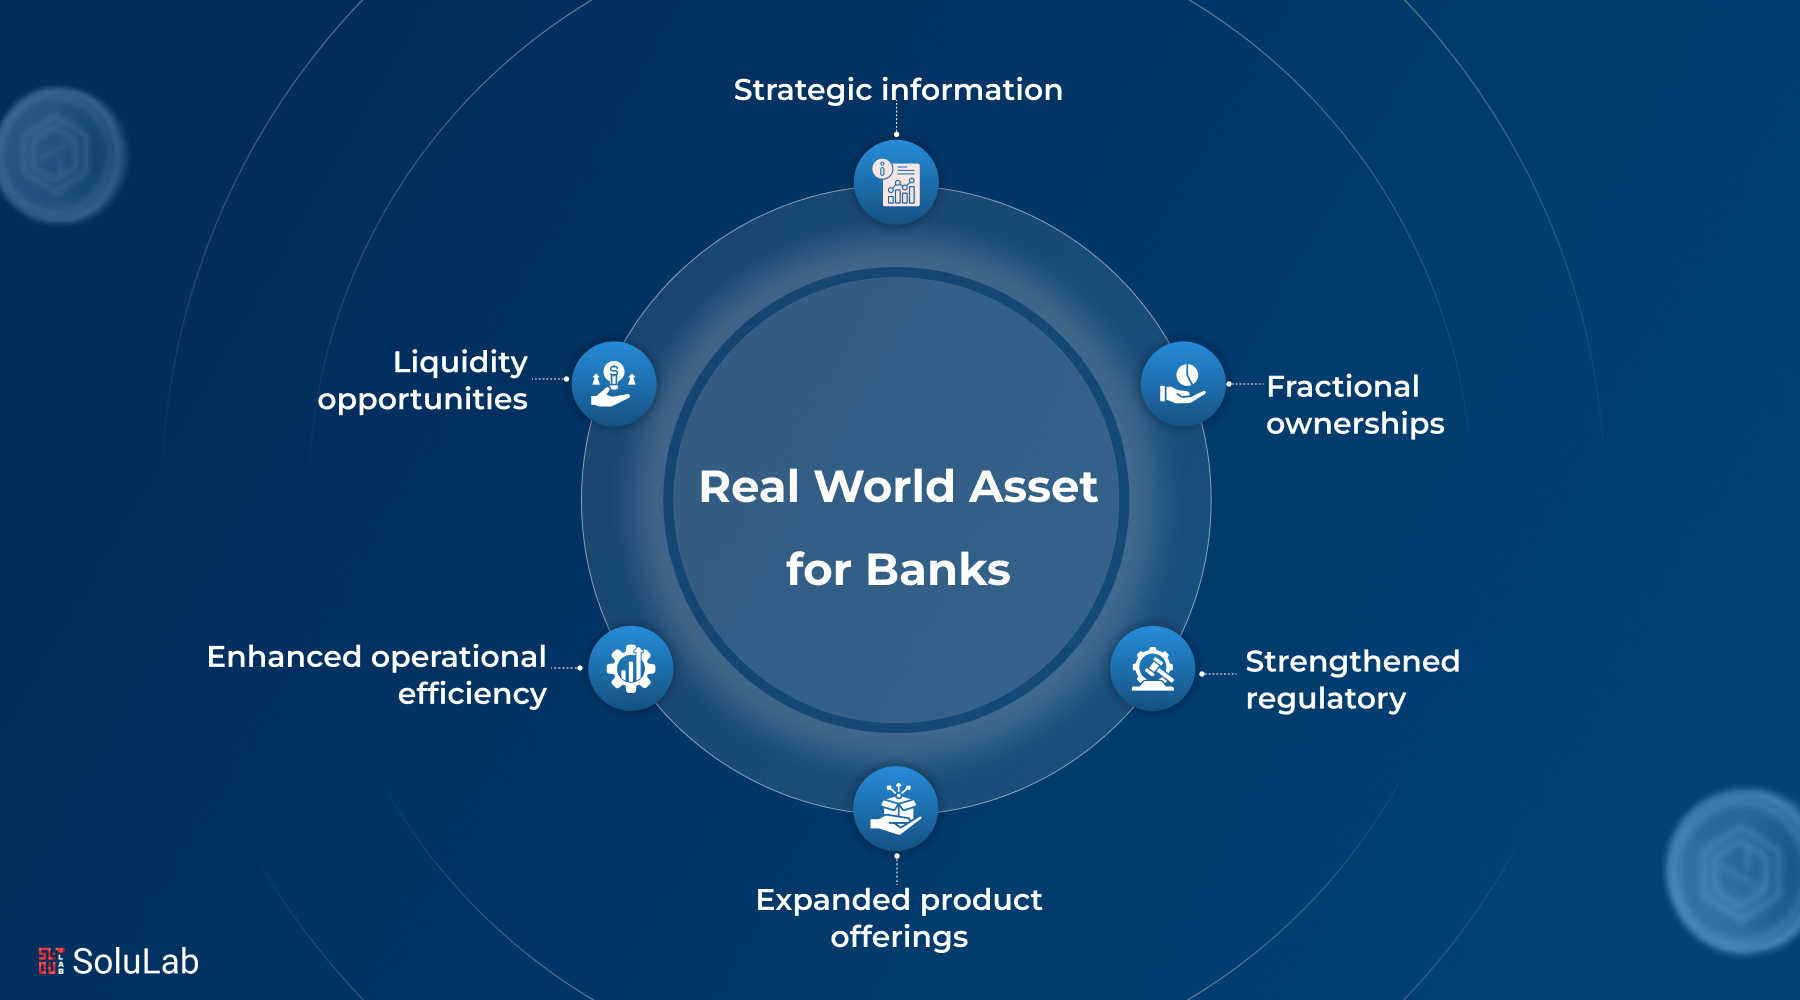
Short answer: banks can no longer treat RWA tokenization as a side experiment. It changes how assets get managed, traded, and turned into revenue, and the list below is why.
- Liquidity Opportunities: Tokenizing real-world assets lets a bank take something that normally sits for years, like real estate or a private equity stake, and cut it into tokens people can trade. More buyers can get in, and capital moves a lot quicker.
- Improves Asset Tracking: Every transfer lands on the chain, so you can trace and verify it later. That means more trust, less room for fraud, and far fewer headaches when the compliance team asks for a report.
- Enables Fractional Ownership: A client who could never write a cheque for a whole office tower can own a slice of one. For wealth desks, that widens the pool of clients they can serve without watering down returns.
- Enhances Operational Efficiency: Smart contracts take over the manual grind of settlement and compliance checks. Costs drop. Time drops. Errors drop too.
- Expands Product Offerings and Innovation: Tokenized bonds and token-backed loans are genuinely new products, and they speak to a younger, more digital investor who expects to hold assets in a wallet.
- Strengthens Regulatory Readiness: Regulators are writing digital asset rules right now. Banks that already run tokenized products will have far less catching up to do when those rules land.
The RWA Tokenization Lifecycle in Banking
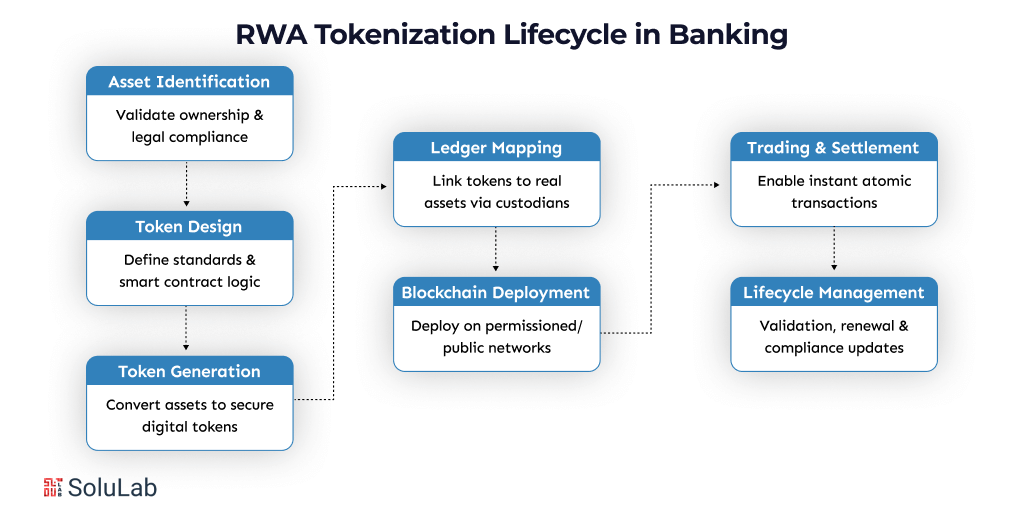
Tokenizing real-world assets (RWAs) changes how a bank manages, trades, and protects both physical and financial holdings. It is not one step, though. It is a chain of them, from picking the asset to looking after the token years later, and a weak link anywhere undermines the transparency and compliance the whole thing is supposed to deliver.
1. Asset Identification and Due Diligence
Everything in the RWA tokenization lifecycle rests on this step. The bank picks candidate assets, real estate, bonds, invoices, and runs them through legal, financial, and compliance checks. Who really owns it? What is it worth? What could go wrong? Only assets that survive those questions go on to become tokens.
Read Our Blog Post: RWA Tokenization for Invoice Financing
2. Token Design and Framework Definition
Next comes the design question: what will this asset look like on-chain? Fungible or non-fungible. Divisible or whole. Teams also map the regulations that apply, choose the smart contract protocols, and write the governance rules for how the token behaves on every platform it touches. In practice, this is where most of the arguments between legal and engineering happen.
3. Token Generation
With the framework agreed, minting starts. Smart contracts go live and issue tokens that stand for ownership of, or rights to, the underlying asset. Each one carries the asset’s metadata: legal ownership, valuation, and any limits on use. That baked-in data is what makes the token traceable and hard to tamper with.
4. Ledger Mapping and Custodianship
The tokens get recorded on a distributed ledger. At the same time, the physical asset, or its legal paperwork, goes to a custodian or another regulated party. Why both? Because a token is only as good as the thing behind it, and this split keeps the digital claim tied firmly to something real and accountable.
5. Deployment and Interoperability
Depending on the use case, tokens launch on a public chain or a private one. Either way, they need to talk to other platforms, or liquidity and scale stall. APIs and blockchain bridges usually do that job, letting tokens move safely between DeFi applications, wallets, and marketplaces.
6. Trading, Settlements, and Secondary Markets
Now the asset can trade, on licensed exchanges or DeFi platforms. Settlement shrinks to near-instant blockchain confirmation. And once tokens circulate in secondary markets, liquidity improves, pricing is visible to everyone, and investors with modest capital finally get a seat at the table.
7. Token Renewal and Lifecycle Management
Issuing the token is not the finish line. Valuations need refreshing, audits keep coming, and the contracts need upkeep so everything stays compliant. When an asset matures, gets caught in a legal dispute, or goes through a corporate action, the token may have to be renewed, changed, or burned outright. Skip this work and trust erodes fast.
Use Cases of RWA Tokenization in Banking
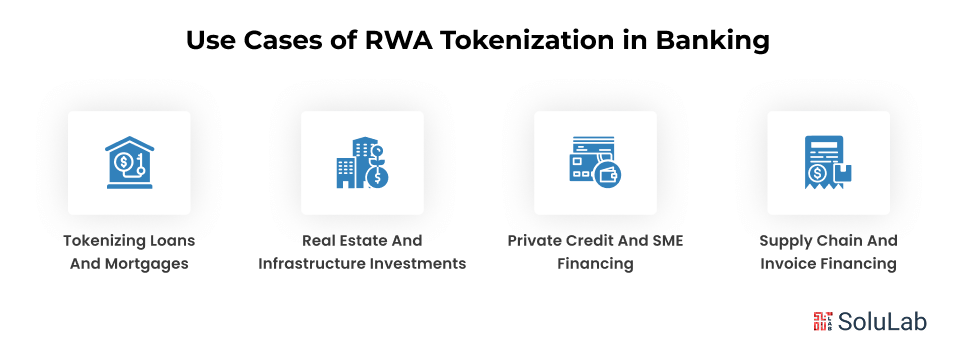
So where does this show up in day-to-day banking? Mostly in places where money is stuck in conventional assets and banks want it moving faster, cheaper, and more securely.
- Tokenizing Loans and Mortgages: A home loan or business mortgage can become a set of digital tokens. That opens the door to fractional ownership, simpler transfers, and better liquidity, with less paperwork and shorter settlement times along the way.
- Real Estate and Infrastructure Investments: When banks go about tokenizing large real estate or infrastructure projects, investors can buy a fraction instead of the whole. More people can participate, and new capital has a way in.
- Private Credit and SME Financing: Put private debt or SME loans on-chain and a bank can offer more flexible financing while spreading risk across more holders. It also pulls in investors hunting for higher yields in underbanked sectors.
- Supply Chain and Invoice Financing: Invoices and receivables turn into assets someone can buy. The business gets working capital sooner, and the supply chain gets a clearer paper trail that is much harder to fake.
Read More: RWA Tokenization Challenges: How a Development Partner Helps
Real-World Examples of Banks Using RWA Tokenization
This is not a whiteboard idea anymore. RWA (Real-World Asset) tokenization is already changing how global banks work, and names like JPMorgan, HSBC, and Societe Generale are out in front, putting traditional assets on blockchain rails. Here is what each of them has actually done:
1. JPMorgan’s Kinexys Platform
JPMorgan built the Kinexys platform to tokenize assets such as U.S. Treasury bonds and money market shares. Kinexys is also home to JPM Coin, which lets institutions settle instantly and pay each other around the clock. The result is less counterparty risk, quicker settlement, and a clearer view of what is happening, which is exactly what legacy banking has always lacked.
2. HSBC’s Digital Bond Issuance
HSBC issued a $100 million digital bond on a blockchain platform, a clear signal that tokenization can drag traditional securities into the present. Settlement happened in real time. Fewer intermediaries sat in the middle. Liquidity improved. It also points toward bond trading that costs less and could one day let smaller investors own a fraction of an issue.
3. Societe Generale’s Blockchain-Based Assets
Societe Generale turned to Ethereum to tokenize €100 million worth of covered bonds and structured products, using the exercise to test whether issuance and settlement could stay within European regulations. What stands out is the choice of a public chain. It hints at a future where banks can audit each other’s records openly and their systems actually connect.
Conclusion
Tokenizing bank assets makes the financial system quicker, safer, and more open. Turn a physical asset into a digital token and you can reach investors in other countries, trim operating costs, and settle in a fraction of the usual time.
None of this is hypothetical. Large institutions are already running it. And as adoption grows, the banking industry’s use of asset tokenization will change how organizations hold value and hand it out.
Bonds, real estate, credit: across product lines, tokenization brings speed and wider access to the core of banking, and it gives product teams room to try things the old rails never allowed.
SoluLab, a RWA tokenization development company, helps banks build secure, compliant platforms for real-world asset tokenization in banking that can grow with demand. Contact us today to talk it through.
FAQs
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.