Key Takeaways
- Old-school real estate is a liquidity trap. Your money sits locked for years, roughly 10% of your equity vanishes into transaction costs, and splitting ownership between people is a legal headache.
- Tokenization turns a static deed into a programmable SPL or ERC-20 token. That means you can trade on a secondary market almost instantly, run the SPV on autopilot, and pay out yield every day.
- Owners get their capital moving again. Investors get a way out, any hour of the day, through regulated secondary markets.
Real estate is the biggest asset class on the planet. It is also one of the slowest. For decades, something like $29 trillion has been stuck behind paper trails and banking cycles that drag on for weeks. That kind of friction was always going to break eventually.
- After the U.S. GENIUS Act and Europe’s MiCA came into force, tokenization became the default way institutions syndicate property.
- Move property titles onto a distributed ledger and the math shifts hard. Transaction costs that used to run around 7% drop below 1%. Call it “Instant Real Estate,” because that is roughly what it feels like.
Blockchain-based tokenization is what changes the underlying structure. Once property rights become programmable tokens, a building can trade about as smoothly as a digital security. That is the whole idea.
Why Is Real Estate Tokenization the Preferred Liquidity Strategy for Developers in 2026?
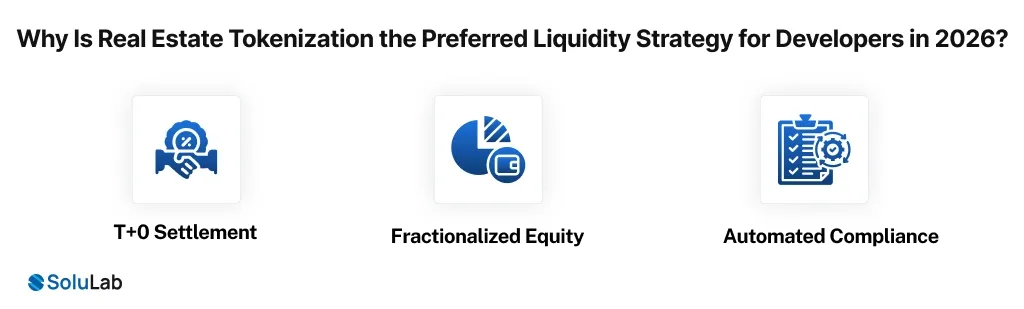
Developers do not tokenize because it is new technology. They do it for one reason: capital velocity.
- Capital velocity is just how fast your money can hop between investments while still earning along the way.
- Traditional real estate throttles that movement. Long settlement cycles and illiquid ownership see to it.
Tokenized infrastructure loosens that grip in a few concrete ways, and once you see how each piece fits together, the appeal to developers stops being abstract and starts looking like a straightforward operational upgrade. Here is where.
1. T+0 Settlement
A normal property deal can take 30 to 60 days to close. Escrow, banks, legal checks. Everyone waits.
Tokenized real estate settles almost on the spot. Call it T+0. The moment the smart contract’s conditions are met, ownership moves on-chain. No queue.
2. Fractionalized Equity
The minimum buy-in drops sharply, to a point where the barrier that once kept ordinary savers out of institutional-grade property syndications basically stops existing.
You used to need $50,000 or more just to get into a property syndication. With tokenized platforms, an investor can start at $100.
Suddenly the door is open to retail and institutional money worldwide, drawing on the same global liquidity pool.
3. Automated Compliance
Newer token standards let you bake compliance straight into the asset.
The frameworks you would reach for:
- ERC-3643 on Ethereum
- Token Extensions on Solana
KYC and AML rules get hard-coded into the token itself. Investor not approved? The transaction just will not go through. There is nothing to override.
No more manual checks, and a lot less operational risk to worry about.
How Does the Tokenization Workflow Convert Physical Deeds into Digital Assets?
Building a real estate tokenization platform is not just minting tokens and calling it a day. You need a legal, technical, and regulatory architecture that ties a real building to blockchain infrastructure.
People call that connective tissue the legal-tech bridge.
1. Legal Layer: The SPV Structure
A physical building cannot live on a blockchain. So you wrap it in a Special Purpose Vehicle, or SPV.
- The SPV is usually an LLC set up somewhere like Wyoming, Delaware, or the British Virgin Islands.
- The property title moves into that SPV. The tokens then stand for membership shares in the entity.
- Buy tokens and you own a slice of the SPV, which owns the actual property.
Why bother with the layer? Because it makes the token stand for real, enforceable ownership, not just a picture of it.
2. Technical Layer: Smart Contract Infrastructure
The smart contract runs the money side of the tokenized property.
What it handles:
- Yield Distribution
Rent collected from tenants can be swapped into a stablecoin like USDC.
Smart contracts then split that income out to token holders, each getting a cut that matches their ownership share.
Tools like Chainlink Automation or Solana Clockwork can push those payouts daily or monthly, hands-off.
- Data Oracles
Outside data has to get in. Property valuations, market moves, that sort of thing has to reach the smart contract somehow.
Oracle networks like Chainlink and Pyth Network feed in verified off-chain data, so contracts can refresh valuations and financial metrics on their own.
3. Regulatory Layer: Security Token Compliance
Most tokenized real estate counts as a security token. That pulls it under financial regulation, like it or not.
The frameworks that tend to come up:
- Regulation D / Regulation S (United States) for accredited and international investors
- MiCA compliance (European Union) for digital asset offerings
- KYC / AML identity verification for investor onboarding
Any platform running these offerings has to operate as a Security Token Offering (STO) platform.
That is what keeps investors protected and the whole thing legally legitimate.
4. Solana vs Ethereum: Choosing Infrastructure for Tokenized Real Estate
Which chain you build on decides whether the platform actually makes money.
Fees that are too high, or settlement that is too slow, can wipe out the whole point of tokenizing in the first place.
Two chains dominate real estate tokenization right now.
| Metric | Ethereum | Solana |
| Transaction Cost | $15 to $50 | <$0.01 |
| Throughput | 15 to 30 TPS | 65,000+ TPS |
| Compliance Tools | ERC-3643 | Token Extensions |
| Settlement Finality | 1 to 15 minutes | ~400 milliseconds |
Ethereum still wins for institutional security token frameworks, especially when you are building regulated financial products around it.
But if your platform lives on high-frequency trading or daily payouts, Solana or Polygon usually makes more sense. The fees are tiny and the throughput is enormous.
Read Also: Top RWA Tokenization Questions Answered for Enterprises Ask in 2026
What Are the 3 Proven Revenue Models for Tokenized Real Estate Platforms?
The token sale is only the start. A tokenization platform can earn money in a few durable ways after that.
1. Asset Sourcing Fees
Platforms often take 1% to 3% of a property’s value for structuring and tokenizing it.
That fee pays for the legal setup, smart contract development, and onboarding.
2. Asset Management Fees
They can also charge an annual management fee, roughly 0.5% to 1% of Assets Under Management (AUM).
That covers coordinating property management, reporting back to investors, and keeping compliance in check.
3. Secondary Market Trading Fees
Every peer-to-peer trade can throw off a small spread or a trading commission.
Thin at first. But as liquidity builds, that trickle of trading turns into a real revenue line.
Tokenization brings a handful of advantages that can genuinely reshape how people invest in property.
Read Blog: Tokenization of Real Estate in Australia
Navigating Jurisdictional Restrictions: The 2026 Regulatory Landscape
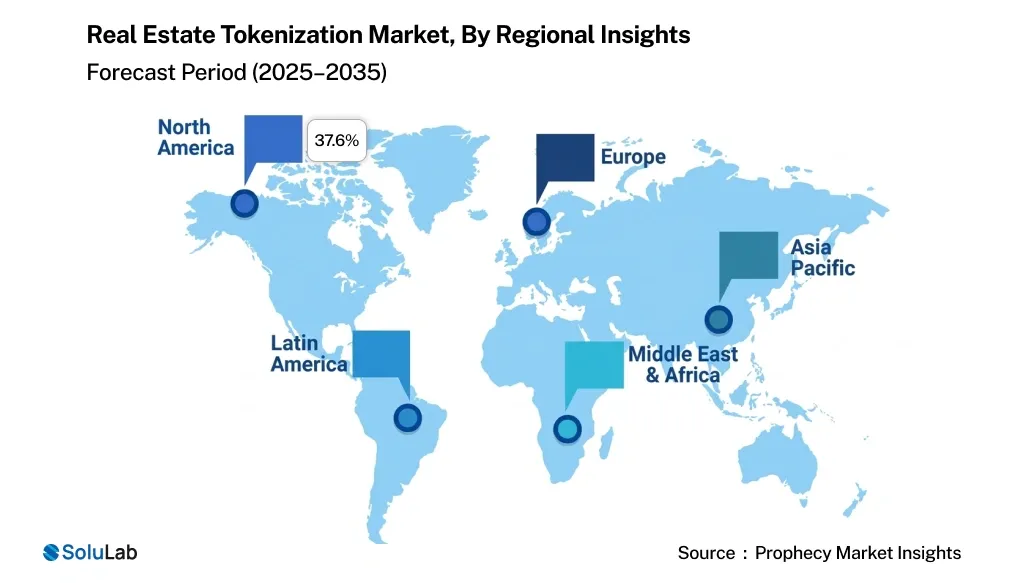
The liquidity story is global. The execution is stubbornly local. In 2026, what usually stops an investor is not the tech, it is the legal structure. Getting through that means treating compliance as code, not paperwork.
1. Real Estate Tokenization in the US: Reg D and Reg S Frameworks
The US is the biggest market for tokenized assets. It is also the most heavily policed.
The SEC treats tokenized real estate as a security. Full stop.
- Issuers usually lean on Regulation D (506c) for accredited domestic investors, or Regulation S for people abroad.
- The better platforms handle this on-chain. With “Transfer Hooks,” a token will only move between wallets that have already cleared KYC/AML.
- So secondary trading of US assets stays fully compliant with SEC lock-up periods and investor limits, and nobody has to police it by hand.
2. Real Estate Tokenization in the UAE: VARA and ADGM Standards
The UAE has become a serious hub for digital assets, mostly through the Virtual Assets Regulatory Authority (VARA) in Dubai and the ADGM (Abu Dhabi Global Market).
- The UAE wants rigorous “Proof of Reserve” and specific licensing before anyone offers fractional ownership to the public.
- To clear that bar, developers are leaning on Hybrid Smart Contracts.
- These tie the digital token back to the physical land registry in Dubai or Abu Dhabi through dedicated APIs.
- The result is a “Double-Verification” setup: the blockchain transaction and the government land record update at the same moment, which is exactly the transparency UAE regulators ask for.
3. Real Estate Tokenization in Australia: Navigating ASIC Compliance
Australia has seen a real jump in fractional ownership interest. But ASIC (Australian Securities and Investments Commission) keeps a tight grip on Managed Investment Schemes (MIS).
- Tokenizing an Australian property usually means the platform needs an Australian Financial Services License (AFSL), or a partnership with someone who holds one.
- The platforms that pull it off use Custodial Smart Wallets. With account abstraction, they can run the legal “Unit Trust” structure on-chain.
- Rental yields get distributed automatically, while the underlying title stays safe inside an Australian legal trust.
Technical Barriers: Solving the “Institutional Trust” Gap
The law is one thing. Then there are three technical problems that quietly stall big rollouts. Solve them, and you go from a pilot project to a market leader. Leave them, and you stay a demo.
1. The Data Integrity Challenge (The Oracle Problem)
A token is only as good as the data behind it. Property data tends to sit in silos, which leaves you with stale prices.
- The fix is Decentralized Oracle Networks (DONs).
- Pull live data from providers like ProspectNow or SmartZip, and a token’s Net Asset Value (NAV) tracks the real market as it moves.
- That kind of institutional-grade transparency is what earns investor trust when the market gets choppy.
2. The Wallet Recovery Crisis
Picture a fund manager losing a private key and, with it, a multi-million dollar deed. In a purely decentralized world, that is exactly what can happen. No fund manager will sign up for that.
- So the industry moved toward Social Recovery and Governance Overrides.
- Prove your identity through offline legal channels, and the platform can “burn” the lost tokens and reissue them.
- It marries blockchain’s immutability with the safety nets that traditional property law demands.
3. Large-Scale Interoperability
The global property market is worth north of $29 trillion. You do not move something that size without governments, banks, and blockchain protocols all pulling together.
- Cross-Chain Interoperability Protocols (CCIP) let tokens travel between tokenization on Ethereum, Solana, and private bank ledgers.
- That kills the “liquidity silos” and means an investor in London can trade a fractional share of a Sydney office tower as easily as buying a stock.
Conclusion
Turn ownership into blockchain tokens and property gets more liquid, easier to reach, and far more transparent for investors anywhere. That is the shift SoluLab helps teams make, through specialized real-estate tokenization development services like:
- Real Estate Tokenization Platform Development
- Security Token (STO) Development
- Smart Contract Development & Audits
- Tokenization on Solana, Ethereum, and Polygon
- SPV-Based Asset Tokenization Architecture
With those pieces in place, enterprises can stand up tokenized real estate platforms that actually scale, and open the door to investors around the world. Contact us today!
FAQs
Deepika is a content writer who blends storytelling with strategic thinking. She explores topics across digital innovation, emerging tech, and the evolving blockchain industry. She enjoys breaking down complex ideas into simple, engaging narratives in the growing global markets.