

Cross-border B2B payments are broken. They have been for decades. High fees, days-long delays, capital stuck in transit while your suppliers wait and your working capital evaporates. In 2026, that model is finally cracking under its own weight.
- Stablecoins now handle the core B2B infrastructure. They hold a 1:1 parity with fiat currencies, which means none of the volatility that makes standard crypto unworkable for invoicing.
- The numbers are hard to argue with: According to The World Economic Forum, stablecoin settlement volume hit $34 trillion in Q1 2026 alone, consistently outpacing Visa’s traditional network throughput.
- Regulatory clarity arrived too. The U.S. GENIUS Act and the EU’s MiCA framework have turned stablecoin platforms into a recognised category, now accounting for 85% of corporate crypto activity.
SAP has fully wired these digital rails into its ERP systems. That is not a pilot. That is a signal that adoption has crossed from experiment to standard operating practice.
Key Takeaways
- AI-powered stablecoin payment systems handle routing optimisation, fraud detection, and reconciliation automatically, letting enterprises scale cross-border volumes without adding headcount
- ERP integrations, open APIs, and smart contracts make programmable payments real: invoicing, settlements, and compliance checks run without manual intervention across global business operations
- Tokenised assets and multi-currency stablecoins give treasury teams actual tools for hedging volatility and managing liquidity across markets, not just theoretical options
How Stablecoins B2B Payments Help Liquidity in 2026?
Stablecoins stopped being the “alternative payments” option a while back. They are now the primary settlement layer for global trade. Unlike traditional SWIFT transfers, which trap capital in transit for days at a stretch, stablecoin-based B2B systems run continuously with no banking hours, no clearing windows, no waiting.
The Enterprise Advantage: Why CFOs are Migrating
- Atomic Settlement: Stablecoin transactions clear in under 3 minutes, around the clock, every day of the year. Settlement risk disappears. Capital that used to sit frozen waiting for bank clearing windows can be reallocated the moment a deal closes.
- Cost Compression: Traditional wire transfers route through 3 to 5 correspondent banks, each taking a cut. Stablecoins bypass that entirely, dropping all-in transaction costs from the 3% to 7% range down to 0.1% to 0.5%.
- Programmable Compliance: Smart contracts can hold a payment until verified delivery occurs (DvP logic), or release funds only when specific regulatory conditions are met. Trust gets encoded directly, not promised verbally.
- Treasury Optimisation: Enterprises use stablecoins to handle inter-company loans and global payroll without the 60% to 97% FX markups that traditional banking hides inside the rate spread.
The 2026 Taxonomy: Choosing the Right Asset for Your Stablecoin Platform Development
The type of stablecoin you choose determines your regulatory footprint and your operational flexibility. Pick wrong and you will spend months unwinding the mismatch.
1. Regulated Fiat-Backed Tokens (The Compliance Standard)
Think of these as digital dollars and digital euros, each backed 1:1 by high-quality liquid assets like U.S. Treasuries. They are the closest thing blockchain has to a plain bank deposit.
- Under the U.S. GENIUS Act and the EU’s MiCA, these tokens now qualify as regulated asset tokenisation and payment instruments. That regulatory recognition matters enormously for public companies.
- Best For: Official B2B invoicing, tax payments, and public company treasuries that need audit-ready transparency.
2. Tokenized Real-World Assets & Commodity-Backed Stablecoins
These represent ownership of physical assets: gold bullion, real estate, carbon credits. They carry intrinsic value that pure fiat-backed tokens do not.
- In 2026, businesses treat them as yield-bearing collateral. A company can hold gold-backed tokens like XAUT as an inflation hedge while simultaneously pledging them as collateral for low-interest working capital loans denominated in USDC.
- Best For: Inflation hedging, diversifying corporate reserves, and ESG-compliant carbon credit settlement.
3. Over-Collateralized & Decentralized Stablecoins
These work by locking other high-value digital assets (ETH, tokenised bonds) into smart contracts to back the peg. No central issuer. No corporate board making reserve decisions.
- Because code governs them rather than an institution, they offer 100% on-chain auditability. For businesses that need censorship resistance and fully trustless automation, this category is the only option that delivers both.
- Best For: DeFi-based yield farming, decentralised supply chain finance, and tech-forward startups that cannot afford counterparty risk on a central issuer.
4. Adaptive/Algorithmic Protocols (Supply-Elastic Assets)
Modern algorithmic models have moved well past the catastrophic pure-algo designs. The current generation uses AI-driven supply adjustments in hybrid configurations to hold the peg.
- Riskier than collateralised alternatives, but they offer a level of liquidity scalability the other categories cannot match, particularly for high-frequency micro-payments like pay-per-use AI API calls or IoT data streams.
- Best For: Automated machine-to-machine (M2M) payments and hyper-scale digital operations where traditional settlement models would create bottlenecks.
Read More: Dollar-to-Stablecoin Swaps In White-Label Neo Banking
Which are the Best Stablecoins for the B2B Market?
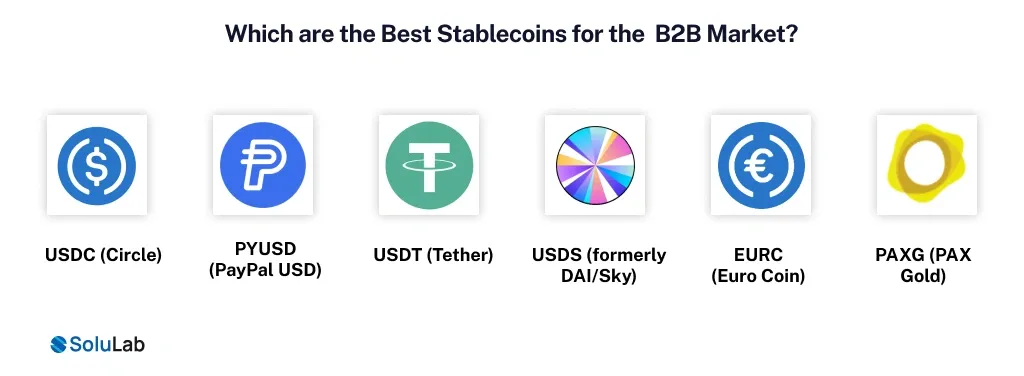
Picking a stablecoin platform model and type in 2026 is a treasury decision, not a tech one. It stopped being about which peg is most stable. The real question is: which asset fits your regulatory corridor, your settlement speed requirements, and the jurisdictions you actually operate in.
1. USDC (Circle)
USDC is the default choice for regulated enterprises. Its alignment with the U.S. GENIUS Act and its MiCA-compliant status in Europe mean public companies can hold it without triggering auditor questions about asset classification.
- Circle’s Cross-Chain Transfer Protocol (CCTP) lets businesses move liquidity across 15+ chains without bridging, which removes one of the biggest operational headaches in multi-chain treasury management.
- If your business needs audit-ready transparency and has banking relationships with US or EU institutions, USDC is not really optional. It is the path of least resistance through compliance.
2. PYUSD (PayPal USD)
As of March 2026, PYUSD operates in 70 global markets. It has done something the broader crypto industry spent years failing at: connecting blockchain settlement to mainstream business banking without forcing finance teams to learn new infrastructure.
- It is the only major stablecoin with native integration into both Stellar and Solana networks, which means sub-cent transaction costs at enterprise scale.
- For SMEs, PYUSD is the practical answer. Moving from a digital wallet to a merchant bank account in minutes makes it viable for day-to-day operations in a way that most crypto payment options are not.
3. USDT (Tether)
USDT does not have the cleanest regulatory profile. But in emerging markets across APAC, LATAM, and Africa, it is simply the most liquid option available. No alternative comes close on depth.
- Tether’s 2026 expansion into B2B commodity financing means companies can now use USDT for bulk trade settlements in regions where USD access is restricted through traditional banking channels.
- USDT is the only asset with enough market depth to absorb $100M+ instant settlements without meaningful slippage. That matters when you are moving serious volume.
4. USDS (formerly DAI/Sky)
The 2025 rebrand from MakerDAO to Sky converted DAI into USDS. It remains the first choice for businesses operating inside DeFi, where censorship resistance is not a preference but a requirement.
- The Sky Savings Rate (SSR) lets corporate treasuries earn a native yield of 4% to 6% on idle USDS reserves directly on-chain, with no intermediary bank needed.
- For tech-forward firms and DAOs, USDS provides a hedge that no traditional bank can freeze, while still delivering institutional-grade yield. That combination is genuinely rare.
5. EURC (Euro Coin)
MiCA came into full effect in 2026, and EURC is the direct beneficiary. It has become the primary tool for Euro-denominated B2B trade, cutting out the FX conversion step that adds cost and delay to every cross-border invoice between EU counterparties.
- It is now a core asset inside the SAP Digital Currency Hub, so European manufacturers can pay suppliers in digital Euros with immediate finality through systems they already use.
- Any business with significant EU operations should be running EURC for supplier payments. The SEPA Instant windows that EURC bypasses are slow and expensive by comparison.
6. PAXG (PAX Gold)
In a volatile macro environment, PAXG does something no other stablecoin can: it gives businesses exposure to physical, London-Good-Delivery gold in a form that settles on-chain in seconds.
- B2B lending platforms increasingly accept PAXG as high-quality collateral for low-interest stablecoin loans, which opens up working capital options that did not exist two years ago.
- PAXG is not a daily payments tool. It is a balance sheet decision: CFOs who want a portion of reserves in gold without sacrificing liquidity now have a way to do both.
Note:
As of early 2026, BUSD has been fully deprecated and replaced by USD1 and FDUSD within the Binance ecosystem. We no longer recommend BUSD for new enterprise integrations.
Read More: Stablecoin-as-a-Service
Benefits of Stablecoins for Businesses
The case for stablecoins in business is not theoretical anymore. Companies are choosing them because they fix actual problems with speed, cost, and access that blockchain technology makes tractable in ways traditional finance does not.
Here are the key benefits of stablecoins for businesses:
1. Cost Savings: Stablecoins run on decentralised blockchains, which means no correspondent banks, no currency conversion desks taking margin, and no compliance overhead baked into the fee. Moving funds from Southeast Asia to Europe costs 3 to 4 times less than SWIFT. Africa to Europe can run 5 to 10 times cheaper. Even when bridging through a third-party fiat ramp, the savings are real.
2. Improved Cash Flow: Slow settlement is a working capital problem dressed up as a payment problem. Traditional cross-border wires hold your money hostage while FX clears. Stablecoins run 24 hours a day, seven days a week, with near-instant finality. You get the capital when you need it, not when the banking system gets around to releasing it.
3. Market Accessibility: In markets where banking infrastructure is thin or standard financial services are out of reach, stablecoins create a workable alternative. Businesses selling into emerging markets gain a payment channel that actually functions. Local buyers get access to goods and services they could not reach before. That is growth through inclusion, not growth through workarounds.
4. Smart Contract Integration: Stablecoins connect directly to smart contracts, which handle payment terms programmatically rather than through manual approval chains. Settlement processes that used to require back-and-forth between finance teams can run automatically, with fewer errors and lower administrative overhead. The payment happens when the conditions are met, not when someone remembers to process the invoice.
5. Balance Sheet Diversification: In markets hit by inflation or where local currency access to USD is restricted, holding stablecoins gives businesses a reliable store of value outside the local system. It is not about speculation. It is about having a portion of the balance sheet that holds its value when the local currency does not.
Taken together: lower costs, better liquidity, wider market reach, and programmable settlement. That combination is why adoption keeps accelerating.
Read More: Stablecoin-Linked Payment Cards For Fintech
How to Implement Stablecoin Payments for Your Business?
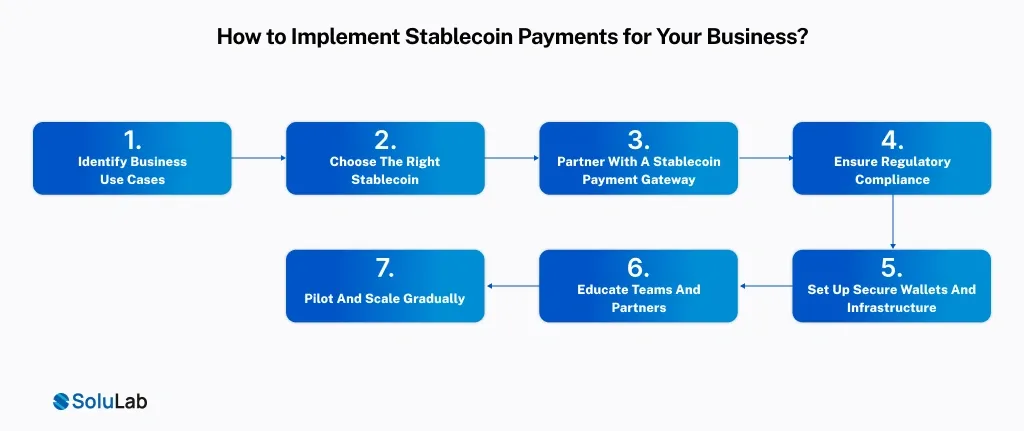
Moving to stablecoin-based payments is not a weekend project. The speed and cost advantages are real, but so is the complexity of integrating blockchain settlement into existing financial operations. A structured approach reduces the risk of getting halfway there and stalling.
1. Identify Business Use Cases
Before anything else, get specific about where stablecoins actually solve a problem for your business. Cross-border payments? Supplier settlements? Employee payouts in markets with volatile currencies? Inflation hedging in reserves? Identifying the concrete use case first prevents the common mistake of adopting the technology before knowing what you are adopting it for.
2. Choose the Right Stablecoin
The selection criteria that actually matter:
- Collateral type and stability model (fiat-backed, crypto-backed, or commodity-backed).
- Regulatory standing in the jurisdictions you operate in.
- Reserve transparency and audit history.
USDC, USDT, and DAI (now USDS) are the most widely adopted in stablecoin-based B2B payment systems because liquidity and reliability tend to compound over time.
3. Partner with a Stablecoin Payment Gateway
You need a gateway layer to connect blockchain settlement to your existing financial systems. Payment gateways handle the wallet infrastructure and the integration work, so your finance team is not building blockchain tooling from scratch. Circle, Binance Pay, and BitPay each offer B2B-focused solutions worth evaluating against your use case.
4. Ensure Regulatory Compliance
Stablecoin regulations differ by jurisdiction, and the gap between markets is wide. AML, KYC, and tax requirements all apply, and getting them wrong is expensive. Bring in legal and compliance before you start building, not after you have shipped something and need to retrofit controls.
5. Set Up Secure Wallets and Infrastructure
Custodial wallets (managed by a third party) are easier to start with. Non-custodial wallets give you more control but require more operational discipline. Whichever you choose, multi-signature authentication and proper encryption are not optional. This is where teams get stuck: underestimating the security requirements until something goes wrong.
6. Educate Teams and Partners
Finance teams that do not understand how stablecoin settlement works will make avoidable errors. The same goes for counterparties. Train both before you go live, not during your first real transaction.
7. Pilot and Scale Gradually
Run a small, bounded pilot first. Pick one corridor, one counterparty, one use case. Measure performance, security, and cost against your baseline. Once you have real numbers, scaling is straightforward. Skipping the pilot to move faster is the move that creates months of rework later.
Done right, this progression integrates stablecoin development into your financial operations without the disruption that comes from rushing. The efficiency gains are real, and so is the blockchain-based infrastructure that makes them possible.
Conclusion
The window for treating stablecoins as a future consideration has closed. Faster settlement, meaningfully lower transaction costs, and payment access in markets that traditional banking cannot reach: these are live advantages, available now, to businesses that move.
Crypto Mining partnered with SoluLab to build a decentralised e-commerce platform for mining hardware.
- Key features included a mining pool, an advanced mining farm, a profitability calculator, real-time monitoring, and enhanced security measures.
- The result was a user-friendly, scalable solution giving global miners direct access to authentic mining devices and hosting services.
If you are ready to bring stablecoin payments into your B2B operations, SoluLab, a Stablecoin development company, builds the infrastructure to make it work. Talk to the team about where to start.
FAQs
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.