Key Takeaways
- AI is used at every step of the investment process: data, signals, construction, optimisation, execution, monitoring and risk.
- Most of it supports human portfolio managers. Fully automated portfolios exist mainly in robo-advisors, such as Schwab Intelligent Portfolios, which starts at $5,000 with no advisory fee.
- Institutional platforms such as BlackRock’s Aladdin now include generative AI features (Aladdin Copilot) on top of whole-portfolio risk analytics.
- The biggest risks are overfitting, regime change and opaque models, so validation and explainability matter as much as accuracy.
AI in portfolio management is the use of machine learning, natural language processing and optimization algorithms to research investments, build and rebalance portfolios, manage risk and report to clients. This guide covers investment portfolios run by asset managers, advisors and robo-advisors. It is not about project portfolio management software, which shares the name but solves a different problem.
What is AI in portfolio management?
Portfolio management means deciding what to hold, how much of it and when to change it, within a client’s goals and risk limits. Since Harry Markowitz’s 1952 paper on portfolio selection, the core tool has been mean-variance optimisation: maximise expected return for a given level of risk. Artificial intelligence (AI) models change three parts of that process:
- Better inputs. Machine learning algorithms forecast returns, volatility and correlations from far more data, including alternative data and text.
- Better optimisation. Methods such as hierarchical risk parity and reinforcement learning handle noisy estimates and changing markets better than a single static optimisation.
- More automation. Monitoring, rebalancing, tax management and reporting run continuously across thousands of accounts.
The firms using it range from quantitative hedge funds and large asset managers to wealth advisors and consumer robo-advisors. Our related guide to Artificial Intelligence in asset management covers the generative AI side for asset managers specifically.
Traditional vs AI-driven portfolio management
| Traditional | AI-driven | |
|---|---|---|
| Data | Prices, fundamentals, analyst research | Adds alternative data, news, filings, transcripts, satellite and transaction data |
| Forecasting | Linear factor models, analyst judgement | Machine learning on non-linear patterns, with human oversight |
| Optimisation | Static mean-variance, periodic | Uncertainty-aware and regime-aware optimisation, run continuously |
| Rebalancing | Calendar-based (quarterly or annual) | Threshold- and signal-based, tax-aware |
| Personalisation | Model portfolios by risk band | Portfolios tailored to each client, including direct indexing |
| Risk monitoring | Periodic reports | Real-time exposure and scenario alerts |
| Scale | Limited by analyst time | Thousands of accounts per manager |
| Weakness | Slow to react, limited data | Overfitting, opacity, dependence on data quality |
How AI works across the investment process
1. Data and alternative data
Beyond prices and financial statements, managers now use earnings-call transcripts, news, regulatory filings, web traffic, card-transaction panels and satellite imagery. The computer-vision techniques behind consumer ai image editing tools are related to the ones quant funds use to count cars in retail car parks or measure oil-tank shadows from space. Cleaning and aligning this data is most of the work.
2. Signal generation
Models turn data into forecasts: expected return, volatility, earnings surprise or default probability. Gradient-boosted trees and neural networks capture non-linear relationships that linear factor models miss. Natural language processing applications score sentiment and topics in news and filings.
3. Portfolio construction
Signals are combined with constraints such as position limits, sector caps, ESG exclusions, liquidity and client preferences to propose a target portfolio.
4. Optimisation
Classic mean-variance optimisation is very sensitive to estimation errors. Alternatives include resampled optimisation, Bayesian shrinkage of inputs, and Marcos López de Prado’s hierarchical risk parity, which uses clustering to build more stable allocations. Reinforcement learning treats allocation as a sequence of decisions, as in Jiang, Xu and Liang’s deep reinforcement learning framework for portfolio management.
5. Execution
Trading algorithms slice orders to reduce market impact, and ML predicts short-term liquidity and costs to time execution.
6. Monitoring and rebalancing
Instead of rebalancing on a fixed date, systems watch drift, cash flows, tax opportunities and risk limits continuously, then trigger trades when the benefit outweighs the cost.
7. Risk and reporting
Risk engines calculate exposures, Value at Risk and stress scenarios in near real time. Generative AI drafts portfolio commentary and client reports. Generative AI for Data Analysis and Modeling explains how these reporting pipelines are built.
Use cases of AI in portfolio management
Asset allocation
ML forecasts of returns and risk feed strategic and tactical allocation across equities, bonds, cash and alternatives, adjusting weights as conditions change.
Real-time market monitoring
Models watch prices, news and positions continuously and alert managers to unusual moves, concentration build-ups or breaches of limits.
Factor investing
AI tests and combines factors such as value, momentum, quality and low volatility, and adjusts factor exposure as factor performance shifts.
Dynamic hedging
Models estimate when tail risk is rising and size hedges (options, futures, cash) accordingly, rather than holding a fixed hedge all the time.
Sentiment analysis
NLP scores the tone of news, earnings calls and social media to anticipate moves or flag reputational risk in holdings.
Regime-aware optimisation
Markets behave differently in calm, stressed and inflationary periods. Regime-detection models identify the current state and switch to the allocation or risk model that fits it.
Reinforcement-learning rebalancing
Reinforcement learning agents learn rebalancing policies that balance return, risk and trading costs over time. Most are still in research or limited production because they are hard to validate.
Tax-aware rebalancing and tax-loss harvesting
Algorithms harvest losses, avoid wash sales, choose tax lots and place assets in the right account types. Robo-advisors such as Schwab Intelligent Portfolios offer automatic tax-loss harvesting for eligible accounts.
Personalised model portfolios and direct indexing
Each client can hold a portfolio tailored to their tax position, values and existing holdings. Direct indexing replicates an index with individual stocks so losses can be harvested at the stock level.
Portfolio commentary and client reporting
Generative AI writes first drafts of monthly commentary and performance explanations from holdings and attribution data. Managers review and approve. More use cases of AI and Use Cases Of AI Agents apply the same pattern in other functions.
A worked example: one AI-assisted rebalance
To make the process concrete, here is how a typical AI-assisted rebalance runs for a balanced portfolio at an advisory firm. The numbers are illustrative, not a recommendation.
- Trigger. Overnight, the monitoring model notices that equities have drifted to 66% of the portfolio against a 60% target, beyond the firm’s 5-point tolerance band.
- Context. The system checks the client’s record: a large capital gain was realised earlier in the year, cash is due to be withdrawn next month, and the client excludes tobacco stocks.
- Proposal. The optimiser proposes trimming equities back to target, selling lots with losses first to offset the earlier gain, keeping enough cash for the withdrawal and respecting the exclusion list.
- Cost check. The execution model estimates trading costs and the tax impact. Because the tax saving outweighs the cost, the trade passes.
- Explanation. A language model drafts a two-paragraph note for the advisor explaining what changed and why, citing the drift, the tax lots and the cash need.
- Approval and record. The advisor reviews and approves. The trade, the reasoning and the approval are logged for compliance.
Every step is something a skilled human could do. What AI changes is that it happens for every account, every night, without anyone having to remember.
Generative AI and agents in portfolio management
Generative AI is mostly used around the portfolio rather than inside the optimiser: summarising research, drafting investment committee memos, answering “why did my portfolio change?” questions, and writing client commentary from attribution data. BlackRock’s Aladdin Copilot is an example of a natural-language layer on top of an institutional platform.
Agents go a step further. A research agent can read a company’s latest filing, compare it with the last one, update a model input and flag the change to the analyst. A rebalancing agent can run the steps in the worked example above and stop for approval. In regulated firms the rule is simple: agents may prepare and propose, humans approve anything that moves client money.
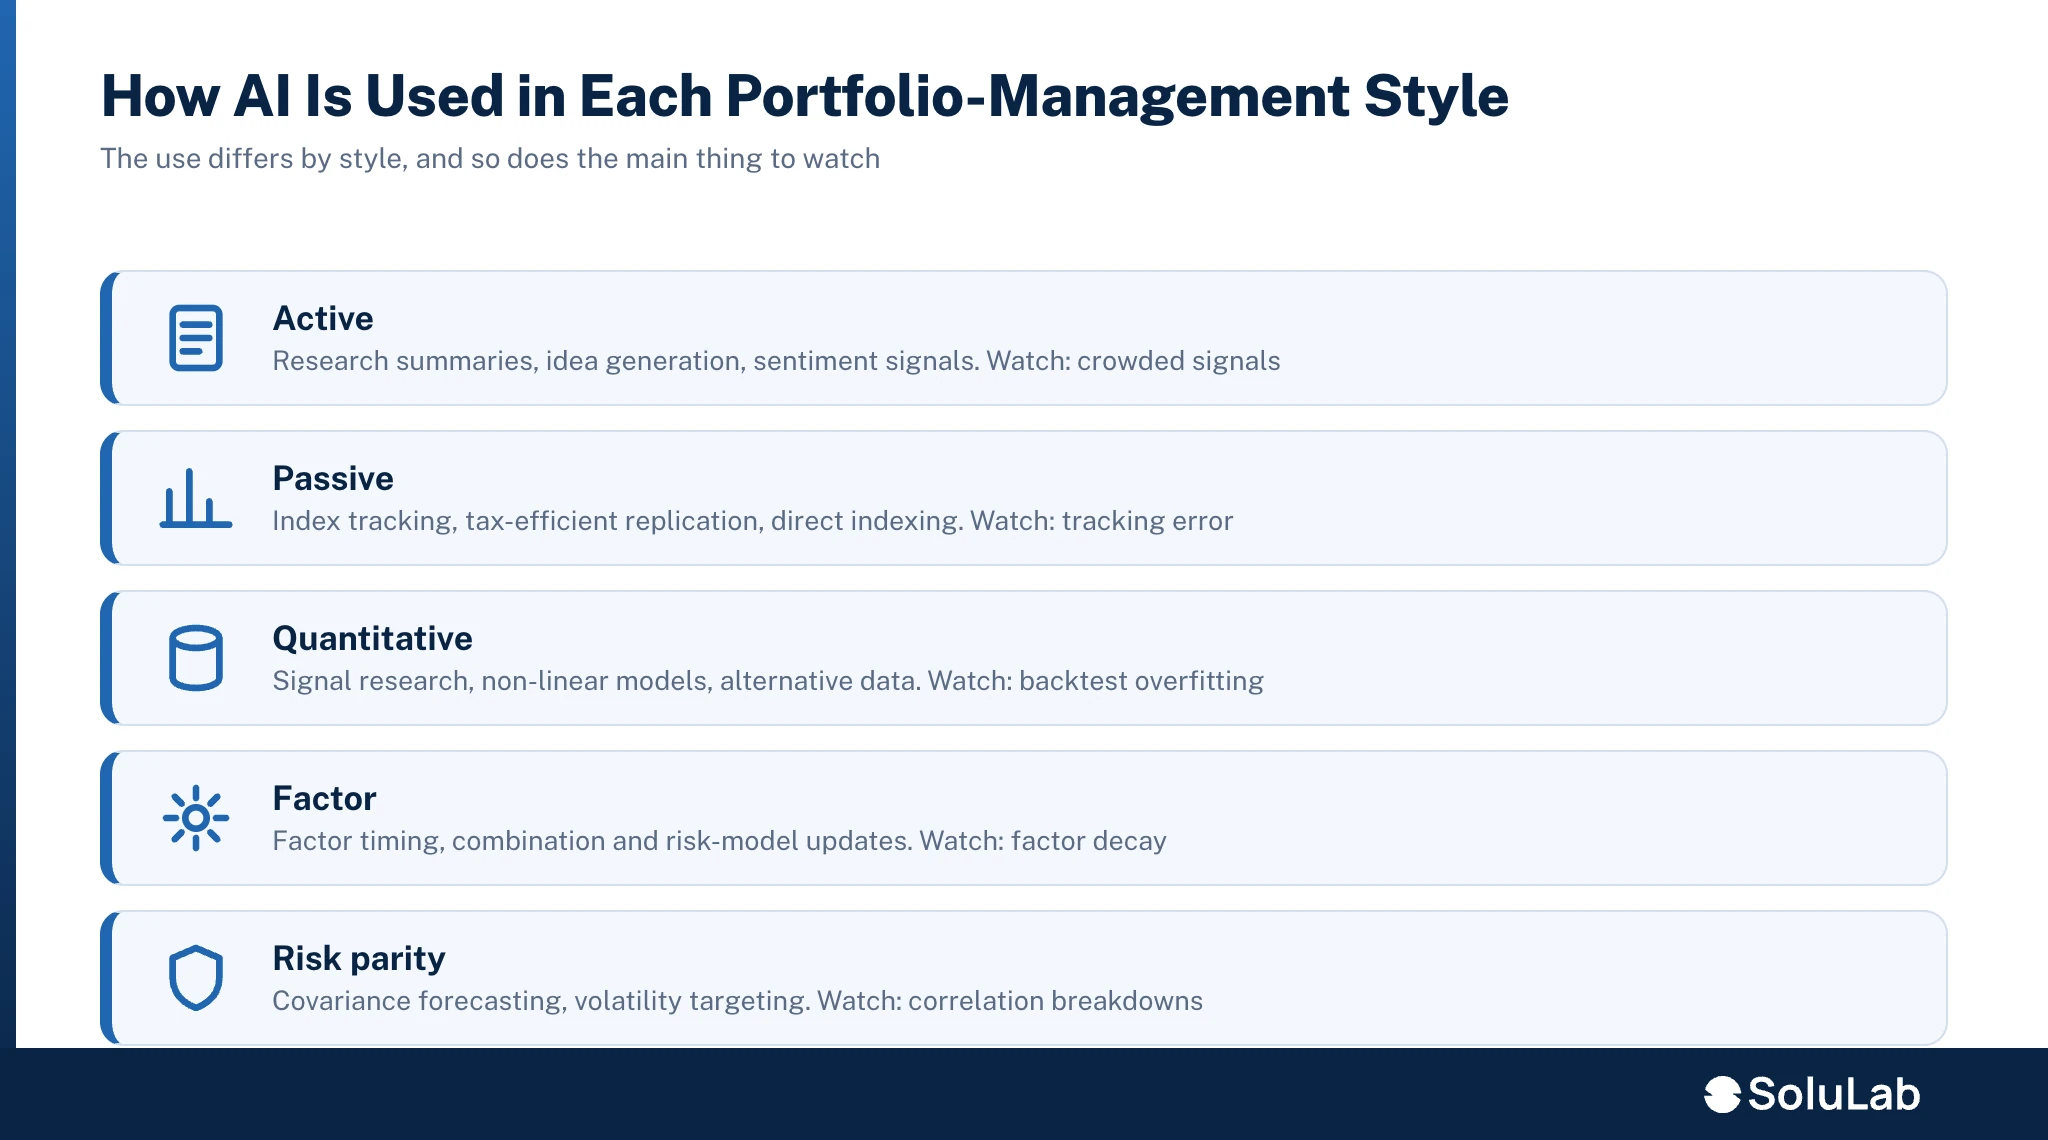
AI by portfolio-management style
| Style | How AI is used | Watch out for |
|---|---|---|
| Active | Research summaries, idea generation, sentiment and earnings-surprise signals | Crowded signals and overfitting |
| Passive | Index tracking, cash management, tax-efficient replication, direct indexing | Tracking error from optimisation shortcuts |
| Quantitative | Signal research, non-linear models, alternative data, execution | Backtest overfitting, data snooping |
| Factor | Factor timing, factor combination, risk-model updates | Factor decay and regime shifts |
| Risk-adjusted and risk parity | Covariance forecasting, hierarchical risk parity, volatility targeting | Borrowed exposure and correlation breakdowns in crises |
Who uses AI in portfolio management: real examples
| Organisation | What they use AI for | Who it serves | Source |
|---|---|---|---|
| BlackRock (Aladdin) | Whole-portfolio risk analytics across public and private markets, plus Aladdin Copilot | Institutional investors and asset managers | BlackRock |
| Charles Schwab | Schwab Intelligent Portfolios: automated allocation, rebalancing and tax-loss harvesting | Individual investors from $5,000 | Schwab |
| Vanguard | Digital Advisor: automated advice and portfolio management | Individual investors | Vanguard |
| Morgan Stanley | AI assistant and meeting tools for financial advisors | Advisors and their clients | Morgan Stanley |
Quant firms and hedge funds are heavy users too, but they publish little about their methods, so we have not listed claims we cannot source.
AI portfolio management tools compared
| Tool type | Examples | Who it is for | What it does |
|---|---|---|---|
| Institutional platforms | BlackRock Aladdin, other order and portfolio management systems | Asset managers, pension funds, insurers | Risk, analytics, compliance, trading and portfolio construction at scale |
| Robo-advisors | Schwab Intelligent Portfolios, Vanguard Digital Advisor | Individual investors | Automated allocation, rebalancing and tax-loss harvesting |
| Advisor platforms | Rebalancing, direct-indexing and model-marketplace tools | RIAs and wealth managers | Manage many client accounts against firm models |
| Investor research tools | AI stock screeners, portfolio analysers | Self-directed investors | Ratings, screening, portfolio health checks |
| Custom builds | In-house models on cloud data platforms | Firms with proprietary data or strategies | Signals, optimisation and reporting tailored to the firm |
Pick by the job, not the label. An RIA with 500 households needs rebalancing and tax automation, not an institutional risk platform. A manager whose edge is proprietary data needs custom models it controls. For wealth-side tools see our guide to AI in wealth management and agentic AI in wealth management.
Benefits, limits and risks
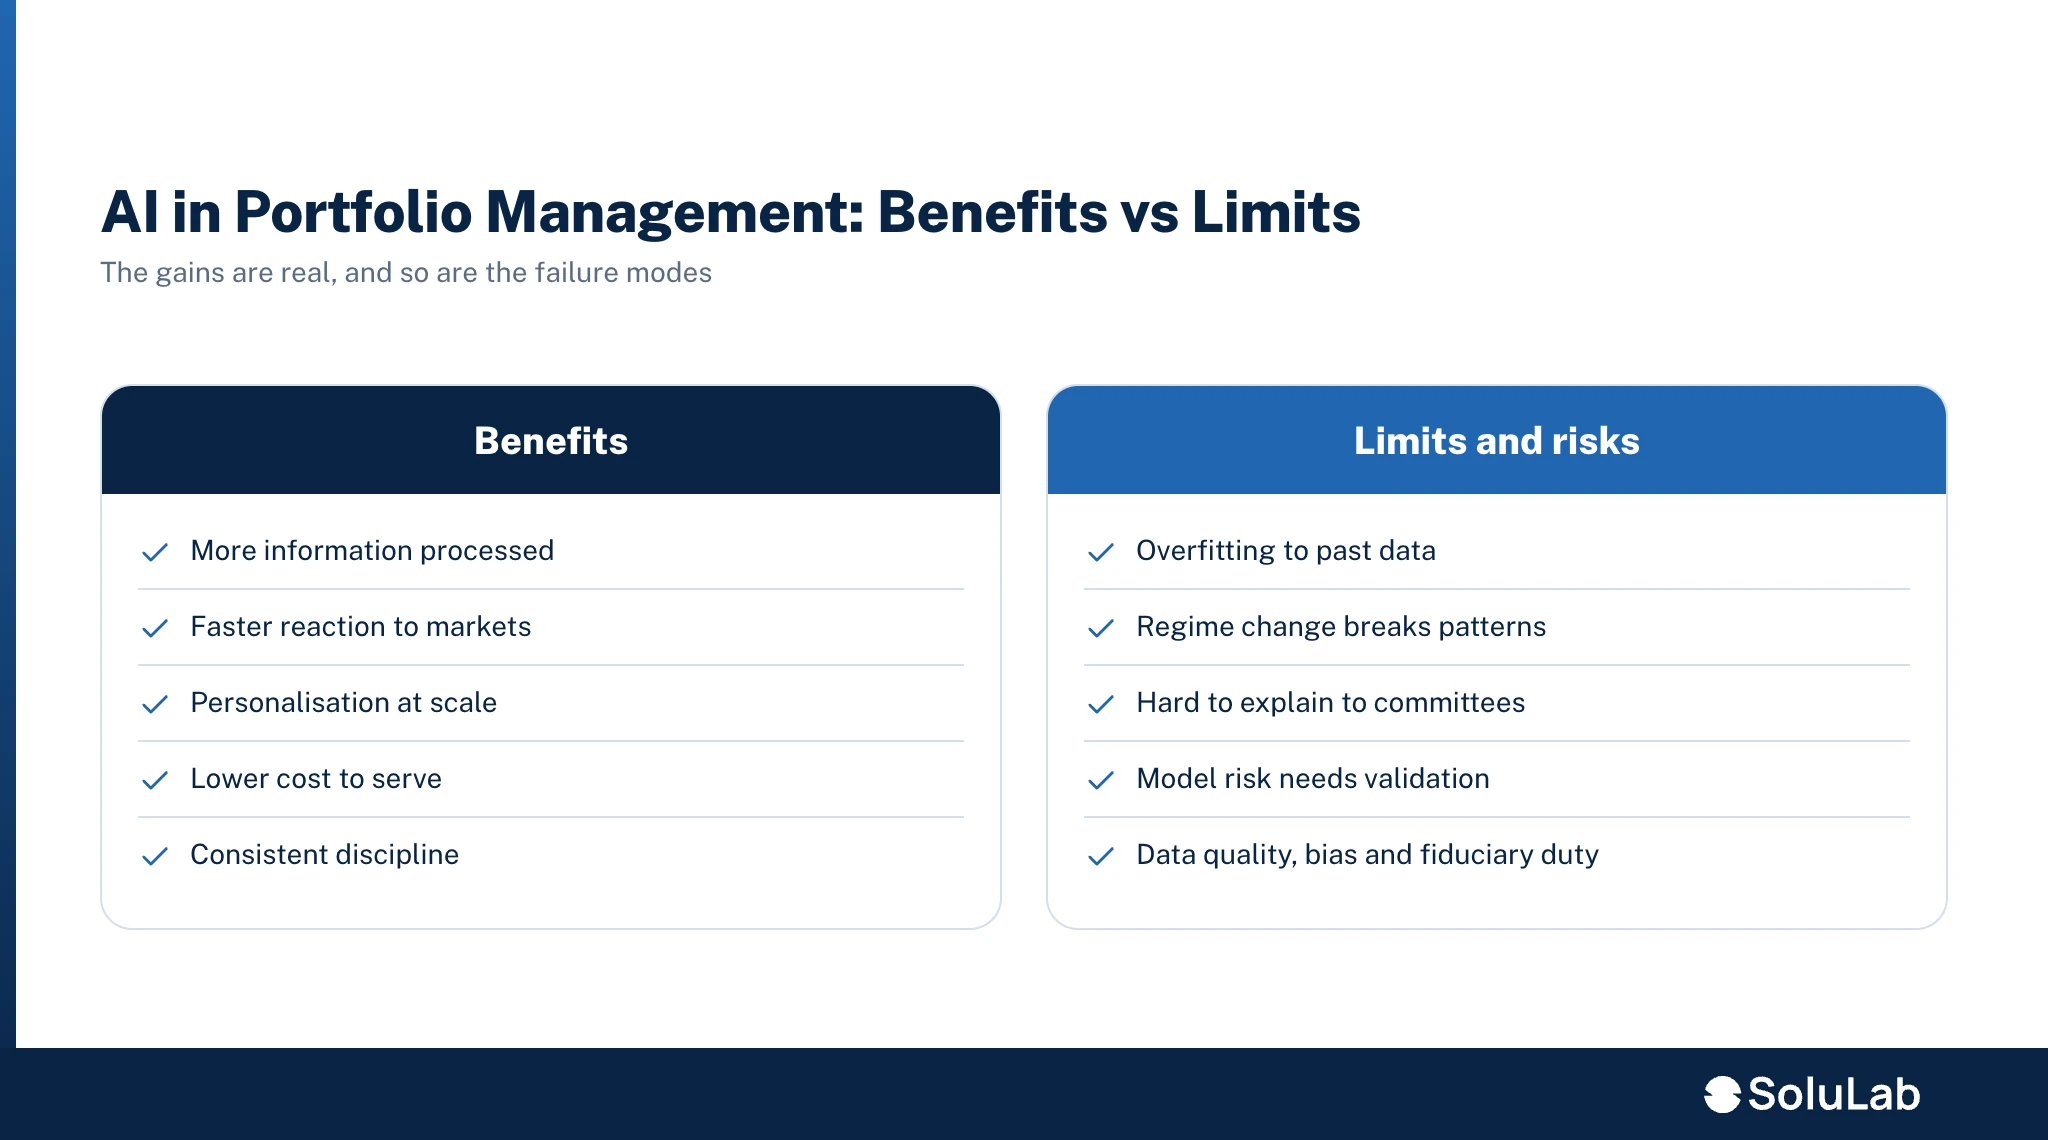
Benefits
- More information processed. Text, alternative data and real-time prices that no team could read manually.
- Faster reaction. Continuous monitoring and signal-based rebalancing instead of quarterly reviews.
- Personalisation at scale. Tax-aware, values-aligned portfolios for each client.
- Lower cost to serve. Automation makes small accounts economic, which is why robo-advisors can charge no advisory fee.
- Consistent discipline. Rules and models apply the same process every time, reducing emotional decisions.
Limits and risks
- Overfitting. A model that fits past data perfectly can fail on new data. Out-of-sample and walk-forward testing are essential.
- Regime change. Relationships learned in one market regime can break in another, as the 2020 pandemic shock and the 2022 rate rises showed.
- Explainability. Portfolio managers and clients need to understand why the portfolio changed. Black-box signals are hard to defend to an investment committee or regulator.
- Model risk. Every model needs validation, monitoring and a documented owner, following model risk management practice.
- Data quality and bias. Alternative data can be biased, incomplete or legally sensitive.
- Fiduciary duty. Using AI does not change the duty to act in the client’s best interest.
Governance and regulation for AI portfolio tools
- Fiduciary duty and suitability. Advisers must act in clients’ best interest whether a recommendation comes from a person or a model. In the EU, MiFID II suitability rules apply in the same way.
- FINRA. Regulatory Notice 24-09 confirms FINRA’s rules are technology neutral, so supervision and recordkeeping cover AI-generated content and recommendations.
- Model risk management. Banks and their asset-management arms follow the Federal Reserve’s SR 11-7 guidance: independent validation, ongoing monitoring and documented limitations for every model.
- Disclosure. Clients should know when algorithms manage or influence their portfolio, what the strategy is and what it costs.
- Data rights. Alternative data must be licensed and checked for personal information before use.
Questions to ask before buying an AI portfolio tool
- What exactly does the AI decide, and what does a human approve?
- How was the model validated, and can we see out-of-sample results that include trading costs?
- How does it behave in stressed markets, and how was that tested?
- Can it explain each trade in language a client would understand?
- How does it handle tax lots, wash sales, exclusions and client constraints?
- Which custodians and portfolio accounting systems does it integrate with?
- Where is our data stored, and is it used to train models for other clients?
- What is the total cost at our account volume?
Common mistakes when applying AI to portfolios
- Trusting a beautiful backtest. Testing hundreds of signal variations on the same history almost guarantees one looks brilliant by chance. Hold out data the model never sees, and count how many variations were tried.
- Ignoring costs and taxes. A signal that trades often can lose its edge to commissions, spreads and taxes. Always backtest net of realistic costs.
- Treating forecasts as certain. Feeding point forecasts straight into an optimiser produces extreme, unstable portfolios. Shrink estimates and cap position sizes.
- Automating before understanding. If the team cannot explain why a model wants a trade, it will not be able to defend the trade to a client or an investment committee.
- Using data you do not have rights to. Scraped or personal data can create legal problems that outweigh any signal value.
- No owner after launch. Models drift as markets change. Without a named owner reviewing performance every month, a model can quietly stop working.
Avoiding these mistakes matters more than choosing the most advanced algorithm. A modest model with disciplined validation usually beats a sophisticated one that was never stress-tested.
How to measure success
| Goal | Metric | Compare against |
|---|---|---|
| Better risk-adjusted returns | Sharpe ratio, drawdown, tracking error | The previous process or a simple benchmark model |
| Tax efficiency | After-tax return, harvested losses | Accounts without automated harvesting |
| Operational efficiency | Accounts per portfolio manager, hours per rebalance | Pre-automation workload |
| Faster risk response | Time from limit breach to action | Manual monitoring baseline |
| Client experience | Report turnaround time, client questions resolved | Previous reporting cycle |
Judge any model against a simple, transparent alternative. If a complex model cannot beat a well-built rules-based approach after costs, keep the simpler one.
How to implement AI in portfolio management
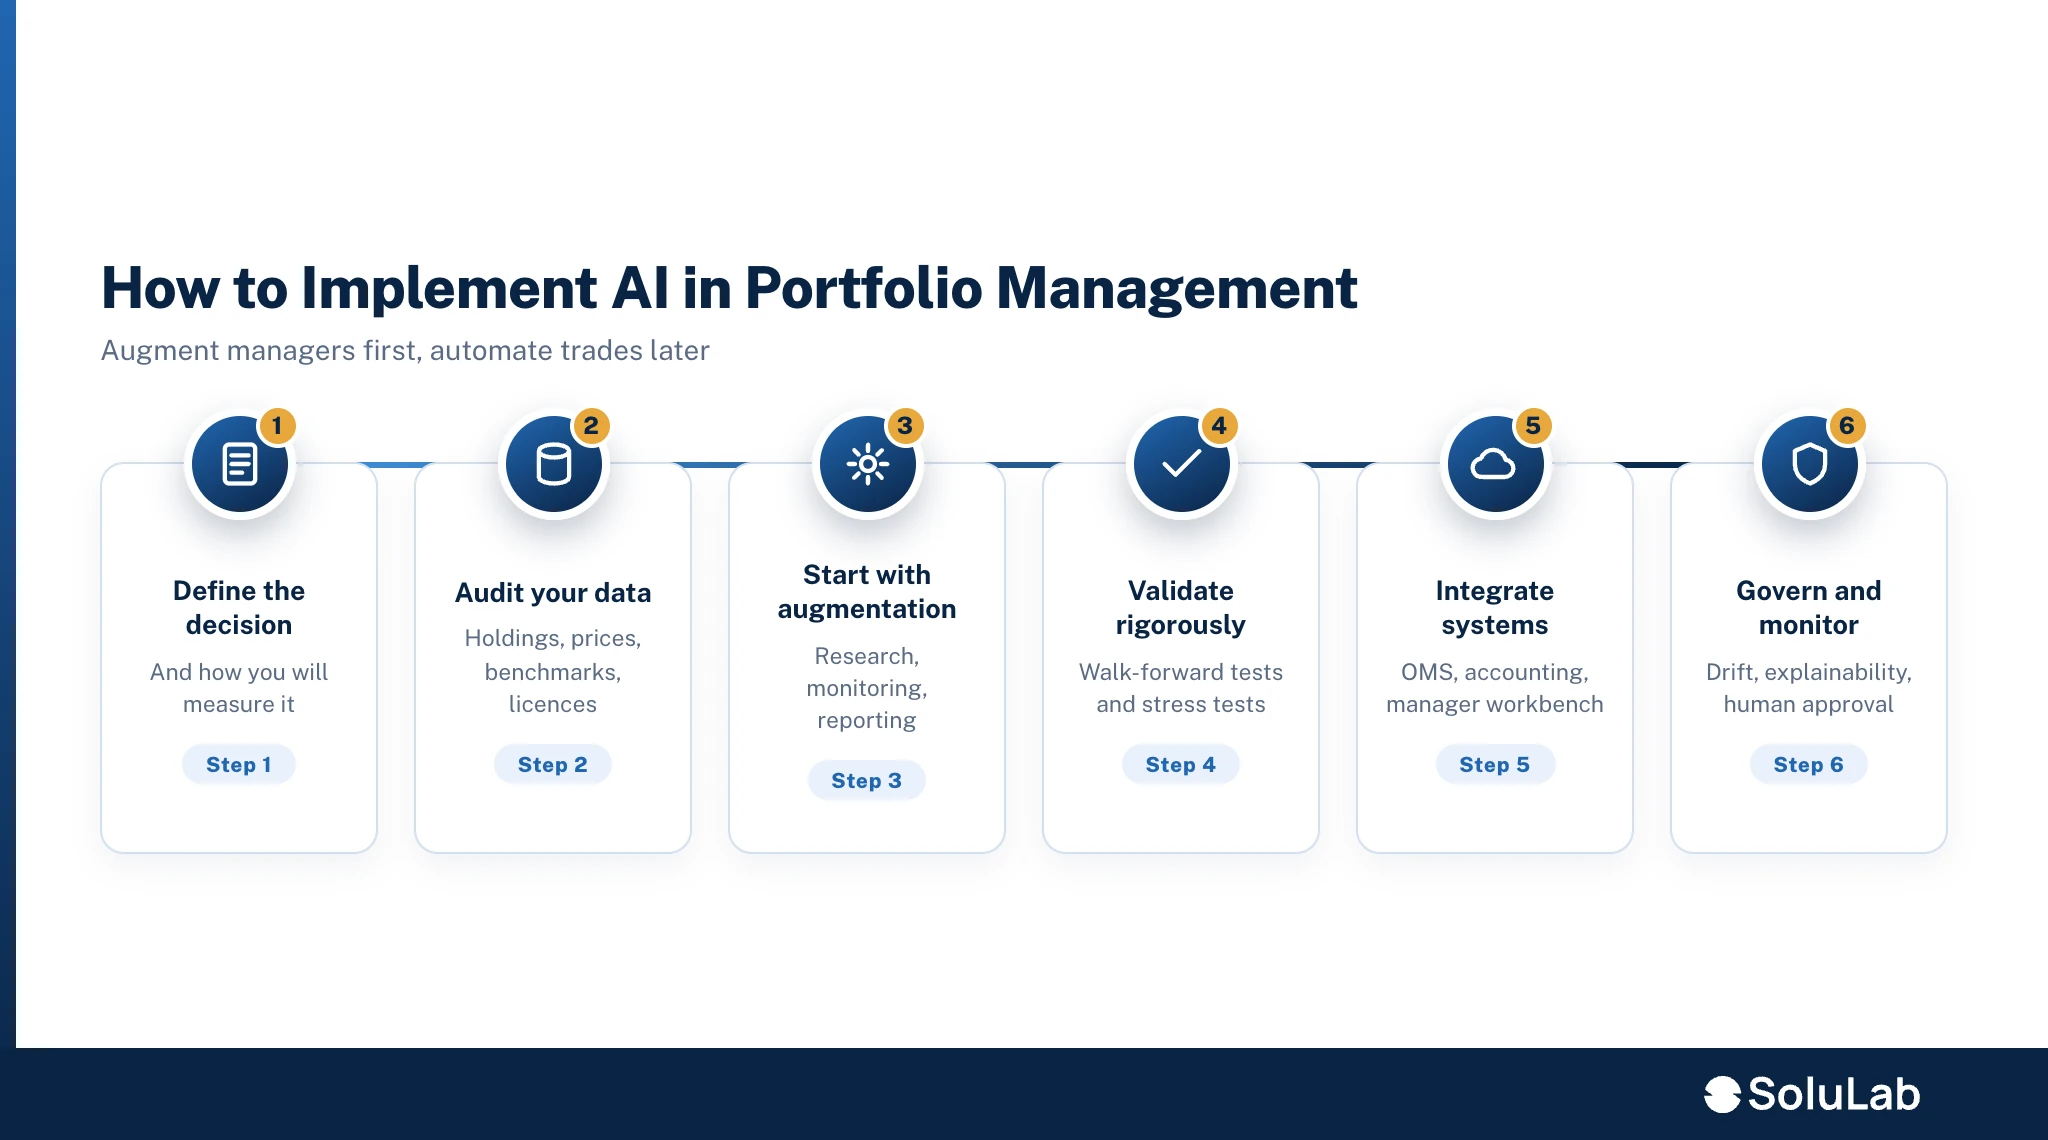
- Define the decision you want to improve, for example rebalancing frequency, tax alpha or risk-alert speed, and how you will measure it.
- Audit your data. Holdings, transactions, prices, benchmarks and any alternative data, with clear licences.
- Start with augmentation. Give managers better research, monitoring and reporting before automating trades.
- Validate rigorously. Walk-forward backtests, transaction-cost assumptions, stress tests and comparison with a simple benchmark model.
- Integrate with existing systems. Order management, portfolio accounting and the advisor or manager workbench.
- Govern and monitor. Model inventory, drift monitoring, explainability reports and a human approval step for material changes.
SoluLab is an AI development company that builds portfolio analytics, advisor copilots and reporting automation for asset and wealth managers. For one wealth firm, our advisory assistant cut portfolio preparation time by 58%. If you need engineers for a specific build, you can also Hire AI developers from our team. Artificial intelligence (AI) works best here as a decision-support layer that your investment team controls.
FAQs
Shipra Garg is a tech-focused content strategist and copywriter specializing in Web3, blockchain, and artificial intelligence. She has worked with startups and enterprise teams to craft high-conversion content that bridges deep tech with business impact. Her work translates complex innovations into clear, credible, and engaging narratives that drive growth and build trust in emerging tech markets.