

Insurance runs on one question: how risky is this person, this car, this building? Answering it fast, and answering it right, has never been easy. Claims crawl. Policy suggestions feel like they were pulled from a hat. Legacy systems were not built for either job.
AI agents change the math. They chew through far more data than a human team can, spot the patterns buried in it, and make calls while the customer is still on the line. Picture a tireless assistant that flags risk early, pushes claims forward instead of parking them, and matches a policy to the person in front of it.
Below, you get the mechanics: how these agents actually work inside an insurer, which use cases are pulling adoption, what a build costs, and where the return shows up.
Key Takeaways
- The problem: Slow processes, data scattered across systems that do not talk to each other, and decisions still made by hand. The result is claims that sit, policies that fit nobody, fraud that slips through, and a customer experience that changes depending on which channel someone picks.
- The solution: AI agents read data as it arrives, move claims through automatically, catch the patterns that signal fraud, and build policies around what a customer actually needs instead of which bucket they landed in.
- How SoluLab helps: We are AI-native, which means AI runs our own workflows too, not just the ones we ship. That shows up as faster builds, lower development cost, and insurance AI agents that hold up in production rather than in a demo.
What are AI Agents in Insurance?
An AI agent in insurance is software that takes over a piece of work an underwriter, claims handler, fraud analyst, or support rep used to own end to end. It reads the data, learns what normal looks like, and decides in the moment. Insurers get accuracy, speed, and personalization out of the same system.
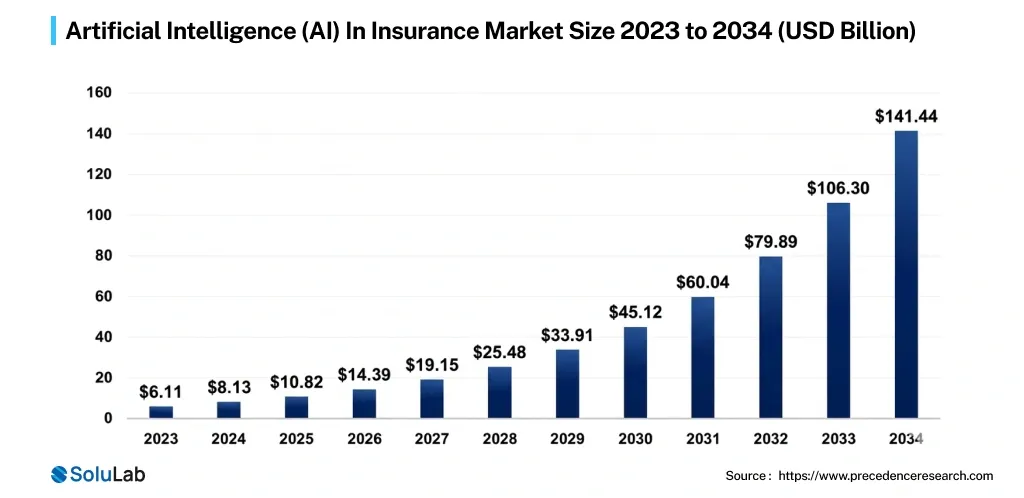
The global artificial intelligence (AI) in insurance market size is expected to reach USD 176.58 billion by 2035.
Under the hood, three things usually do the heavy lifting:
- Natural Language Processing (NLP): Reads and makes sense of human language
- Machine Learning (ML): Learns patterns from historical data
- Process Automation: Handles the repetitive insurance workflows nobody wants
How AI Agents in Insurance Work?
The short version: they automate the grind and sharpen the judgment calls, which pulls risk assessment and pricing closer to reality and makes the customer side less painful. Here is what that looks like step by step.
1. Data Collection
AI Insurance agents pull from wherever the information lives: customer applications, medical records, public records, prior history. Then the AI Agents for Insurance algorithms go looking for what a human reviewer would likely skim past, the correlations and risk factors hiding in the noise. Predictive modeling, clustering, and natural language processing do that work.
2. Risk Assessment
Insurance Agents with Artificial Intelligence can work through a volume of data no underwriting desk would get to, and turn it into risk profiles that hold up. Premiums get priced to the person. High-risk cases surface early. And the bias that creeps into manual underwriting has less room to operate.
3. Automated Claims Processing
AI for insurance agents take on first-pass claim assessment, document verification, and payment processing. Wait times drop. Errors drop. Policy gets applied the same way on a Tuesday morning as on a Friday afternoon, which is quietly the bigger win.
4. Fraud Detection
Fraud rarely announces itself. It shows up as a claim narrative that does not quite match the paperwork, or a run of claims tied back to the same individual or group. AI for life insurance agents catch those inconsistencies because they are looking at every claim at once, not one file at a time. AI Agents in Insurance cut losses that would otherwise go straight through to the bottom line.
5. Personalized Recommendations
AI tools for insurance agents read customer data and point to the products that genuinely fit that person’s situation. Satisfaction climbs, and so does retention. As insurers get better at this, the catalogue gets more specific too, down to options like prepaid funeral insurance, which let people plan for end-of-life expenses and leave their families with fewer open questions.
Key Benefits of AI Agents for Insurance Companies
Automation, data intelligence, and decisions made in real time. Combine those three across core functions and insurers get to move faster, grow without bloating, and treat customers like individuals.
- Scalability: Policy volume doubles, claim volume spikes, customer messages pile up. AI agents absorb all of it at once, so growth stops meaning more headcount, more infrastructure, and more coordination overhead.
- Cost Reduction: Underwriting, claims processing, and support all have automatable chunks. AI agents can automate 50–60% of claims processing tasks, cutting handling costs by 25-40%.
- Better Customer Satisfaction: Answers arrive in seconds instead of days, recommendations match the person asking, and the claim journey stops feeling like a fight. Trust follows, and so does renewal.
- Enhanced Accuracy: Large datasets plus live inputs means fewer human slips and tighter risk assessment. More to the point, the same case gets the same answer every time across underwriting, pricing, and fraud review.
- Improved Efficiency: Hand the repetitive, time-eating work to agents and turnaround times shrink. Your people get their attention back for the strategic calls and the messy customer conversations that need a human.
How to Build AI Agents for Insurance That Drive Automation?
Building AI agents in insurance is not a weekend project. You need clear objectives, data you can actually trust, and architecture that will not buckle at volume. Get those three right and the impact shows up where it counts: underwriting, claims, and customer experience.
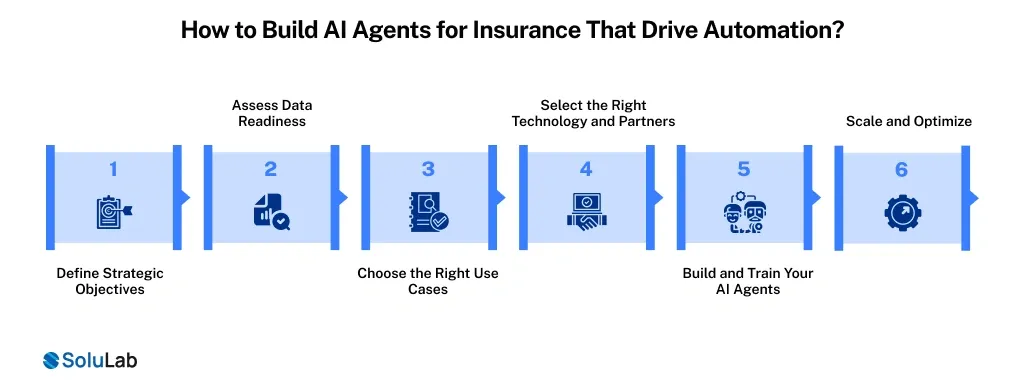
Step 1. Define Strategic Objectives
Tie the AI work to something the business already cares about. Shorter claims cycles. Sharper risk calls. A customer experience people mention unprompted. Vague ambition produces vague ROI.
- Identify key business challenges
- Align AI with revenue goals
- Define measurable success metrics
- Set a clear vision before execution begins.
Step 2. Assess Data Readiness
This is where most insurance AI projects stall. Model quality tracks data quality, and legacy insurers usually find their records scattered, duplicated, or locked in formats nothing else can read. Audit before you train.
- Audit internal and external data
- Ensure data quality and consistency
- Build secure data pipelines
- Strong data leads to stronger outcomes.
Step 3. Choose the Right Use Cases
Pick something with a visible payoff. Claims automation and fraud detection are the usual first moves for a reason: they produce a number you can show a board, and they scale once they work.
- Prioritize high ROI opportunities
- Start with simple implementations
- Validate impact with pilot projects
- Solve real problems, not theoretical ones.
Step 4. Select the Right Technology and Partners
Your stack and your build partner decide how fast you ship and whether regulators are satisfied when they come asking. Insurance is not a neutral domain to build in, and a partner who has not shipped in it will learn on your budget.
- Choose scalable AI infrastructure
- Ensure regulatory compliance readiness
- Partner with domain experts
- Technology decisions define long-term success.
Step 5. Build and Train Your AI Agents
Train on data that reflects your actual book, not a sanitized sample. Then keep training. Real interactions will surface edge cases your test set never imagined, and the feedback loop is what turns a decent model into a dependable one.
- Train models with real data
- Implement continuous learning systems
- Monitor model performance regularly
- Iteration is key to accuracy.
Step 6. Scale and Optimize
Once the pilot proves itself, widen the blast radius. Push the agents into adjacent workflows and keep tuning for speed, accuracy, and cost. Optimization is not a phase you finish.
- Expand across business functions
- Optimize for speed and accuracy
- Continuously monitor and improve
Applications of AI Agents in Insurance
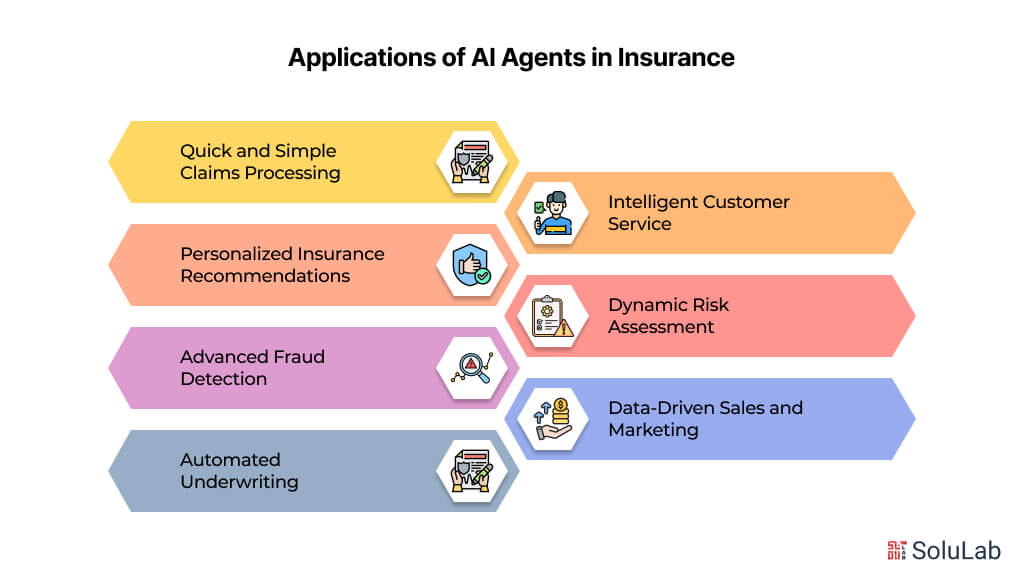
AI Agents for Insurance are rearranging how the work gets done, taking over routine tasks and adding services that were not practical before. Where AI and insurance meet in practice:
1. Quick and Simple Claims Processing
A customer files a claim from their phone. The agent gathers the supporting detail, verifies what it can, and starts the repair estimate before anyone at the insurer has opened the file. That whole sequence used to take days of back and forth.
2. Personalized Insurance Recommendations
Demographics, driving history, health records, lifestyle. AI Agents in Insurance read all of it together and land on a risk picture that is far more specific than a broad category ever produces. Premiums then reflect the individual, which customers notice, and which reads as fair rather than arbitrary.
3. Intelligent Customer Service
With AI-powered chatbots in place, a customer can ask a basic policy question at 2am, look up their own coverage details, and complete simple self-service steps without waiting for a call centre to open. No queue, no hold music.
4. Advanced Fraud Detection
The same database analysis runs quietly in the background, hunting for the trends and inconsistencies that suggest a claim is not what it says it is. The use cases of AI agents insurers by telling investigators where to spend their limited hours.
5. Dynamic Risk Assessment
Vehicle characteristics, traffic conditions, weather. Feed live signals like these into artificial intelligence insurance and risk stops being a number set once at policy inception. Pricing gets more honest. Drivers who behave well tend to keep behaving well when they know it counts.
6. Automated Underwriting
Insurance agent AI in underwriting clears the straightforward files off an underwriter’s desk and returns decisions faster. What is left is the complicated, judgment-heavy work, which is what you hired underwriters for in the first place.
7. Data-Driven Sales and Marketing
AI Agents for Insurance mine customer detail to work out which products belong on which channel, what the message should say, and when the person is most likely to care. Right offer, right moment, less budget burned on the wrong audience.
Cost of Insurance AI Agent Development
Budget depends on where you are starting. An early feasibility test and a fully integrated enterprise rollout are different animals, and the gap between them comes down to complexity, integrations, compliance load, and whether the system has to decide in real time.
| Stage | Estimated Cost Range | What It Covers |
| POC (Proof of Concept) | $10,000 – $30,000 | Basic prototype validating feasibility, limited data integration. |
| Multi-Workflow Implementation | $30,000 – $40,000 | Multiple use cases like underwriting, claims automation, and fraud detection. Includes API integrations, data pipelines |
| Enterprise-Scale Deployment | $50,000+ | Fully integrated AI ecosystem with multi-agent architecture, compliance (GDPR/insurance regulations) |
Future Trends Powering AI Development for Insurance Services
The centre of gravity has shifted. Insurance AI started as automation and is turning into systems that decide in real time, which changes underwriting, claims, and how customers experience the whole relationship.
- Explainable AI: A model that cannot show its reasoning is a regulatory problem waiting to happen. Insurers are backing transparent models that justify underwriting and claims decisions, which satisfies regulators and gives customers a reason to trust an automated answer.
- Hyper-Personalization: Behavioral, contextual, and live data feed agents that build products, pricing, and recommendations around one customer’s risk profile as it changes.
- Real-Time Risk Assessment: Hook into IoT, telematics, and wearables and you get continuous visibility into assets and behavior. Risk scores and pricing move with the signal instead of waiting for renewal.
- Autonomous Claims Processing: Agents are edging toward owning the full claims lifecycle, from document check to settlement, with no human in the middle. Time, cost, and manual touchpoints all fall.
- Embedded Insurance Models: Coverage appears inside the checkout or the ride-booking screen, at the exact moment it is relevant. No separate purchase journey, no second app.
- Regulatory-Aware AI Systems: Compliance is moving into the architecture itself. Platforms will adapt as rules like GDPR evolve, keeping operations secure, auditable, and defensible.
How SoluLab Helps Insurance Companies Build Production-Ready AI Agent Solutions?
Plenty of insurers have an AI pilot. Fewer have AI in production. We work on closing that gap, pairing insurance domain knowledge with AI-native workflows and architecture built to scale, so what gets deployed actually holds and the business outcome is something you can measure.
SoluLab is an AI-native company. AI shapes what we build and how we build it, which is why our cycles are shorter, our costs come in lower, and the agent systems we ship survive contact with a real insurance environment.
- AI agent development for insurance workflows
- Fraud detection and anomaly detection systems
- NLP-powered chatbots and virtual assistants
- Data engineering and model training pipelines
- API integrations with insurance platforms
- Compliance-ready AI architecture (GDPR, HIPAA)
- Predictive analytics and personalization engines
Take UpdateIA, which we built for a French startup. It is a multi-agent AI platform running 14+ autonomous agents under a coordinator named Jarvis. It tied together workflows across HR, CRM, Finance, and Legal, cut manual effort, kept compliance intact, and put better information in front of decision-makers while it still mattered.
Conclusion
Personalized risk evaluation is where AI agents earn their keep. Feed them live data, behavioral signals, and proper analytics and an insurer can write a policy for a person instead of for a category, which is what the industry has been promising for years without the tooling to deliver it.
Customers feel it in the experience. The insurer feels it in underwriting precision and fraud catch rates. Humans still need to sit over the top of these systems, but the share of complex work agents can carry alone keeps growing. SoluLab, a leading AI agent development company in the USA, brings a team that has spent years doing exactly this kind of work. On a health insurance powered by AI project, processing time came down by 70%, and the financial upside followed.
Got questions about where to start? Our AI and finance people are around. Get in touch with us today!
FAQs
Neha is a curious content writer with a knack for breaking down complex technologies into meaningful, reader-friendly insights. With experience in blockchain, digital assets, and enterprise tech, she focuses on creating content that informs, connects, and supports strategic decision-making.